Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 354

Bear markets are good for portfolio makeovers, not only bargains

Notching up record after record, financial markets are continuing to deliver unpleasant reminders of just how unprecedented the global pandemic crisis is. One recent record is the speed of the S&P/ASX 200 Index’s sudden slide to bear market status (defined as a 20% decline in pre-tax value from peak to trough). This slide took a mere 14 days in March, the quickest in the index’s history, easily eclipsing the next worst market slide of 55 days which signalled the onset of the GFC.
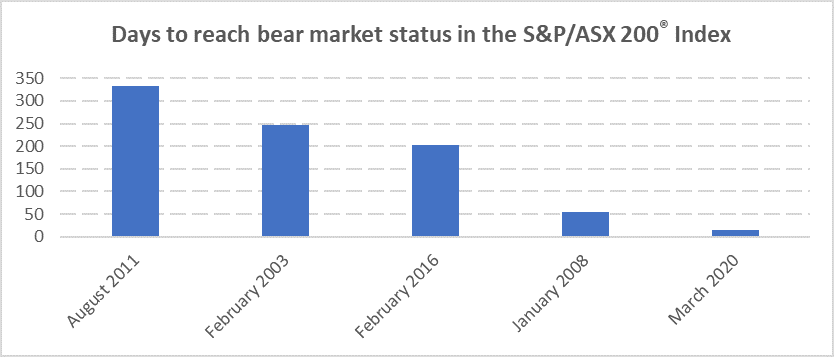
Source: Bloomberg, Parametric 31 March 2020. For illustrative purposes only. It is not possible to invest directly in an index.

Portfolio management in a crisis

A sophisticated approach to managing equities through this crisis period, as any large super fund will tell you, focuses on two things: first, avoid being a forced seller, and second, be well-positioned to take advantage of buying opportunities (which have been hard to find in recent years).

Despite fearmongering about the liquidity of large super funds in these extraordinary times, my conversations with super fund clients have been focused on the latter—tactical buying opportunities—not the risk of a debilitating run on funds and becoming a forced seller of equities. This suggests that, at least for these funds, liquidity is being well managed and will not be an issue.

Beyond the bargain-hunting opportunities for super funds (and other investors), there is a bigger opportunity available when bear markets hit—to give the whole equity portfolio itself a structural ‘makeover’.

As funds become larger and more sophisticated, they look to migrate their equity holdings from pooled investment funds housed in a legal trust structure (for example, ETFs and unlisted managed funds) across to separately managed accounts (discrete mandates) which give super funds direct ownership of the equities in their portfolios.

Pooled investment funds have their place as they are easy to use, ‘off-the-shelf’ ways to invest in equities. They shield the investor from much of the complexity and compliance burden of equity investing, which are instead borne by the product provider or pooled fund manager. But trends in the APRA-regulated super fund sector suggest funds are favouring more transparency, tax efficiency and customisation in equity investing.

The package of benefits that can be delivered in a separate account equity investment structure (with the right managers) but not through pooled funds includes:

  • specific ethical screens and values-driven investing
  • centralised portfolio management (CPM)
  • innovative fee structuring
  • tactical portfolio ‘tilting’
  • efficient transition management
  • after-tax investing
  • better assessment and management of portfolio risks, and
  • custom stakeholder reporting.

The window to restructuring a portfolio

Ironically, the strong returns on equities over the past decade (Australian, developed and emerging markets) have created a problem for super funds wanting to restructure their equity holdings—the capital gains tax liability they would incur in redeeming their investments from a pooled equity fund to seed a new separate account.

This kind of restructure can be done tax-free under US law, but not under Australian law, so beware literature from the US, which misleads Australian investors on this issue.

Consider a super fund wanting to transfer its $500 million equity portfolio from equity unit trust holdings into a separate account. The units have appreciated 25% since their acquisition, and 90% of the units are long-term holdings, with the remainder acquired in the past year. In isolation (and without tax-managing the transition), the fund faces a $10.5 million tax bill to restructure, or over 2% of portfolio value. While the restructure would deliver many benefits, the up-front tax bill is hard to swallow and a reason to delay the move and persist with what the fund believes is a sub-optimal structure.

Which brings us to the bear market conditions suddenly upon us. For super funds and others encumbered with ‘legacy’ investment structures and their embedded tax, now is an important window of opportunity for much more than just bargain-hunting—to re-cut the numbers to see just how much lower the tax cost of a move to their desired ‘future state’ for equity investing would be.

It is far more likely right now that the tax cost of a ‘portfolio makeover’ to move equities to a separate account structure would be immaterial or easily outweighed by the benefits. In our example above, the fund might even find that the current market value of its units in the equity trust has dipped below the original $400 million acquisition cost, which would actually deliver a windfall tax benefit if the fund seized the opportunity to restructure now.

While this ‘portfolio makeover’ opportunity represents a rare piece of good news for those navigating current market conditions, the cautionary lesson for super funds given the ASX bear market’s sudden, dramatic arrival is this: that predicting the market turnaround and speed and shape of the recovery (V-shape; U-shape; Nike ‘swoosh’?) will be fraught with difficulty.

The opportunity to not just find equity bargains, but migrate to a best-of-breed equity investment structure, is one to seize now, in case it vanishes just as fast.


Raewyn Williams is Managing Director of Research at Parametric Australia, a US-based investment adviser. This material is for general information only and does not consider the circumstances of any investor. Additional information is available at parametricportfolio.com.au.


  •   22 April 2020
  • 4
  •      
  •   
4 Comments
Jack
April 22, 2020

I agree this is a time for a clear out, but with my personal portfolio, what is especially disappointing is that many LICs which have been hopeless for years are now at even worse discounts.

Simon
April 24, 2020

If LICs were forced to offer a buyback at NTA say annually, there would be no discounts for very long. Unfortunately, it's like trying to squeeze blood out of a stone to get them to do that kind of shareholder friendly action.

David
April 23, 2020

I am a self funded retiree and I believe an intelligent individual. I understand the context of the article although I have had difficulty understanding a large amount of the terminology. As an example, "separate account equity investment structure", of the eight points I could relate (understand) two. The article has a number of similar statements. In my opinion the article could have been conveyed in much simpler terms.

Graham Hand
April 25, 2020

Hi David

We prefer to avoid articles which are too long, as readers are usually busy people. It is not always possible to explain concepts and terminology and some articles assume a level of knowledge. We have published over 3,000 articles and do not always repeat some earlier explanations.

For example, 'separately managed accounts' or similar have been covered a few times, such as:

https://www.firstlinks.com.au/top-three-ways-sma-helps-optimise-tax

https://www.firstlinks.com.au/four-drivers-growth-managed-accounts

https://www.firstlinks.com.au/5-flexible-features-managed-accounts

Raewyn has also provided other articles, as you can see by looking her up under 'Contributors'.


Leave a Comment:

RELATED ARTICLES

The ASX's 16-year drought: a rebuttal

How likely are market crashes?

Is more trouble coming for the 60/40 portfolio?

banner

Most viewed in recent weeks

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

Will you run out of money in retirement?

Fear of running out has become a defining retirement anxiety. Why do some retirees die with substantial wealth while others deplete their nest egg? Evidence suggests the answer is more complicated than we think. 

The investment that sidesteps the new tax traps

Tax rules have changed, but many investors are still using yesterday’s strategies. Insurance bonds may offer advantages for those seeking greater control, tax efficiency and certainty about their wealth.

Testamentary trusts have secured the CGT exemption

Treasury’s latest CGT reform draft delivers a win for testamentary trusts and deceased estates, exempting estate-derived gains from the 30% floor. However, questions on death and divorce rollovers remain unresolved.

Meg on SMSFs: What do we think about reversionary pensions these days?

Reversionary pensions have long been a staple of SMSF estate planning, but are they still the best option? Meg Heffron revisits a once-clear favourite and asks whether changing super rules have shifted the balance.

How does the 4% rule stack up?

The 4% rule has long been retirement's gold standard. But after a difficult period for investors, fresh analysis suggests a more conservative approach may significantly improve the chances of making savings last.

Latest Updates

Planning

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

Investment strategies

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

Economy

Population growth masks Australia’s productivity problem

For years, investors have benefited from a seemingly reliable growth story. But recent national accounts raise uncomfortable questions about what has really been driving Australia’s economy and whether that can continue unchecked.

Investment strategies

Why tomorrow’s winners may not be today’s index leaders

The stocks that built retirement balances over the past decade now dominate many portfolios. The new challenge is whether these companies can continue meeting the increasingly high expectations embedded in today's share prices.

Investing

What earnings surprises reveal about future returns

Sometimes the most important information in an earnings result isn't the number itself. It's the possibility that the market's assumptions have been fundamentally wrong and future earnings may look very different.

SMSF strategies

Individual SMSF Trusteeship directly liable for ATO fines

A rarely discussed detail buried in SMSF structures could dramatically change who wears the cost when something goes wrong. With penalties rising, a decision many dismissed as administrative may deserve a second look.

Investment strategies

The currency bet you didn’t know you made

Buying global shares means making two bets: on the companies and on the Australian dollar. Most investors consciously choose only the first. Last financial year, the second bet cost 8.5% in returns for many investors.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.