Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 179

Home ownership struggles will drive changes

Last month, I explained that without making any extra contributions, a 30-year-old couple would run out of super at age 75 if they needed a combined income of $59,160 a year after retiring at age 64.

But this isn’t the only problem facing many couples today. The cost of housing means that not only will they struggle to make extra super contributions, they will have real problems buying a home. Based on my experience with clients, it’s a major issue for almost every Australian under 30.

Who can afford a Sydney house?

A measurement of official house price data and mortgage costs by comparison website RateCity looked at the salary required for a single person to afford repayments on a 30-year loan. The main criterion was that the individual could not spend more than a third of their income on housing costs. Here are the results for Sydney:

  • Median House Price: $825,000
  • Loan Size: $660,000
  • Interest Rate: 4.74%
  • Monthly Repayment: $3,439
  • Annual Income Needed: $137,556

Are these figures an accurate reflection on what is happening? I would suggest not. First, few single first home buyers earn $137,556. Secondly, the median house price in Sydney is now a lot more than $825,000.
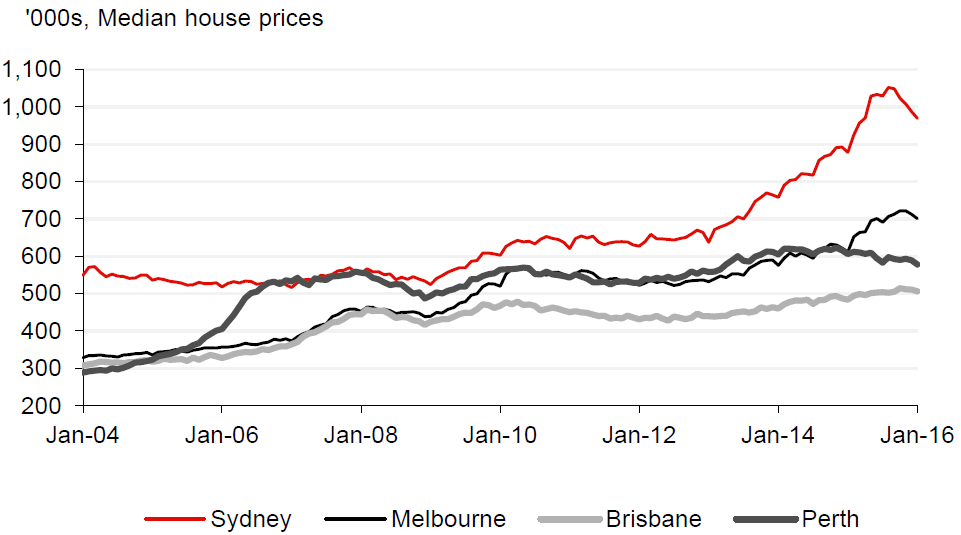

Source: Macquarie Equities, APS and UBS

Thirdly, people are clearly spending more than one third of their income on loan repayments. As you can see from the chart below, property prices are more than seven times average income levels.
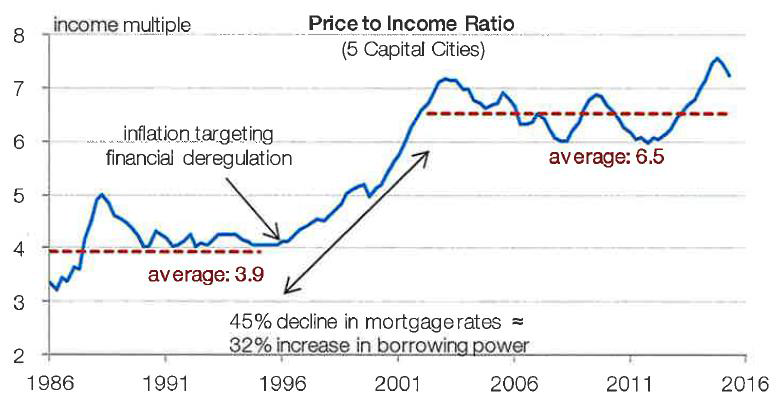

Source: Morgan Stanley and Macquarie Equities

What caused the surge from 1996 to 2003? Consumer confidence, immigration and housing shortages are possible reasons, but I suspect rising wages and dual household income earners were the key factors.

Whilst not many 30-year-olds earn $137,556, it’s quite possible that a 30-year-old couple can be jointly earning $120,000. Given the lower tax rates that two incomes generate over the single person, a 30-year-old couple could generate sufficient income at today’s interest rates to make the necessary mortgage payments listed above. However, home ownership in Australia has fallen from 71% to 67% in the last 20 years, and more significantly, for Australians aged between 25 and 34, the proportion has fallen from 39% to 29%, and for ages 35 to 44, from 63% to 52%. First home buyers now make up only 13% of new home loans.

Other buyers and finance sources

Obviously, there are far more people buying properties than only 30-year-old couples. Overseas buyers and investors appear responsible for much of the post-2010 surge, and favourable tax concessions are pushing homes out of reach for a high percentage of younger Australians.

Anecdotal evidence from clients suggests that the desire to get a foothold in the property market is causing many people to adopt strategies that are increasingly risky.

Living with parents is a popular solution to the housing problem, but that becomes strained after a while. Many parents now use equity in their home to finance a mortgage for their children. A major bank recently confirmed that 10% of its property loans were guaranteed by people other than the purchasers.

This is fine if the debt is not too large and the children can pay it off quickly. But the risks with this strategy are high. If the debt repayment becomes difficult due to unemployment, interest rate rises, a property downturn, divorce or an unexpected pregnancy, both the parents and the children could suddenly have a major cash flow problem. It wouldn’t take much for both to lose their homes.

Buying an investment property whilst living with your parents or renting is another popular strategy. This has some positives if the rent covers the loan interest and expenses while benefitting from a rising property market. Negative gearing allows an offset of the excess loan interest and costs (above rent received) against other income tax.

However, many investors underestimate the costs involved, especially if they never live in the property later. Land tax, capital gains tax, stamp duties, council rates, strata levies, repairs and maintenance, etc could render the whole venture uneconomic. Many people look to maximise deductions by taking out an interest-only loan, but this can backfire if the property is worth less than the loan when it comes to sell.

Policy inequity will lead to change

The idea of renting somewhere before buying and hoping for a significant decline in the housing market is not popular with my clients. The overwhelming feeling is that rent is dead money and pays off someone else’s mortgage. The reality is, though, that the vast majority of people under 30 have little choice but to adopt a ‘wait and see’ approach. Despite the inequality, the Federal Government appears to have little desire or perhaps ability to rectify this imbalance. Tax policies such as negative gearing and capital gains tax concessions favour those with capital or access to it, and even the Reserve Bank has admitted the tax breaks encourage investors to increase the prices they will pay.

Unlike in the US with the rise of Donald Trump, in the UK with Brexit and throughout Europe with the growth of right-wing parties, in Australia any middle-class resentment is still largely hidden. Although real wages and salaries have not increased much in recent years, the substantial rise in property prices has made large sections of the population feel much wealthier. However, negative gearing is the enemy of most Gen Y and Millennials wanting to find their own home, as they are outcompeted by investors. In my opinion, the days are numbered for negative gearing and the 50% capital gains tax discount in their current form.


Rick Cosier is a financial adviser and Principal of Healthy Finances Ltd. This article is general information and does not consider the circumstances of any individual.


  •   27 October 2016
  • 3
  •      
  •   
3 Comments
Ashley
October 26, 2016

First home buyers don’t buy the 'median' house, they buy in the bottom. Half of all houses cost less than the median, so they buy in the bottom quarter or lower! Now do the numbers and the story is far less pessimistic. If they’re whingeing with mortgage rates at 4%, wait till rates are 7% or 10%.

Bruce
October 27, 2016

The main reason that house prices surged between 1996 and 2003 was the change in Capital Gains Tax. As Peter Martin points out in an article in the SMH, In September 1999 the government halved the headline rate of capital gains tax, making negative gearing suddenly an essential tax strategy. Whereas before, renting out a house at a loss for tax purposes had been mainly an exercise in delaying tax, because the eventual profit made selling the property would be taxed at close to the seller's marginal rate; afterwards, with the profit taxed at only half the marginal rate, it became an exercise in cutting tax.

The Government knows that if it raised the headline rate for capital gains tax, even on future purchases, it would cause a slump in home prices because investors would leave the market. However, this change may divert investment into small and medium size businesses who still benefit from CGT exemptions when the money is paid into the superannuation fund of the owners. It would definitely make it easier for first home buyers to enter the market.

Paul
October 28, 2016

Thank you Rick for this concise summary of the problems facing first homebuyers. The spiralling of house prices relative to wage increases over the past 20 years has been caused by a number of factors (including low interest rates, relaxation of bank lending requirements and a surge in foreign investors) however it is the taxation disparities that appear to be hitting first homebuyers the hardest.

As you point out, "....negative gearing is the enemy of most Gen Y and Millennials wanting to find their own home, as they are outcompeted by investors." This is grossly unfair and (as a Grattan Institute Report earlier this year pointed out) it is out step with housing and taxation arrangements with most other countries. Successive Governments have done nothing to address this issue for fear of upsetting vested interests. It will deservedly be a 'voter issue' for prospective first homebuyers (and their parents) going forward.


Leave a Comment:

RELATED ARTICLES

New strategies to fix the housing crisis

Australian housing is twice as expensive as the US

Three ways to match housing affordability with good returns

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Latest Updates

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Latest from Morningstar

Does an American retirement rule work for Australians?

The 4% rule has survived decades of scrutiny, but Australia's retirement system changes the equation in ways most overlook. Before accepting or rejecting this rule of thumb, it pays to understand what really drives retirement outcomes.

Shares

Glencore lands on the ASX. Should BHP and Rio shareholders switch?

A coal-heavy miner with governance concerns isn't the obvious choice for investors. Yet, Glencore's ASX listing may offer something BHP and Rio can't. The challenge is working out whether the opportunity outweighs the risks.

Why does the system treat capital gains and losses differently?

Investors are often told not to let tax policy drive their investment decisions. Yet, under the new CGT rules, portfolio construction, volatility and even how assets are owned may have an outsized impact on their final outcome.

Economy

Three common sense reforms that Australia needs

What do frozen bank accounts, mortgage traps and pension penalties have in common? They're all symptoms of a system that makes life much harder. Yet the obvious solutions seem to have escaped the attention of Canberra.

Shares

The hidden cost of government debt for investors

Some of the important effects of rising public debt never make the headlines. Research shows the immediate effects may already be unfolding, influencing corporate behaviour in ways that many investors would never suspect.

Investment strategies

When do fundamentals matter?

Is fundamental investing losing its grip on markets? Investors continue to search for valuation-based explanations for every price move, but the dominant force behind short-term returns may be something else altogether.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.