Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 302

3 key risks: banks are too big to behave badly

It’s difficult to imagine the landscape without them. Indeed, history has shown that they’re too big to fail. However, revelations from the Financial Services Royal Commission have certainly taken a toll on how we perceive our major banks.

As investors, we have been long-term beneficiaries of the regular dividends they pay and yet some of the conduct uncovered has been reprehensible. So as investors, how should we look at banks in the future?

For me, there are three key areas to consider:

1) The importance of managing risk

Since the GFC, banks have made many changes to shore up what were already strong capital foundations. Capital ratios have risen almost three-fold in 10 years to ‘unquestionably strong’ levels. Liquidity management has also strengthened with banks switching to more stable sources of funding and increasing their holdings of liquid assets. As a consequence, Australian bank return on equity (ROE) has slightly decreased to around 12% but still remains strong by international standards (around 8% for large US banks).

Today, we’re largely at the tail-end of this shoring up process, although as highlighted by the Royal Commission, there’s still some work to do to mitigate operational risk stemming from poor culture. To date, the financial implications for ‘banks behaving badly’ have been relatively minor, but the consequences of reputational damage could significantly impact profitability if it continues.

2) A slowing credit market

In the last 12 months the credit market has noticeably slowed, as shown below. This is likely to continue, at least on the investor side, as a result of households becoming more cautious and banks tightening their lending standards. With household debt at high levels relative to global benchmarks, this isn’t altogether a bad thing. In fact, longer term it will have a positive impact on our financial security as Australia and the banks will be more resilient to a downturn.

Credit growth (six-month-ended annualised)
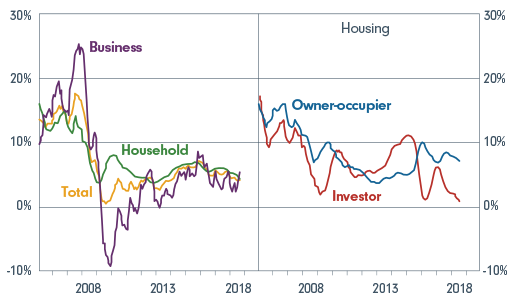
Source: APRA, RBA

Shorter term however it does have a couple of implications for the majors:

  • Fewer loans mean less profit.
  • Tighter lending practices mean more stringent checks and balances which increases the time it takes to process a loan application.

Tighter lending standards have meant more paperwork because it’s new and the process is still quite manual. Over time, it will become increasingly automated making the process much faster and importantly cheaper. We can expect to see technology projects replace people as the need to reduce the cost of labour intensifies.

3) Disruption from an intruder

In the last 10 years, we have witnessed some remarkable changes in market leadership in other industries. Established Goliaths have fallen as disruptors have swept in and completely sidelined their business models. So, could something like this happen to the major banks?

There will continue to be smaller companies which pick off individual niches. For example, OzForex in foreign exchange and AfterPay in payments. But when it comes to the core banking operations, Australian banks have invested heavily in technology particularly around service and convenience and a disruptor would have to offer something unique to displace them in a material way. This is especially true in banking, given the time it takes to establish the ‘trust’ many of us seek from our institutions.

Perhaps what strikes me most about Australia’s banks is their ability to adapt. Whether it be self-regulation to strengthen their financial health or investing heavily in technology to meet the changing needs of their customers, they really are the ultimate market chameleons. And they’ll need to be.

The GFC proved they were ‘too big to fail’ but today the message from the Royal Commission is clear - they’re 'too big to behave badly'.


Kate Howitt is a Portfolio Manager of the Fidelity Australian Opportunities Fund. This document is issued by FIL Responsible Entity (Australia) Limited ABN 33 148 059 009, AFSL 409340 (‘Fidelity Australia’), a member of the FIL Limited group of companies commonly known as Fidelity International. This document is intended as general information only. You should consider the relevant Product Disclosure Statement available on our website www.fidelity.com.au.

Fidelity International is a sponsor of Cuffelinks. For more articles and papers from Fidelity, please click here.

© 2019 FIL Responsible Entity (Australia) Limited. Fidelity, Fidelity International and the Fidelity International logo and F symbol are trademarks of FIL Limited. FD18634


  •   17 April 2019
  • 1
  •      
  •   

RELATED ARTICLES

The sorry tale of our big banks

The outlook for Australian banks

Clime time: A big win for bank customers against scammers

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Latest Updates

Retirement

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

2026 is not 1999

The US market looks eerily similar to the dot-com era with soaring AI spending and tech giants dominating returns. But one difference separates today’s boom from the dot-com bubble and it could determine what happens next.

Planning

Taxing time for trusts

Trusts are facing a shake-up, but an overhaul may not be necessary. Families can explore restructuring strategies that preserve succession and the asset protection benefits that have made these structures valuable.

Economy

Why the US economy is stronger than you might think

War, inflation and higher rates were expected to derail America. But has the market got it wrong? Three forces are driving the economy beyond expectations, revealing implications for stock prices and portfolio positioning.

Gold

How much trust is in your portfolio?

Everyone talks about diversifying assets. Far fewer think about diversifying trust. As inflation, debt and market assumptions collide, the question is whether portfolios need greater protection from unexpected outcomes.

Retirement

Retirement in reality - 7 months in

Seven months into retirement, I'm still uncovering surprises. This month was spent reflecting on the slow pace of health change, the myth of neatly scheduled part-time work and the unexpected persistence of retirement guilt.

The new geography of technology leadership

The next chapter of technology may not belong to the companies or business models many expect. As the landscape shifts, some opportunities are emerging in places that remain surprisingly overlooked by global markets.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.