Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 97

Has the FSI missed the elephant in the room?

The Financial System Inquiry (FSI) makes some important recommendations which would improve the industry if implemented. I agree with the recommendation to clearly define the objectives of superannuation, against which government policy and super fund activities would be assessed. Some of the language used such as “consumption smoothing” (the acknowledgment that the intention of super is to force us to save out of current earnings to provide for consumption when we are no longer earning wages) deserves credit for the way it can re-focus an industry. However the elephant in the room, the trade-off between return and risk, is largely left untouched. This lack of guidance was an important opportunity missed in the FSI.

The trade-off between return and risk is an age long topic. My reflections first address the accumulation focus of the industry and then I consider a retirement outcomes focus.

Risk versus return in accumulation phase

Until recent years much of the industry focus has been on superannuation balances at retirement. “How big will your nest egg be?” was a common phrase between industry and consumers. Trustees of super funds had to define the appropriate trade off between return and risk for the default members in their funds. The decision facing the trustee is illustrated in the diagram below.
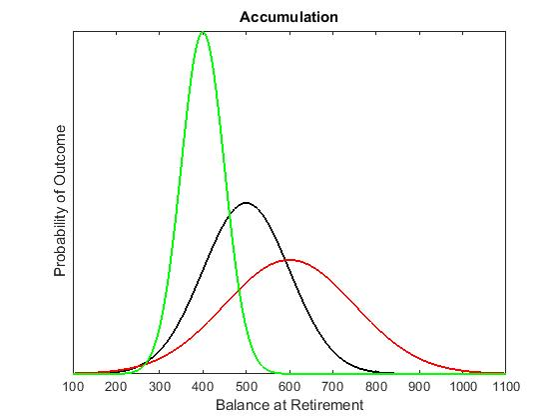
The above diagram is an illustration of the distribution of outcomes of a member’s balance at retirement once we account for expected contributions and performance. The black line represents the base case. A trustee could take more risk on the member’s behalf. Represented by the red line we expect the accumulation at retirement to be higher (assuming that a higher risk portfolio is expected to deliver higher returns). But the range of potential outcomes is wider, and some of the potential outcomes may be unpalatable. Conversely a trustee could reduce risk, as represented by the green line. The range of potential outcomes is narrower, representing more certainty, but (assuming that lower risk equates to lower expected returns) the expected size of the nest egg at retirement is reduced. Certainty and level of expected outcome pull against each other – yet both are desirable. Note the above analysis could be presented in real or nominal dollars, with real dollars the more appropriate approach.

This is broadly how the ‘70/30’ default portfolio evolved (70% growth assets such as shares and 30% defensive assets such as bonds), however I haven’t seen much compelling historical research that explains the origins of ‘70/30’. Indeed there is a possibility that ‘70/30’ was just back of the envelope analysis that took on an inertia-driven life of its own via peer group risk!

Risk versus return in retirement phase

Let’s now switch to the more recent focus on retirement outcomes. The same problem remains but it is more complex and detailed. And again the same ambiguity about the correct trade-off between expected outcome and variability of outcome exists. The diagram below looks similar but the subtle differences are important.
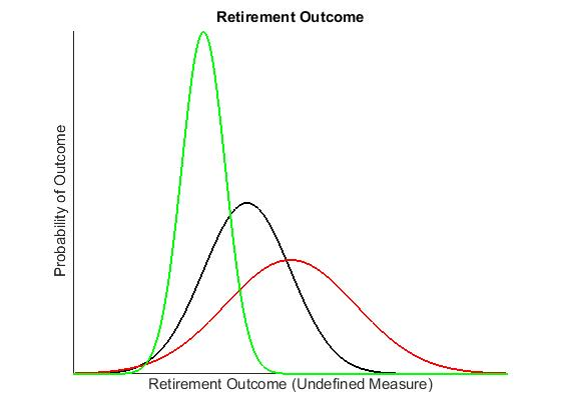
Notice the emphasis on the words ‘retirement outcome’. This is a complex topic: how do we define retirement outcome? I suggest it should include the following (but weighting these factors would be complex):

  • the level of retirement income
  • whether it is achieved through the entire retirement period (does it drop off or run out?)
  • the liquidity that is available to meet possible life events (such as a retirement home bond)
  • any bequest motive (though this is debateable and likely a secondary issue).

Given the definition of outcome is more complex it is not hard to imagine that measuring the variability of the outcome is also a more intricate exercise. Nonetheless the same framework is relevant: a trustee can make decisions which exchange the level of expected outcome for the opposite move in the variability of the outcome. Both are desirable, and indeed certainty of outcome should be valued and some people view certainty as a luxury. The projected outcome should be considered in terms of the expected outcome against the variability of the projected outcome.

FSI recommendations made without guidance on this trade-off

Alas what remains undefined and unguided by policymakers is the appropriate trade-off between expected outcome and variability of outcome. Every regulatory review, including the FSI, represents an opportunity to address the elephant in the room.

Without such guidance some of the recommendations made in the FSI appear somewhat less formed. Consider two important recommendations made: improving cost efficiency and developing a comprehensive income product for members’ retirement (CIPR) which addresses longevity risk. Let’s consider these in the outcome framework just outlined.

Cost reductions could increase net investment returns (if achieved through efficiency gains and the deletion of non-beneficial functions and services), or reduce net returns if it means more passive management for a fund that can add value through active management. Cost reductions may increase return volatility because less diversification opportunities into areas such as alternative investments will be available. So all up, a cost reduction focus may increase or may decrease net returns but will likely increase the volatility of returns. So at best this recommendation appears to be pulling the outcome in opposite directions – higher expected outcomes (assuming the FSI believes lower costs translate to higher returns and that active returns don’t exist) but greater variability of outcomes. In the absence of direction as to the appropriate trade-off between expected outcomes and variability of outcomes it is unclear whether such a recommendation will actually improve member outcomes or not.

What about all those other types of risk?

The FSI also recommends the creation of a CIPR to address longevity risk. On the surface, this is a worthwhile recommendation. However longevity risk is just one of many risks to retirement outcomes – investment returns, return volatility, inflation rates, wage growth, house prices, savings rates, mortality outcomes, age pension and taxes, just to name a few. There would be different costs (a negative impact on returns) in hedging these different risks. Perhaps it is cheaper to hedge a unit of investment risk than a unit of mortality risk. If so, then from an outcomes perspective it could be better to hedge a unit of investment risk before we hedge the mortality risk. It is also unclear which risk is most significant to retirement outcomes. What the FSI has done is paternally recommended that we prioritise the hedging of one risk over another, with little assessment of the cost of hedging the different forms of risk or the size of those risks. All this is in the absence of guidance as to the appropriate trade-off between expected outcome and variability of outcomes!

While product solutions such as the CIPR often appear the solution and can really define a regulatory review, it may have been more beneficial to recommend that funds develop more detailed processes and capabilities for modelling what retirement outcomes will look like. It would have been wonderful if a review addressed the elephant in the room, the appropriate trade-off between return and risk, including different types of risk.


David Bell is Chief Investment Officer at AUSCOAL Super. He is working towards a PhD at University of New South Wales. The views contained in this article are those of the author and not AUSCOAL Super.


  •   19 February 2015
  • 2
  •      
  •   
2 Comments
Tortoise
February 19, 2015

This dilemma partly explains why investors have started a SMSF. Everyone is different. A Trustee cannot solve this on a mass scale. What's good for one is not necessarily good for the next person.

David Brown
February 20, 2015

well - we don't have a collective system at all - we have individuals forced into collections of savers. David Murray quite rightly makes the point that collective risk management only comes from a DB system, that is reliance on each other and the average strength of the system is only ensured when savings are pooled. Our savings are pooled in terms of costs for investment management and admin - but are completely unique to each individual in terms of liabilities.

So in such a system - your elephants could never have been addressed.

Quite sensibly - the FSI chose instead to approach the problem from a different angle. Enshrining a "purpose" for Super gives the strength of law to re-orient the Trustee's obligations (and attention) back to the narrow purpose of delivering adequate retirement incomes. in this way the current Aussie trustee - free from the onerous obligation of liabilities - ie the members "own" their own unique liabilities - is now lumbered with that duty. It is a clever - and possibly too subtle way to unload the liability duty of care on the Trustees' doorstep.

Contrast this with DB trustees - who very much "own" the collective liability of the fund. If they fail to meet the liabilities - there is hell to pay from the sponsor (Govt, Company B/S) and regulator (whistle blowing actuaries). As such, I note a very different approach to returns, investment behaviour, asset classes and fees overseas in DB jurisdictions. In Australia, returns seem to be second or third priority ....behind brand strategy, political lobbying, and sponsoring sports teams. the reason is that at the end of the day, as long as one super fund is broadly in line with the returns on the Chant West survey, everything in the Trustee's world is OK.

Not all DB schemes do it well - but it is notable that the Super industry as a whole has delivered lower raw returns of DB funds like QIC, VFMC (or the FF for that matter). Even after a golden decade of the Australian economy, our long term returns are not as good as many US or Canadian DB schemes.

I suspect the FSI wasnt missing your elephant at all - but, instead tries to draw attention to the real elephant - ie : who is actually going to take responsibility for the liabilities???


Leave a Comment:

RELATED ARTICLES

CIPRs are coming and that’s exciting

'Utility function' research wins Retirement Innovation Award

Meeting the retirement outcome challenge

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Latest Updates

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Latest from Morningstar

Does an American retirement rule work for Australians?

The 4% rule has survived decades of scrutiny, but Australia's retirement system changes the equation in ways most overlook. Before accepting or rejecting this rule of thumb, it pays to understand what really drives retirement outcomes.

Shares

Glencore lands on the ASX. Should BHP and Rio shareholders switch?

A coal-heavy miner with governance concerns isn't the obvious choice for investors. Yet, Glencore's ASX listing may offer something BHP and Rio can't. The challenge is working out whether the opportunity outweighs the risks.

Why does the system treat capital gains and losses differently?

Investors are often told not to let tax policy drive their investment decisions. Yet, under the new CGT rules, portfolio construction, volatility and even how assets are owned may have an outsized impact on their final outcome.

Economy

Three common sense reforms that Australia needs

What do frozen bank accounts, mortgage traps and pension penalties have in common? They're all symptoms of a system that makes life much harder. Yet the obvious solutions seem to have escaped the attention of Canberra.

Shares

The hidden cost of government debt for investors

Some of the important effects of rising public debt never make the headlines. Research shows the immediate effects may already be unfolding, influencing corporate behaviour in ways that many investors would never suspect.

Investment strategies

When do fundamentals matter?

Is fundamental investing losing its grip on markets? Investors continue to search for valuation-based explanations for every price move, but the dominant force behind short-term returns may be something else altogether.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.