Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 580

Improving access to account-based pensions

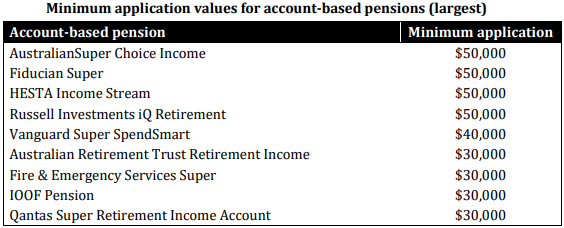
Why an estimated one million Australians aged 65 or above still have an accumulation account is not completely resolved. We noticed while researching this topic that minimum application amounts may be precluding some low-balance retirees from accessing account-based pensions (ABPs). We estimate that 50,000 Australians who are retiring over the next year may not be able to access an ABP because they do not meet minimum application requirements of their superannuation fund. The table below lists funds with the largest minimum ABP application amounts extracted from product disclosure statements (full list in Appendix of original paper). We briefly detail our concerns, acknowledge nuances, and suggest some steps forward for funds and policymakers.
Our concerns

We have a range of concerns over limiting ABP access for low balance members:

  • A retirement account provides access to a tax-free environment – Low balance members may miss out on a tax benefits could easily provide a 0.5% return uplift annually (relative to the comparable investment strategy applied in accumulation). This can have a meaningful impact on income and balance over longer periods. While somewhat coincidental, 0.5% is the threshold level used in the Your Future, Your Super performance test.
  • Exclusion from pension bonus – Members not meeting the entry requirements for their fund’s ABP will also be excluded from participating in any retirement bonus (where offered).
  • Effective member engagement – It is unclear what options are being presented to members with less than the minimum ABP balance requirements, and whether their super fund is engaging with them in a proactive manner including suggesting realistic next-steps. A generic message that there is a good retirement product while confronting members with minimum balance requirements that they may not meet seems like a poor communication practice, and may reduce member confidence.
  • System design not being made available to all – The design features of Australia’s retirement income system include an accumulation phase that taxes contributions and income and a retirement phase that is tax-free. Precluding low balance members from the tax benefits during retirement seems inconsistent with a fair and equitable system.

Nuances

We acknowledge that the problem is nuanced:

  • Many low-balance members withdraw their accumulation balances – Many low-balance members may not make use of an ABP even if available due to an intent to withdraw their balance – although it is challenging to identify the degree to which ABP take-up to date has been inhibited by account access or intentional choice. The extent to which lower ABP take-up is intentional reduces any business case challenges (next dot point), and would reduce the cost of reducing minimum ABP balance requirements.
  • Super funds face a business cost challenge – Operating a product with operational complexities and small balances is likely to be cost-ineffective, although this challenge is likely to shrink over time as the system matures and balances grow. However, small ABP balances is only one of many areas where super funds face member cross-subsidisation challenges. Other examples include operating and investment fees, insurance design, engagement programs, and retirement income strategy development costs. Whether avoiding cross-subsidisation across ABP members is appropriate is debatable.
  • Consideration of capital reserve or contingency accounts – The linkage between small ABP balances and the minimum drawdown rules warrants consideration. Many low balance retirees are currently required to draw a very modest income, but may be better off using their modest assets in super as savings they can access as and when required. This leads us to reflect on the merits of what we call a ‘contingency account’ in this Retirement Explainer, and Treasury called a ‘capital reserve’ in the appendix of their Superannuation in Retirement consultation paper. Such an account offers scope to allow low balance retirees to access a flexible source of funds while capturing tax benefits.

Our take

Some funds might do more to provide their low balance members with access to an ABP. The benefits would not only be financial, but also include more effective member engagement, and ultimately a fairer system. Given that we estimate 50,000 low-balance members will join the retiree cohort next year, we advocate for steps to be taken as priority. We call on super funds to consider their minimum ABP balances, and Treasury to continue exploring their capital reserve idea as a more appropriate match to the needs of low balance retirees. While the size of the affected cohort will likely shrink as the system continues to mature, this cohort will not entirely disappear, and a sizable number of Australian retirees appear to be impacted now. We think more should be done to assist these members.


David Bell is the Executive Director of The Conexus Institute. Geoff Warren is a Research Fellow with the Conexus Institute, and an Honorary Associate Professor at the Australian National University.


  •   2 October 2024
  • 6
  •      
  •   
6 Comments
mark
October 03, 2024

There would appear to be little merit in buying a pension with such a low starting balance given the associated costs and other viable alternatives.

David Bell
October 04, 2024

I'm careful not to assume that on behalf of people. For various reasons (such as financial literacy, professional management of assets, access to guidance) some low balance retirees may benefit from being able to roll their accumulation account into an account-based pension with their trusted super fund.

Aussie HIFIRE
October 05, 2024

I agree that the pension minimums should be reduced. However there are two obvious reasons why someone might be over age 65 and keeping their super in accumulation phase.

Firstly, they may have a spouse over age 67 who is eligible for a larger amount of age pension if their younger spouse's super isn't assessed for means testing due to being in accumulation phase.

And secondly, they may have already moved 1.9 mill into pension phase and are forced to keep the balance in accumulation phase if they don't want to withdraw it for a variety of possible reasons.

David Moxon
October 06, 2024

A member with a low balance in one fund may have money in another fund or funds. Over the years funds have spent considerable effort encouraging members to consolidate their super. For members who have chosen not to consolidate while working; retirement is surely a time when serious consideration should finally be given to doing so.

Peter Care
October 06, 2024

Why over 65 year olds have account based pensions? Many times it is s lack of understanding of how the super system works.
I had coffee with a friend who’s brother in law was a 65 year old bus driver who’s super was accumulation phase.
Turns out, the belief amongst the drivers is you cannot retire until you are 67 (age pension age) and you can’t touch your super until you retire.
With the working classes there is still so much misinformation out there. Even though his super fund provides regular information sessions (including after hours and online), my friend’s brother in law had never been to one.
I explained to my friend that as his brother in law had turned 65, he could contact his super fund and ask about converting his super from accumulation into an account based pension and thus pay zero tax on earnings rather than 15%. I also explained he did not have to quit his bus driving job to do this.
I also highly recommended he attend the next information session run by his super fund.
It is amazing how many people mix up the super rules with the age pension rules.

Ruth
October 11, 2024

What I always suspected over many years. They do not want you to access your own funds. Better to lock it up so they obtain fees. Sadly, you have no choice as the law says increasing parts of your pay must go to these funds, whether you like it or not. You might for example prefer to buy a home.
Imagine what it will be like in 5, 10, 15, 20 years or more. Will you see your funds after they have been ravaged by inflation and the government needs them to solve their debt problem? The last time we were this far in debt was WWII.


Leave a Comment:

RELATED ARTICLES

2 billion reasons to fix retirement income

Large funds need to earn retirement loyalty

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Latest Updates

Retirement

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

2026 is not 1999

The US market looks eerily similar to the dot-com era with soaring AI spending and tech giants dominating returns. But one difference separates today’s boom from the dot-com bubble and it could determine what happens next.

Planning

Taxing time for trusts

Trusts are facing a shake-up, but an overhaul may not be necessary. Families can explore restructuring strategies that preserve succession and the asset protection benefits that have made these structures valuable.

Economy

Why the US economy is stronger than you might think

War, inflation and higher rates were expected to derail America. But has the market got it wrong? Three forces are driving the economy beyond expectations, revealing implications for stock prices and portfolio positioning.

Gold

How much trust is in your portfolio?

Everyone talks about diversifying assets. Far fewer think about diversifying trust. As inflation, debt and market assumptions collide, the question is whether portfolios need greater protection from unexpected outcomes.

Retirement

Retirement in reality - 7 months in

Seven months into retirement, I'm still uncovering surprises. This month was spent reflecting on the slow pace of health change, the myth of neatly scheduled part-time work and the unexpected persistence of retirement guilt.

The new geography of technology leadership

The next chapter of technology may not belong to the companies or business models many expect. As the landscape shifts, some opportunities are emerging in places that remain surprisingly overlooked by global markets.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.