Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 297

Retirement planning is not just about income

The proposed changes to dividend imputation rules highlight one of the potential risks of a concentrated, home-biased, income-oriented portfolio.

It’s clear that investors who rely on dividend imputation credits for income will have an important decision ahead as to how to restructure their portfolio should this proposal come into effect.

Because we believe that an income-only strategy can create heightened risk in a portfolio and limit its potential for capital growth, we are strong proponents of the concept of total return investing – or investing for cash flow and capital appreciation.

Our research shows this to be a lower risk approach, in particular for those in the drawdown phase of their investment lifecycle.

Better not to focus only on income

Instead of constructing the portfolio to align income yield with spending requirements, a total return approach intends to align the portfolio’s asset allocation with the investors spending goals and risk tolerance.

This approach advocates keeping your portfolio broadly diversified at a low cost and focused on the overall, or total, return. Where the need for additional income occurs over and above the yield generated by this broadly diversified portfolio, the investor spends the amount made from the overall portfolio - or the total return - rather than switching around holdings to generate additional yield.

Changes to tax rules naturally provoke public debate because of the impact on the way investors have structured their portfolios but there are a couple of reasons why the total approach may be beneficial to the long-term health of your investment portfolio.

First, an income approach often spends the natural yield of the portfolio which may either exceed the spending requirements or it may fall short. This approach pays too little attention to the capital base, which can result in the portfolio being eroded by inflation and failing to last the duration, or retirees underspending from their portfolio and living an unnecessarily frugal retirement.

Second, an income-orientated portfolio may not align with the investors actual risk tolerance, which is particularly relevant in Australia, where portfolios are often concentrated in a small number of shares to generate the desired income yield. In particular, financial sector shares in Australia are commonly overweighted. Financial sector shares comprise around one-third of the Australian market, and around 36% of dividends paid.

In this way, being too focused on the income yield of the portfolio can mean you miss out on the importance of portfolio diversification across sectors and asset classes, replaced by a need to achieve a higher income yield.

Equally, overweighting higher yield bonds in the same pursuit of higher income can expose the investor to moderate or even significant credit risk, heightening volatility in the portfolio. Higher yield bonds display different characteristics to investment grade government and corporate bonds, which are a better diversifier in your portfolio to equity risk than high yield bonds.

Summary of negative portfolio impacts resulting from common investor practices
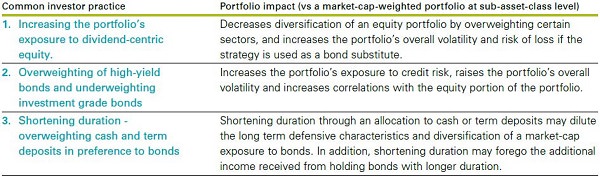
Source: Vanguard. From Assets to Income: A goals-based approach to retirement spending

Controlling withdrawals of capital

In contrast, by focusing on the entire return earned by the portfolio, rather than its individual components, a total-return approach maintains a portfolio’s diversification and allows for better alignment with investment goals. Investors also have more control over the size and frequency of withdrawals. This is particularly useful when considering how to incorporate other financial resources, such as the age pension, into a retirement plan.

Some industry commentators have voiced concerns that investors may be prey to faddish income strategies should Labor’s proposal for franking credits come into play. But by taking a sensible, diversified approach and investing for both income and growth, investors can sidestep some of the pitfalls associated with the hunt for yield.


Aidan Geysen is Head of Investment Strategy at Vanguard Australia, a sponsor of Cuffelinks. This article is for general information purposes only and does not consider the circumstances of any individual.

For more articles and papers from Vanguard Investments Australia, please click here.


  •   13 March 2019
  • 5
  •      
  •   
5 Comments
Frank
March 14, 2019

Agree, it has not helped many people in the last few years to have Australian-centric dividend portfolios, missing out on the great gains made in the S&P500 over the last decade while bank share prices are down.

Dudley
March 14, 2019

"great gains made in the S&P500 over the last decade":

Correlated with what central bankers 'had for breakfast'.

Maurie
March 15, 2019

When companies contemplate acquiring businesses, they are interested in the future cashflows. The price in the market is simply the cost of doing business (acquiring that future income stream). Why don't investors use the same philosophy. The concept of total return is a bit of a furphy for me. As soon as I press the button to realise a capital gain, I am effectively giving up the future income stream associated with share ownership. For someone who bought CBA in 1996 (5 years after the float), the current years dividend payment has increased five-fold and produces current year ROI of 35%. That compares pretty well even in inflated adjusted terms. Total return becomes irrelevant when you look at the big picture.

Geoff
March 17, 2019

I tend to agree, if you have the time to allow such things to mature. By my calculations, over the last 20 years, even a share as conservative as Argo has increased twice as fast as inflation.

But nothing is set and forget, and a low inflation environment over most of that period has undoubtedly helped, and should that change, then a re-examination of one's assumptions would be wise.

SMSF Trustee
March 17, 2019

No, Maurie, no, no, no

Even the example of CBA that you have given, the fact is that the share price has also gone up about 3-fold during that time (approx $25 to approx $75 depending on exactly when you bought and what day it is now). That also provides the capacity to help fund retirement by selling shares to generate cash flow.

And that puts you in a better position financially than someone who bought a share that has increased its dividend by the same, but where the share price is, say, little changed.

Or a share whose dividend has increased a lot and whose share price has done even better. Say BHP, dividend up 4 fold from the late 1990's (50 cents to $2) and share price up from $3 to $35 over that period. Owning BHP over the period would put you in a much better situation than owning CBA, even though the dividend income has grown really well.

So many people cite CBA among the banks, but what about NAB? Over the time period you've talked about they've only doubled their dividend (or a bit better - from 90 cents to $2 a year) and their share price is about the same. The income side tells you one story, but the total return tells you a completely different one.

Total return is really important because investment return is not just about dividends and over time it's the combination that determines how well off you are compared to when you started.


Leave a Comment:

RELATED ARTICLES

How much super should you have?

Is this your biggest retirement worry?

Strangers to themselves in retirement

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Latest Updates

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Latest from Morningstar

Does an American retirement rule work for Australians?

The 4% rule has survived decades of scrutiny, but Australia's retirement system changes the equation in ways most overlook. Before accepting or rejecting this rule of thumb, it pays to understand what really drives retirement outcomes.

Shares

Glencore lands on the ASX. Should BHP and Rio shareholders switch?

A coal-heavy miner with governance concerns isn't the obvious choice for investors. Yet, Glencore's ASX listing may offer something BHP and Rio can't. The challenge is working out whether the opportunity outweighs the risks.

Why does the system treat capital gains and losses differently?

Investors are often told not to let tax policy drive their investment decisions. Yet, under the new CGT rules, portfolio construction, volatility and even how assets are owned may have an outsized impact on their final outcome.

Economy

Three common sense reforms that Australia needs

What do frozen bank accounts, mortgage traps and pension penalties have in common? They're all symptoms of a system that makes life much harder. Yet the obvious solutions seem to have escaped the attention of Canberra.

Shares

The hidden cost of government debt for investors

Some of the important effects of rising public debt never make the headlines. Research shows the immediate effects may already be unfolding, influencing corporate behaviour in ways that many investors would never suspect.

Investment strategies

When do fundamentals matter?

Is fundamental investing losing its grip on markets? Investors continue to search for valuation-based explanations for every price move, but the dominant force behind short-term returns may be something else altogether.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.