Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 163

Britain, Brexit and Australia

Countless articles have been written on Brexit, but most focus has been on the immediate panic selling after the vote. This commentary adds more context to the debate.

Britain’s long history of trading with Australia

As a British colony, Australia was heavily reliant on Britain for investment capital and export revenue. Prior to Federation in 1901, Britain bought virtually all of our exports (mainly wool and gold), making Australia one of the richest countries in the world per capita.

Britain remained our largest export partner until 1940, when it fell to second behind the United States. After the War our export mix changed dramatically, playing a vital role in the reconstruction and reemergence of Europe and Japan. By 1967, Japan’s hunger for our iron ore and coal made it our largest export partner, remaining in that position until it was superseded by China in 2010.

The chart below shows the declining role of Britain in Australia’s export revenues since the 1800s.
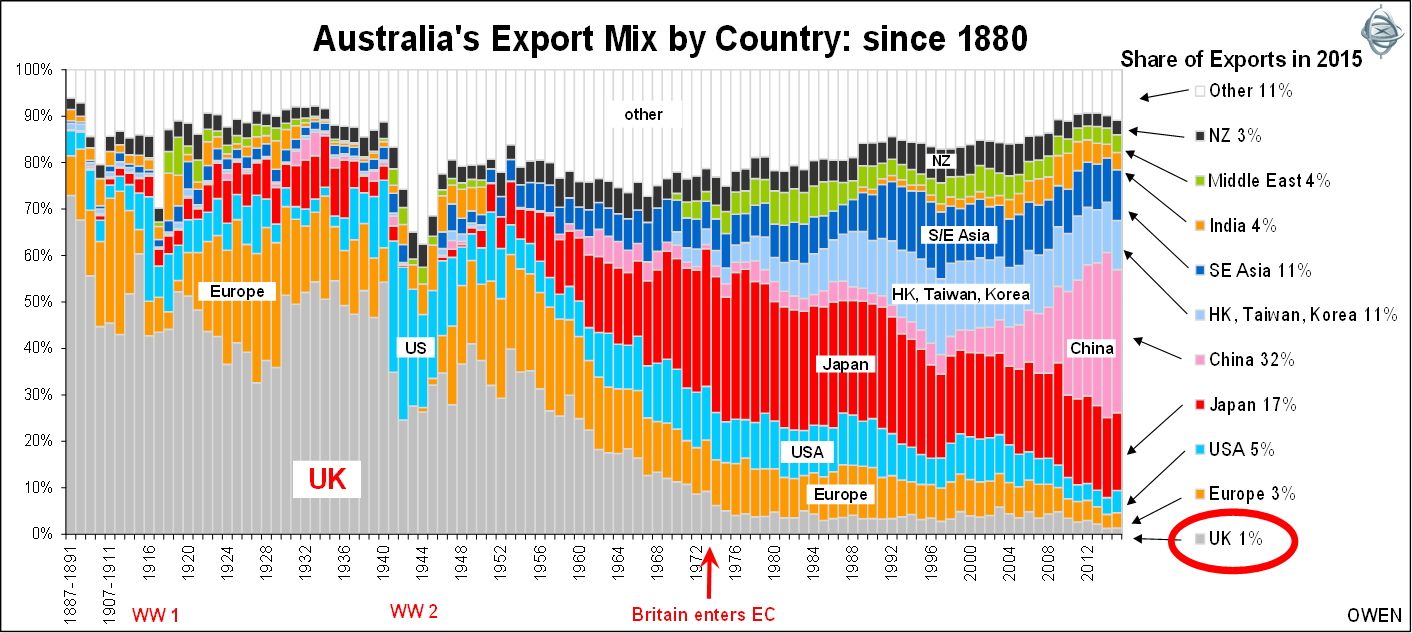
When Britain entered the European Community in 1973, it dismantled its preferential access system for former colonies such as Australia. By that time, however, its impact was relatively minimal given that Britain was buying less than 10% of Australian exports. This was less than the percentage of our exports going to Europe, and less than a third of what Japan was buying. Today, Britain accounts for just 1% of Australia’s export market.

Where to from here?

Britain was a late entrant into the European Community and never adopted the Euro. What was surprising about the Brexit vote, however, was the way in which voters rejected the pleas from both major parties to remain. The final result defied opinion polls taken in the days and even hours before the vote.

This surprise may explain the knee-jerk reaction of financial markets. Globally, ‘risk assets’ like shares, high-yield bonds and commodities (with the exception of gold) were gripped in a wave of panic selling. The money went into ‘safe havens’ such as cash, government bonds and gold.

Markets have since calmed, leaving investors to digest what it all means. The implications for Britain in the long term may well be benign or even positive. An exit would remove a seemingly unnecessary layer of bureaucracy that interferes with every aspect of daily life and costs tax-payers money. In addition Britons will win back some control of immigration, which was the catalyst for the sudden upsurge in dissatisfaction with Europe’s open borders policy. This renewed sense of independence and self-determination may boost spending, investment and employment.

Britain has always been a major source of investment capital for Australia and this may well increase if the Brexit proceeds. The impact of a British exit on trade should be minor in the medium to long term. As Europe accounts for half of British trade, the lower pound will help British exports. The pound fell 10% against the Euro after the vote, and is down 17% since this time last year. But it is still 5% higher than where it was three years ago, so it may need to fall considerably further to provide any real benefit for British exporters.

A more likely impact will be on British companies that operate in Europe under the EU passport system that allows firms to function across the EU without extra licensing in each country. Obtaining new licences should not be a problem for most companies but there will be inevitable disruption in the transition. Some very successful economies operate in Europe outside the EU, like Switzerland and Norway.

Fragmentation may accelerate

While Britain negotiates new treaties, short-term disruption and uncertainty will probably cause an economic slowdown and it may also slow growth rates in Europe, which has been stagnant since the GFC. The Brexit may also accelerate the end of 'Great' Britain. Scottish and Northern Ireland voters overwhelmingly voted to remain in the Union, leading to renewed calls for Scottish independence and the reunification of Ireland.

Another result of the vote is that it may accelerate fragmentation of the EU and Eurozone. It will certainly embolden anti-EU parties across the continent and there are already movements in France (Frexit) and the Netherlands (Nexit). It may also provide more impetus to internal independence movements such as Catalonia in Spain, Flanders in Belgium, Basque in France, and many others. Further political unrest could delay investment spending, leading to slower economic growth and higher unemployment.

More worrying is if the Brexit is seen as a backward step in the globalisation of trade and investment. The European experiment was undoubtedly good for the European recovery after World War 2, but since the GFC we have seen increasing signs of protectionism and currency wars between the big players – the US, China, Japan, and Europe.


Ashley Owen is Chief Investment Officer at independent advisory firm Stanford Brown and The Lunar Group. He is also a Director of Third Link Investment Managers, a fund that supports Australian charities.


  •   7 July 2016
  •      
  •   


Leave a Comment:

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Latest Updates

Retirement

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

2026 is not 1999

The US market looks eerily similar to the dot-com era with soaring AI spending and tech giants dominating returns. But one difference separates today’s boom from the dot-com bubble and it could determine what happens next.

Planning

Taxing time for trusts

Trusts are facing a shake-up, but an overhaul may not be necessary. Families can explore restructuring strategies that preserve succession and the asset protection benefits that have made these structures valuable.

Economy

Why the US economy is stronger than you might think

War, inflation and higher rates were expected to derail America. But has the market got it wrong? Three forces are driving the economy beyond expectations, revealing implications for stock prices and portfolio positioning.

Gold

How much trust is in your portfolio?

Everyone talks about diversifying assets. Far fewer think about diversifying trust. As inflation, debt and market assumptions collide, the question is whether portfolios need greater protection from unexpected outcomes.

Retirement

Retirement in reality - 7 months in

Seven months into retirement, I'm still uncovering surprises. This month was spent reflecting on the slow pace of health change, the myth of neatly scheduled part-time work and the unexpected persistence of retirement guilt.

The new geography of technology leadership

The next chapter of technology may not belong to the companies or business models many expect. As the landscape shifts, some opportunities are emerging in places that remain surprisingly overlooked by global markets.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.