Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 116

Are Chinese investors still on training wheels?

Watching the Chinese investment markets from a distance is a little like watching a young child learning to ride a bike. Rapid progress is being made but at any time it can all come crashing down. Whilst urbanisation briskly increased from 1982 it is only in the last few years that capital restrictions have begun to ease. Restrictions on lending and deposit rates are being loosened, property ownership restrictions are being dropped and access to the share markets has been freed up for retail investors. As a result, non-bank lending has grown exponentially, property has boomed and stock prices have gone up like a skyrocket. There’s a real sense that in the last few years the training wheels have been removed and investors are being left to discover how capital markets work on their own. Whilst markets are going up everyone is happy but are investors even considering it is possible they can go down? Below are two case studies which might provide some insight on how much due diligence Chinese investors are undertaking.

Hanergy Thin Film Power Group

From the perspective of Chinese investors, Hanergy Thin Film was a one way trip to wealth with its Chairman, on paper, briefly reaching the top spot on China’s rich list. The problem is that there is apparently little or no actual business and its ‘revolutionary’ technology is far from proven or profitable. The Bloomberg graph below shows that a year ago shares could be bought for little over one Hong Kong dollar, they peaked at 7.88, then crashed by 47% in a day and have since been suspended from trading.
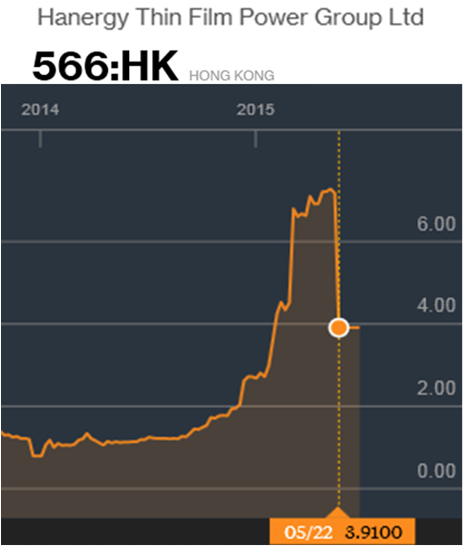
Most shocking is that this is not a two dollar company. It grew to a market capitalisation of over US$40 billion with few questions asked. Barron’s and Bronte Capital did some digging in the months before the share price collapse and concluded something was badly wrong. A simple wander around one site showed few employees and little activity, certainly nothing like what would have been expected by such a supposedly booming company. Information pointing to shorting by the Chairman and margin loans has emerged in the aftermath of the share price collapse, but the opaque related-party transactions and concerns about manipulation of the share price were well known before the collapse. One article asks whether Hanergy is China’s equivalent to Enron. The Hong Kong securities regulator is undertaking an investigation and the shares remain suspended.

Zhuhai Zhongfu Enterprise Co.

Zhuhai Zhongfu has a real business selling plastic bottles to the likes of Coca-Cola and Pepsi in China. Business has been tough in recent years as some of its customers seek to bring their bottle manufacturing in-house. Revenues have been falling, there were big losses in 2012 and 2013 and only a small profit in 2014. Cash levels were declining and were far too small to meet a large portion of debt classified as a current liability. One line of its debt had last traded at a 19.3% yield in June 2014 before the bonds were delisted. A Chinese broker had named it as one of the four riskiest borrowers in China in April 2015. All of this is familiar territory for a company close to default and so there should have been no surprise when on 29 May 2015, Zhuhai Zhongfu couldn’t repay all of the principal due that day.

What is unusual is that the share price rose by 211% in the year before the default on a fairly consistent upward trajectory with a market capitalisation of US$1.4 billion on the day of the default. The credit rating was at A+ until seven days before the default when it was cut to BB. Investors and the Chinese credit rating agency appear to have paid no attention whatsoever to the company financials which pointed to imminent issues.

Conclusion

As an outsider it is very difficult to know whether these companies are representative of listed equities in China. With a median P/E ratio of 75, an explosion in margin loans and a rapid increase in retail investors, suspicions are high that there is a bubble. What can be said with confidence is that in these two cases, Chinese investors didn’t do basic due diligence such as visiting the company and reading the financials. If these two examples are representative of the Chinese share markets then a collapse that rivals the dot com bust or Japan in the 1990’s could be on the cards.


Jonathan Rochford is Portfolio Manager at Narrow Road Capital. This article was prepared for educational purposes and is not a substitute for professional and tailored financial advice. Narrow Road Capital advises on and invests in a wide range of securities, including securities linked to the performance of various companies and financial institutions.


  •   2 July 2015
  • 3
  •      
  •   
3 Comments
Jerome Lander
July 02, 2015

Chinese equities are clearly in a bubble. They are, unsurprisingly, given the backdrop, not the only asset that is.

Bronte Capital, for example, has around 200 "bubblish" securities in their short portfolio which are highly suspect (like Hanergy) and provide a hedge against their long portfolio.

What is surprising is how many investors acknowledge the significant opportunities to be short companies like Hanergy in the current market environment, but how little they look to take advantage of it. Investors could easily do so by investing in long/short funds, rather than long only funds. Looking forward, this would also obviously lessen their chances of being hurt significantly by catastrophic declines in stockmarkets creating permanent capital losses across their entire portfolio, and in many cases better align their portfolios with what they claim their goals to be (good returns without large capital loss).

Graeme
July 02, 2015

No doubt the Chinese are on training wheels, just as the western world was just prior to the GFC. A common feature of bubbles has always been fanciful market activity that the main participants choose to ignore.

I would be very careful getting involved in shorting in such markets, remembering that a stock can only fall 100% whereas it can rise thousands of percent. And of course there is also the chance that that if the stock price is falling as hoped there is the risk that another company will launch a takeover or in the Chinese case receive government support.

Jerome Lander
July 03, 2015

Graeme, yes shorting Chinese equities is problematic and needs to be done in a very risk-constrained and tightly risk managed way, and in the context of a broader portfolio of shorts, and longs. It is not something anyone should do, but something that is best outsourced to professional investment managers who are capable shorters.

The higher level problem, however, is that the balance of portfolios are very heavily weighted to long only portfolios after what has been a very long bull market, with identifiable and increasing catalysts and risks. Good long-short and more active portfolios in general are better aligned - and better placed - to meet most investors' outcomes and objectives going forward, and hence deserve to be a much bigger part of investment portfolios than they currently are.

For example, many super funds and institutional investors - who are far too fee driven currently - simply are not adequately diversifying their long only index like funds in their portfolios to best construct outcome orientated portfolios. Doing so would help better align their portfolios with their stated objectives, and help prevent mums and dads being as hurt in the next inevitable market correction. Interestingly enough, the same individuals who run these funds will place their own money into long short funds, which should tell you something!


Leave a Comment:

RELATED ARTICLES

Feeling lucky? Another stock market spike in China

banner

Most viewed in recent weeks

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

Testamentary trusts have secured the CGT exemption

Treasury’s latest CGT reform draft delivers a win for testamentary trusts and deceased estates, exempting estate-derived gains from the 30% floor. However, questions on death and divorce rollovers remain unresolved.

Meg on SMSFs: What do we think about reversionary pensions these days?

Reversionary pensions have long been a staple of SMSF estate planning, but are they still the best option? Meg Heffron revisits a once-clear favourite and asks whether changing super rules have shifted the balance.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

How does the 4% rule stack up?

The 4% rule has long been retirement's gold standard. But after a difficult period for investors, fresh analysis suggests a more conservative approach may significantly improve the chances of making savings last.

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

Latest Updates

Planning

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

Superannuation

There's a reason why your super is locked up until your 60s

For decades, it seemed settled. Then one controversial idea reignited a debate that could reshape the financial future of millions. The real question isn’t who’s right or wrong, but whether a long-held assumption deserves another look.

Property

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Retirement

Under-retiring: The greatest retirement risk in a generation

Two retirees. Similar savings. Completely different lives. New research from Challenger reveals why some Australians confidently spend in retirement while others hold back and the overlooked factor shaping retirement decisions.

Five risks to watch in markets

Things you may often hear are: a recession is around the corner, markets are overpriced, the AI sector is about to flop at any moment. It’s like the never-ending laundry pile that sits in my house, it never really disappears.

Investment strategies

Do you qualify as ‘rich’?

What does it mean to be 'rich'? For something so universally desired, it is surprisingly difficult to define. That ambiguity creates a challenge for investors and raises a bigger question about what financial success really looks like.

Investment strategies

If you’re worried about your bond portfolio, you’re missing the point

Most investors think they know what bonds are for. But when markets turn volatile, a surprising misunderstanding can lead to costly decisions. Here’s the overlooked lesson that could change how you view your portfolio.

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.