Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 157

Commodities: has the trend changed?

On the 22 March 2016, Mr Richard Elman, Founder and Chairman of the Noble Group Limited was quoted on Bloomberg as saying:

”We all know that commodities are cyclical, but predicting when that turning point comes is only possible with hindsight, especially with such excessive moves as are currently occurring. Those who come hoping for some kernel of wisdom leave disappointed when I tell them that I don’t know how all the different factors will play out - nor does anyone else.”

It is unusual for a high-profile executive to be so frank and explain how things really are. For someone like Elman who has been involved in building a large commodities business over five decades to admit that predicting turning points in commodity prices is impossible has consequences for all other market participants. If turning points are impossible for him to predict, then it follows that predicting turning points in resource companies is as difficult, if not more difficult. As Ed Seykota famously stated in an interview:

“Commodity trading is the purest form of trading in the world and resources companies are simply a leveraged version of this.”

Nobody rings a bell

Of course, resource journalists, researchers, newsletter writers and research analysts cannot admit this ‘simple truth’ otherwise their very reason for existing would be cast into doubt. Mr Elman has the luxury of having built up a large business and five decades of experience and is a major owner of a business that has experienced significant share price movement over long periods of time.

It follows from this logic that ‘no one rings the bell at the top of a resources cycle’ because it is impossible to predict. Similarly, ‘no one rings the bell at the bottom of the resources cycle’ because it is impossible to predict. It didn’t happen at the top of the last resources boom and it won’t happen at the bottom of the current resources downward trend.

What is extremely interesting, however, it that commodities and consequently resource companies do experience significant periods of trending. This brings us to how an investor actually makes money in resource companies. The short answer is by following the trend once it has been established and exiting the trend once it has ended.

Diagram 1: ASX200 Resources Index over last decade.
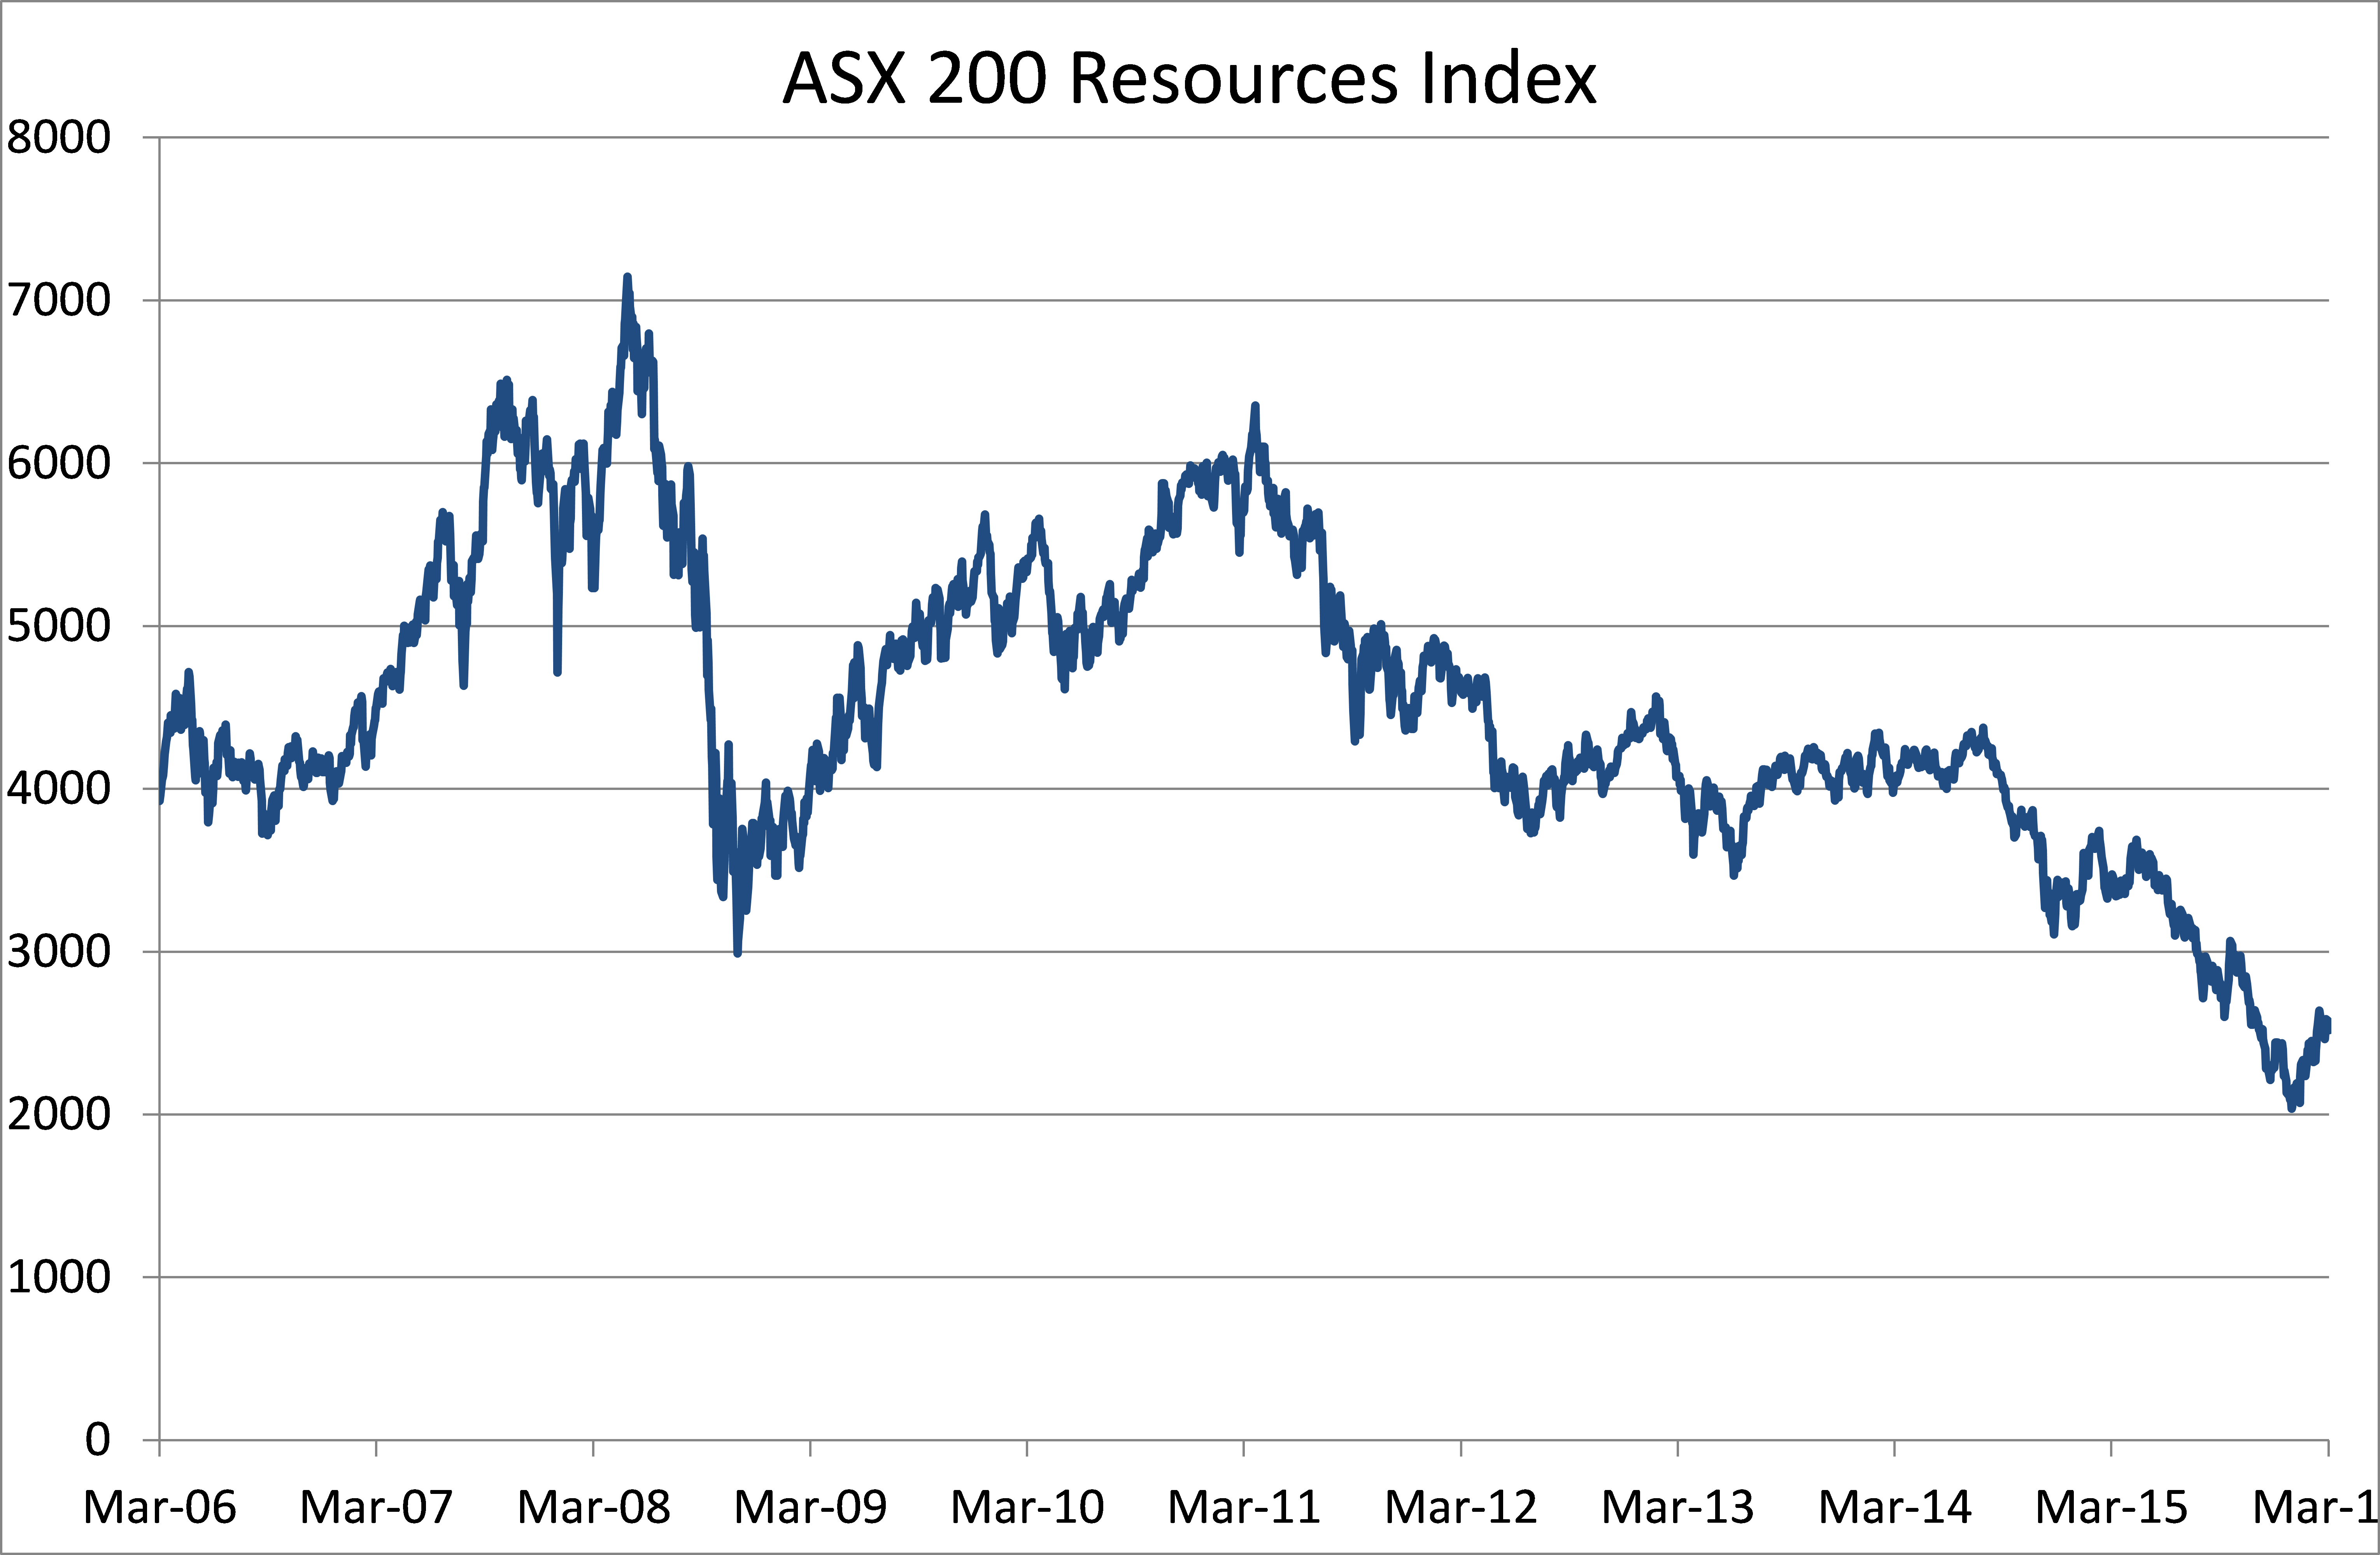
Diagram 1 is a ten-year chart of the S&P/ASX 200 Resources Index. We can see a period up to 2008 when the index was trending up strongly, then a severe sell off during the GFC and a strong recovery and trend until 2011. Since 2011 the resource index has been falling for five years. Only recently we have seen an ‘uptick’ in the resources index and many of the stocks that underlie this index. Clearly the longer-term trend is down but we may be seeing the first early signs of a recovering resources sector. However, as Mr Elman points out, this is impossible to tell, but will be easy in hindsight.

Closing shorts and entering longs

How do we deal with this set of circumstances at Cadence? Having been short a number of commodities over the past three to five years we find ourselves scaling out of these short positions a bit at a time. Diagram 2 illustrates our process of scaling out of (buying back) short positions.

Diagram 2: Exiting shorts
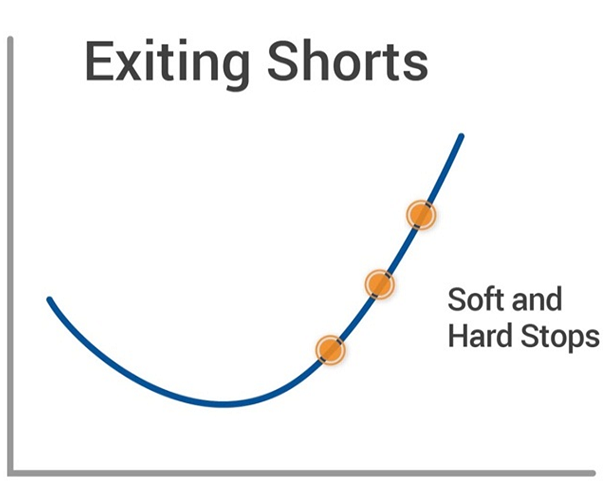
As we exit these short positions we may find that many resources stocks have become fundamentally cheap and are starting to trend up. This process then allows us to enter small long positions and potentially scale into a longer term recovering trend (Diagram 3 below).

Diagram 3: Entering longs
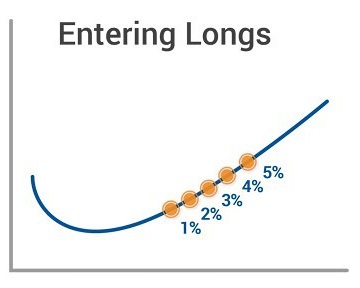
Should this prove not to be the case then we would simply exit these small positions with small losses. In this way we adopt a risk-adjusted approach to determine whether the resource decline has in fact ended and the market is entering a new trend. We believe this is the only way of establishing a position.

It is very difficult to predict turning points in any stocks but particularly difficult in resources stocks. However, once a trend has been established, trends tend to last for considerable periods of time, particularly in cyclical stocks and industries.

As we write this article we know that recent price movements have at a minimum tested long-term resource and energy price trends and may be indicating a longer term change in trend. Only time will tell, but our process for dealing with these trends is well-defined. We are not professing to ‘ring the bell at the bottom’ but the bell may currently be ringing.


Karl Siegling is the Managing Director of Cadence Capital Limited (ASX: CDM). CDM is a Listed Investment Company currently celebrating its 10-year anniversary. This article is for general education and does not consider the individual circumstances of any investor.


  •   26 May 2016
  •      
  •   


Leave a Comment:

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Higher yields are creating opportunities in global bonds

Bond markets are adjusting to a new reality, but not in the ways investors expect. With markets repricing and capital competing for attention, investors may need to rethink where resilience and opportunity lie. 

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Latest Updates

Superannuation

Superannuation’s structural failings

Politicians are fighting over access to super, but they may be arguing about the wrong thing. The system’s three fundamental flaws have been hiding in plain sight for decades, costing Australians far more than they realise.

Planning

The great wealth transfer myth

Why do some families preserve wealth for generations while others struggle to? As the great wealth transfer unfolds, the determining factor is often not the structure of the estate, but the preparation of those who will inherit it.

Investment strategies

What comes after bank hybrids?

For years, bank hybrids have been a cornerstone of portfolio income. With tens of billions of dollars now disappearing from the market, investors face a critical question: what comes next, and are the obvious replacements enough?

Investment insights from the US

What happens when knowledge becomes a commodity? The latest themes emerging from the US tech sector suggest AI could reshape company moats, disrupt incumbents and create winners and losers in unexpected places.

Investing

Can Berkshire thrive without Buffett?

Warren Buffett's departure marks the end of an era. But the more important question for investors is whether Berkshire's culture, discipline and capital allocation framework can survive without the man who built them.

Retirement

The Bengen 4% Rule: Lost in translation

For years, retirees have been told to focus on withdrawal rates. But the real question is far simpler: how many dollars can you safely spend? The answer may be very different from what conventional retirement wisdom suggests.

Interest rates

Super low interest rates came with side effects

For more than a decade, investors lived through an era of near-zero interest rates. With bond yields now surging, it's worth asking whether cheap money solved economic problems, or introduced a much larger set of risks.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.