Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 552

Credit trumps residential property for headache-free income

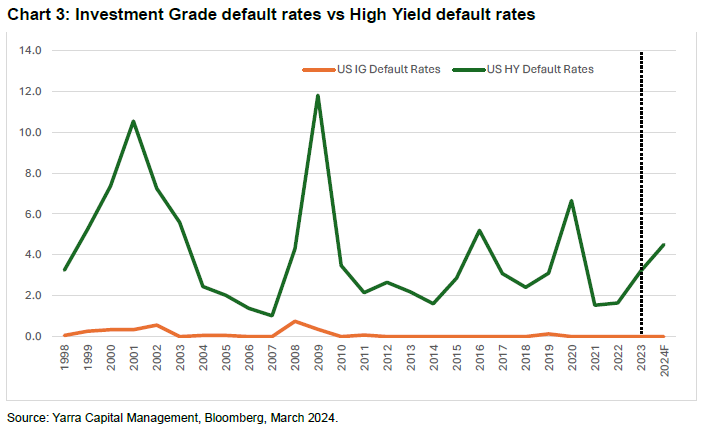
Investment grade (IG) portfolios can offer returns of 7-8% and, importantly, the likelihood of any significant default cycle appears small.

Australian bond and fixed-income managed funds saw strong net fund inflows over 2023 and that trend has continued into the early part of 2024. That does not happen very often but when it does, it can produce equity like returns from fixed interest assets and with a much lower risk of capital loss. I believe investors are starting to understand that, and that's the real attraction of investment grade (IG) rated portfolios.

One interesting trend we have increasingly observed is that IG deals coming to market are offering better returns than so called ‘safe haven’ asset classes, in particular the Australian residential property market (refer Chart 1).
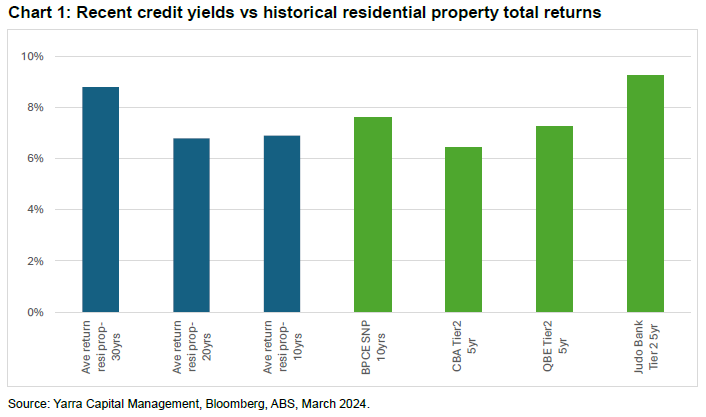
The challenge is delivering compelling risk-adjusted returns. Here we take the view that global governments will focus on maintaining stability in their economies, resulting in higher-for-longer inflation and interest rates. Under this scenario, the cost of debt would remain higher for an extended period - an excellent backdrop for credit investors. The return prospects look increasingly attractive: investors can lock in higher yields than cash and with limited interest rate or spread risk. While recent IG credit returns compare favourably to the average total returns available from equities, comparing with residential investment property paints an especially stark picture.

Credit opportunities

In terms of our investments across the Australian multi-asset credit universe, key positions have been in bank-issued Tier 2 hybrid debt (T2s) and residential mortgage-backed securities (RMBS). The market is increasingly comfortable that we’re not going to have a house price crash and is factoring in an environment where central banks stop hiking and eventually start easing rates (from as early as August in Australia). We’re seeing credit spreads performing very strongly because of the attractiveness of the outright yields and the comfort investors have with those IG corporates and issuers. It’s a thematic that is likely to continue.

Compared specifically to residential property, we believe IG credit offers an appealing and hassle-free alternative for stable and attractive income, without the headaches associated with owning investment property. Yields of 6-7% across T2s and RMBS compare to residential property rental yields of just 2% (refer Chart 2).
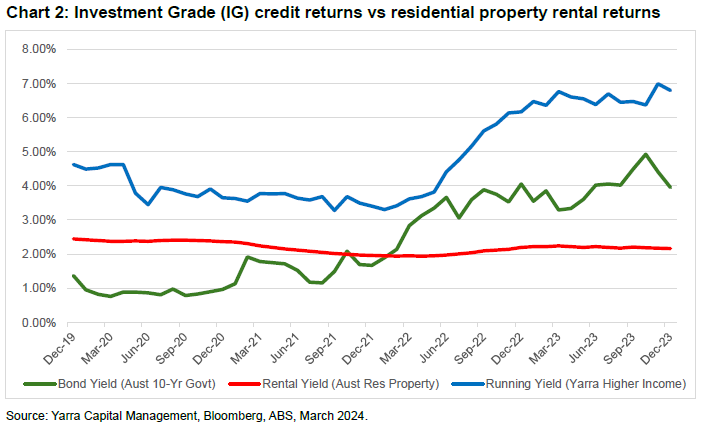
While we’re not suggesting holders of Australian investment property should all rush for the exits, it is worth contemplating the go-forward return profile for what is one of Australia’s long favoured asset classes.

With such a significant gap in return profiles, investment property owners would need to see significant capital growth to make up the difference. And with a stable outlook for house prices, it’s difficult to see that happening. Meanwhile, taxes are rising for Australian property investors and there is clearly some uncertainty around the future of negative gearing.

The outlook for investment grade credit

Looking forward, we think bank issued hybrid capital, particularly T2s, are still attractively priced and that they will continue to provide a source of strong outperformance. RMBS is still a robust sector, as we continue to see households prioritising their mortgage repayments over discretionary spending. With house prices having essentially returned to their previous peaks, and borrowing capacity determined by income capacity, it is difficult to imagine a scenario where the next leg up for house prices comes from. Finally, combined with uncertainty around the government’s future tinkering to both negative gearing and capital gains tax, potential for still higher land taxes in some States, and the increasing rights of tenants, it’s understandable why many property investors are more likely to be thinking of selling up rather than buying.

It’s clear that investors see IG credit as a defensive play and as a security that should perform well in a recession. History has shown that rate hiking cycles by central banks often lead to a recession and so it must remain a consideration. However, even in a recessionary environment with mild negative growth, IG credit offers a compelling alternative to cash. There are parts of the credit market that are more vulnerable in the event of recession, but IG credit ratings underscore companies that can more easily service debt and, therefore, are better able to weather the negative impact of a recession on profitability. 
 

Phil Strano is a Senior Portfolio Manager at Yarra Capital Management. This article contains general financial information only. It has been prepared without taking into account your personal objectives, financial situation or particular needs.


  •   20 March 2024
  •      
  •   


Leave a Comment:

RELATED ARTICLES

Is the best value for Australian credit not in Australia?

Can Australian credit continue to perform?

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Latest Updates

Retirement

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

2026 is not 1999

The US market looks eerily similar to the dot-com era with soaring AI spending and tech giants dominating returns. But one difference separates today’s boom from the dot-com bubble and it could determine what happens next.

Planning

Taxing time for trusts

Trusts are facing a shake-up, but an overhaul may not be necessary. Families can explore restructuring strategies that preserve succession and the asset protection benefits that have made these structures valuable.

Economy

Why the US economy is stronger than you might think

War, inflation and higher rates were expected to derail America. But has the market got it wrong? Three forces are driving the economy beyond expectations, revealing implications for stock prices and portfolio positioning.

Gold

How much trust is in your portfolio?

Everyone talks about diversifying assets. Far fewer think about diversifying trust. As inflation, debt and market assumptions collide, the question is whether portfolios need greater protection from unexpected outcomes.

Retirement

Retirement in reality - 7 months in

Seven months into retirement, I'm still uncovering surprises. This month was spent reflecting on the slow pace of health change, the myth of neatly scheduled part-time work and the unexpected persistence of retirement guilt.

The new geography of technology leadership

The next chapter of technology may not belong to the companies or business models many expect. As the landscape shifts, some opportunities are emerging in places that remain surprisingly overlooked by global markets.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.