Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 478

The energy crisis is likely to last years

Europe is restarting mothballed coal-based power plants because the benchmark electricity price has exceeded 1,000% above its average of the past decade (where prices are set by the marginal cost of the last unit – essentially, the most expensive unit – of energy purchased to balance demand). Electricity prices are spiralling because the cost of natural gas, the marginal fuel in most European electricity markets, has soared 1,300% above its decade average. The shock would be like oil nearing US$550 a barrel.

Global price of natural gas, EU
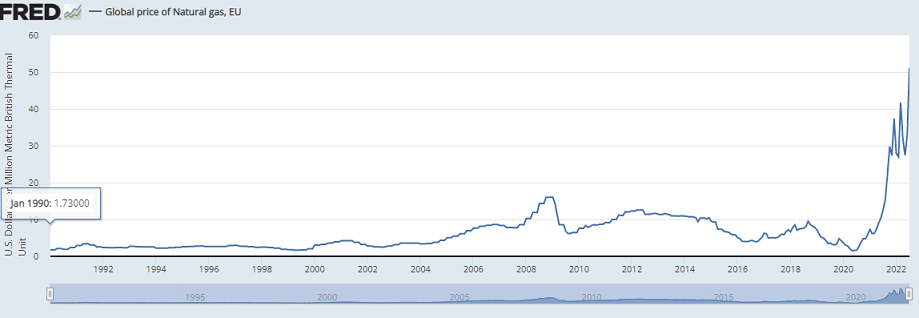
Sources: IMF and Federal Reserve of St Louis. Found at: fred.stlouisfed.org/series/PNGASEUUSDM

Widespread controls

The EU, in response, is imposing wartime-like price controls, rationing and a windfall tax on energy companies. In the UK, the prospect of household energy bills jumping by 9% of GDP has prompted London to announce emergency measures worth double the cost of the pandemic furlough scheme, and to reallow shale-gas fracking.

Norway, where hydropower generates 90% of local needs, may curb the export of electricity, raising concerns cross-border flows could collapse across Europe. French nuclear power output is diving due to maintenance and repairs, with Électricité de France only operating 26 of the country’s 57 reactors. President Emmanuel Macron warns of the “end of abundance”. Germany is worried that rage over energy prices driving inflation to near-50-year highs could turn violent. Kosovo is facing two-hour blackouts every six hours, the first European country to display this feature of a failed state.

In China, daily hydro generation from the Three Gorges dam on the Yangtze River has dived 51%. Factories have suspended operations and cities are dimming lights. Japan is overcoming its Fukushima fears and returning to nuclear power. Southeast Asia is using coal to replace the liquified natural gas diverted to Europe. South Asia is suffering blackouts because energy is unaffordable. US natural gas prices in August breached US$10 per million BTU, a 400% increase on the recent years, due to demand from Europe.

The world faces its biggest energy crisis since the 1970s when soaring oil prices helped create the stagflation for which the decade is renowned. Today’s energy blow could be crueller because the energy industry, having overcome the pandemic disruptions that boosted prices for hydrocarbons, is beset by three challenges that are set to persist, if not worsen.

Three major challenges 

The first challenge is the unfavourable state of global politics. Europe’s torment is due to the significant cuts to the supply of Russian oil and natural gas that accounted for 40% of its energy needs. Oil and gas prices are likely to stay elevated in the near term because the world’s energy system cannot quickly replace Russia’s lost hydrocarbons, which equate to about 10% of global energy production.

The Middle East is another concern. The return of Iranian oil to replace Russia’s missing barrels depends on restoring the agreement on Iran’s nuclear capabilities between Iran and the EU, Germany and the five permanent members of the UN Security Council, one of which is Iran’s ally, Russia. Moscow could easily delay any new agreement or ensure that any restored pact is short-lived.

The second energy challenge relates to climate change. Droughts and heatwaves in China, Europe and North America are hampering hydropower electricity generation while boosting demand beyond capacity. France’s nuclear industry has cut production because receding rivers make it harder to cool reactors. The other angle to climate change is that renewable energy generation has not reached a level where it can compensate for lost fossil fuels.

The third challenge for energy markets is overcoming policymaker mistakes:

  • The biggest error is that Europe, notably Germany, became dependent on Russian energy, especially natural gas that is not as easy as coal or oil to replace.
  • A second mistake is France has failed to keep operational the country’s nuclear reactors.
  • A third error, many would argue, is the world’s turn away from nuclear energy after the Fukushima disaster in 2011.
  • A fourth blunder was not investing enough in renewables. Much blame will flow if the rising prices that are creating huge paper losses for utilities on Europe’s energy derivatives markets spark financial instability.

Reduction on living standards

Today’s energy crisis is still unfolding. In time, the promise of profit will calm the crisis with clean solutions that snap Western dependence on despots. In the meantime, however, the energy crisis is likely to cut global living standards, boost inflation, trigger a recession or worse in Europe, hound those in power, widen inequality within and between countries, trigger social unrest, spark industrial conflict and impede the fight against climate change. The damage inflicted just in Europe will likely make the 2020s energy crisis worse than that of the 1970s.

To be sure, favourable developments in relation to the Ukraine war could calm things and droughts will break and heatwaves pass. Maybe a sunny, warm and windy winter in Europe and energy substitution and conservation will ease power costs. Countries with gas and other energy reserves stand to gain. The recent fall in oil prices relieves inflationary pressures. But spot oil prices have declined on China’s pandemic lockdowns and concerns about a European recession.

The energy crisis largely created by Russia’s missing fossil fuels might best be viewed as shorthand for a series of crises around climate change, government finances, inequality, inflation, politics and social cohesion. Policymakers have much to solve before they can close for good those coal plants being refired to overcome today’s energy emergency.


Michael Collins is an Investment Specialist at Magellan Asset Management, a sponsor of Firstlinks. This article is for general information purposes only, not investment advice. 

For more articles and papers from Magellan, please click here.


  •   5 October 2022
  • 8
  •      
  •   
8 Comments
Rob
October 05, 2022

With respect, it's not about history, the future is more important. All of a sudden you have a powerful alignment of the need for secure supply AND the need to take carbon out. Guess who wins? Australia! Almost every mineral necessary for that transition which will take decades, is in Oz - Lithium, Graphite, Nickel, Cobalt, Copper, Rare Earths and the list goes on... To get from 2022 to 2032 the transition fuel of choice is LNG. Can you quickly increase the global supply and shipment of LNG? No you can't. Guess who wins? Australia!! Lucky country? Yep

Steve
October 05, 2022

While Biden's policies have made the price of fuel double over the past year, it's interesting that Ausbil commented recently that the US Henry Hub natural gas price is quite low, compared to the EU, where it is skyrocketing. The USA seems to be doing whatever they can to sell more gas. lol https://ycharts.com/indicators/henry_hub_natural_gas_spot_price

DC
October 05, 2022

No mention that European and other western countries, have significantly curtailed or prohibited oil and gas exploration in their own countries, and that banks, the IMF and other financiers are increasingly limiting finance fossil fuel projects.

Add to that the closing of perfectly good nuclear and coal plants and transitioning to renewables that are a long way from being a suitable replacement and able to provide sufficient, sustainable and reliable "base load" power.

The net effect, having to rely on less than reputable countries to supply a large percentage of gas and oil that under normal circumstances could have been produced locally or by other stable countries until the time when other suitable lower carbon alternatives are technologically adequate replacements.

As to more funding for renewables to alleviate the problem, many countries have invested hundreds of billions, if not trillions, with no meaningful reduction in fossil fuel use or reliance and significant increases in electricity costs. Just look at Germany, California and Australia.

The current crisis, is not something largely created by Russia, but should be seen for what it is - a huge "self-inflicted own goal" by developed economies. Russia and the gas crisis is arguably just a symptom of the failed policies of the west - a foreseeable one at that.

Sunshine
October 05, 2022

Absolutely spot-on. Well said!

Peter
October 05, 2022

The root cause of the energy crisis is the world commitment to renewable energy in a timeframe impossible to achieve without the adverse impacts of energy shortages listed in the article.
That is why so much natural gas is required to supply energy demand reliably. The logical response to insufficient gas now and uncertain availability in future is to remove bans and moratoriums on gas exploration and production and provide sovereign long term take or pay contracts for new supply. With certainty, the price will come down.
Climate action must wait; to do otherwise will inflict far more damage on us all that a bit more global warming.

michael
October 06, 2022

"Climate action must wait; to do otherwise will inflict far more damage on us all that a bit more global warming."

You don't actually know this. Nobody does.
Nobody knows how much damage a gas shortage will do. Nobody knows what a little more warmth will do.
I will add that Europeans have lived without gas for millennia, & the globe has been warming for millennia.

Tony
October 05, 2022

"Europe’s torment is due to the significant cuts to the supply of Russian oil and natural gas that accounted for 40% of its energy needs."

It's a cop out to blame Russia for Europe's energy woes. The question is why was Europe so dependent on Russian oil and gas in the first place? And the answer might be because of the failed transition to renewable energy. Here's a tip Europe. It's not very prudent to shut down reliable energy sources without having adequate replacement ready to go. And if we want to see what awaits us given the current trajectory we are on, then look no further than Europe, because our future is unfolding in real time.

Pete
October 08, 2022

Despite the unfolding catastrophe in Europe, some still seem to view energy transition akin to a woman giving birth to a baby after one month instead of 9.

To offer up "spend more on renewables" as the solution is a fantasy and continuing to pretend so, as many Western governments, including Australia's newly elected optimists, in not only naive it is incredibly dangerous.


Leave a Comment:

RELATED ARTICLES

The surprising beneficiaries of the AI boom

The ticking clock on oil reserves

Europe: A new growth trajectory powered by reform and investment

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Higher yields are creating opportunities in global bonds

Bond markets are adjusting to a new reality, but not in the ways investors expect. With markets repricing and capital competing for attention, investors may need to rethink where resilience and opportunity lie. 

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Latest Updates

Superannuation

Superannuation’s structural failings

Politicians are fighting over access to super, but they may be arguing about the wrong thing. The system’s three fundamental flaws have been hiding in plain sight for decades, costing Australians far more than they realise.

Planning

The great wealth transfer myth

Why do some families preserve wealth for generations while others struggle to? As the great wealth transfer unfolds, the determining factor is often not the structure of the estate, but the preparation of those who will inherit it.

Investment strategies

What comes after bank hybrids?

For years, bank hybrids have been a cornerstone of portfolio income. With tens of billions of dollars now disappearing from the market, investors face a critical question: what comes next, and are the obvious replacements enough?

Investment insights from the US

What happens when knowledge becomes a commodity? The latest themes emerging from the US tech sector suggest AI could reshape company moats, disrupt incumbents and create winners and losers in unexpected places.

Investing

Can Berkshire thrive without Buffett?

Warren Buffett's departure marks the end of an era. But the more important question for investors is whether Berkshire's culture, discipline and capital allocation framework can survive without the man who built them.

Retirement

The Bengen 4% Rule: Lost in translation

For years, retirees have been told to focus on withdrawal rates. But the real question is far simpler: how many dollars can you safely spend? The answer may be very different from what conventional retirement wisdom suggests.

Interest rates

Super low interest rates came with side effects

For more than a decade, investors lived through an era of near-zero interest rates. With bond yields now surging, it's worth asking whether cheap money solved economic problems, or introduced a much larger set of risks.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.