One of the conceits of Gary Shteyngart’s Super Sad Love Story is a future in which everybody’s ability to continue accessing consumer credit is determined, in real time, by credit poles that announce to the world the credit ratings of those who pass by. The book, which was written back in 2010, seemed to anticipate a world in which, companies know more about you than you do about yourself.
Anticipating borrower credentials
Consumer lending seems ripe for these forms of corporate intelligence to anticipate the behaviour of potential or current borrowers. Advances in artificial intelligence have been used by banks on credit card lending for decades and seem to be paying off. The average annual U.S. net credit card loss rate for prime borrowers has been at its lowest recorded (below 3%) for the past five years, significantly below the 30-year 5% average. As the average interest rate on US credit cards has remained at over 13%, the average bank seems to be making a lot of money on this type of lending, as long as they can control its risk.
The original promise of peer-to-peer lending was precisely this: why should the banks benefit from this enormous spread between lending rates and funding rates? A potential investor in marketplace lending (i.e. a lender) should benefit instead. And the rates paid to marketplace lenders are higher than they would otherwise receive if lending to a bank itself. However, just as with securitisation lending, investors in marketplace lending own the risk, and need to ensure that it is carefully managed. The consumer credit arena was littered over the decades with those who flew too close to the sun, particularly in new forms of consumer credit [1].
Comparisons with other types of lending
On its surface, marketplace lending seems promising for a potential investor. A pool of consumer or commercial loans sourced through an intermediary provides the benefit of borrower diversification, just as a securitisation loan pool does, and at a higher net estimated spread than other types of lending.
Another perceived advantage is that pools of loans have the benefit of apparent familiarity. Unlike high yield bonds or loans or even asset-backed securities (ABS), these auto, commercial and consumer loans are easily understandable, not highly structured as ABS are, and locally (according to their originators) have experienced only nominal losses of less than 0.25% as a percentage of the pool.
The table below shows an estimate of the credit spread available from marketplace lending compared with other types of lending. Note that while most data is based on historical performance of debt type, the marketplace lending estimates are projected based on the experience of comparable types of consumer lending.
Estimated loss-adjusted credit spread by type of asset
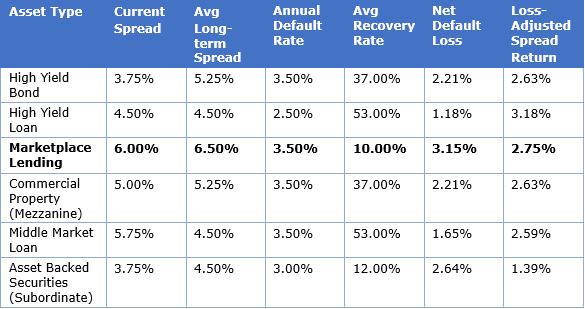
Source: Moody’s, Credit Suisse. Loss-adjusted spread is estimated based on a four-year average loan life. Recoveries are assumed to occur simultaneously with defaults for simplicity (in reality there would be a lag). Long term spread for marketplace loans is interpolated to be historical average spread for BB unsecured consumer securitised debt, with lower assumed default rate (actual historical is 5-10%) and similar recovery rate.
Difficulties knowing default rates in advance
But there are also reasons for caution with respect to marketplace lending. In general, debt investing and equity investing are different. With less upside available in debt than equity, it ordinarily pays more to be an early investor in equity than in a new type of debt. The reason we have done so well (in some respects) as a species is because of our enthusiasm for what is new. But successful debt investors can perhaps be considered a particularly dour sub-species. Australia has gone through a period of around 30 years of economic expansion, has never had a full subprime lending cycle, and so new investors in consumer debt should be careful. Most marketplace loan packages also do not have the same level of equity protection as their predecessor securitisations, although this is beginning to change.
Potential investors should therefore be conservative with respect to the eventual losses expected on this type of lending. An annual loss rate of 3.5% when realised losses are less than 0.50% seems high, but subprime consumer lending annual losses have historically been in the high single digits virtually universally, and higher if a pool performs poorly. If this 3.5% loss rate doubles to 7%, for example, the annualised total return over a four-year period becomes -1.75%. In prior economic cycles, securitisation loan originators tried to limit investor losses by freezing credit, and in revolving pools by allowing payments to go to debt investors first. Still, some of the lowest-ranked ABS debt had net credit losses, which is why subordinate ABS have some of the worst loss-adjusted spreads over the past two decades.
The other way that loan originators have tried to limit losses is by setting interest rates high enough to compensate for the risk. Commercial marketplace lending rates are 15% and more. Some consumer rates may be lower than this, but higher than traditional credit card rates. A high annual interest rate should be enough to compensate a loan originator for residual credit risk. Part of this charge is also to cover loan servicing costs, which for subprime lending have traditionally been 4-6% annually. But without additional credit protection, potential investors might also ask is why the rates they receive are significantly lower than this, since the disintermediation of banks and their fees was meant to be a main advantage of this type of lending.
The making and pricing of loans
A key question for marketplace lenders should be how they use their intelligence on potential borrowers to make and price loans. If marketplace lenders truly have developed valuable ways of assessing customer behavioural risk through intelligence, they should be able to describe it in detail to potential investors without giving away their business advantage.
The world of credit poles for consumer credit assessment, just as with other forms of machine-learnt intelligence, is probably not as far away as we think. But along the way, there will almost certainly be some accidents, just as there have been over the past two decades. An investor evaluating marketplace lending should take care that he or she is aware of the risks for the potential return they can receive.
[1] NextCard, an internet-based credit card company that issued securitisation debt and failed in the early 2000s, is probably the easiest example to pick out. The technology was far ahead of the credit intelligence actually needed to make the business work. As investors, we try to learn from our mistakes.
John O’Brien is a Principal Adviser at Whitehelm Capital, an affiliate of Fidante Partners. The views expressed in this article are those of the author. This article is for general information purposes only and does not consider the circumstances of any investor.
Fidante is a sponsor of Cuffelinks. For more articles and papers from Fidante, please click here.