Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 432

Are older Australians re-assessing the job market?

Before Covid-19, a major reason that Aussies weren’t employed or looking for jobs was because they had retired. That is, they were out of the job market. In fact, in April 2018, 38.7% of people said that they were “Permanently not intending to work (aged 65 and over)”, up from 33% just four years prior (September 2014). Then there was a reassessment. The proportion of those not in the workforce because they were retired fell from 38.7% to a 3-year low of 35.3% in July 2019.

Record numbers, but are they accurate?

And in the period since, due to Covid, it is not possible to determine firmly whether the trend has changed because more people exited the job market over the lockdown period. They weren’t employed as such – they didn’t work for one hour or more in the past week - but neither were they looking for work because they were likely to return to their employer after the lockdown.
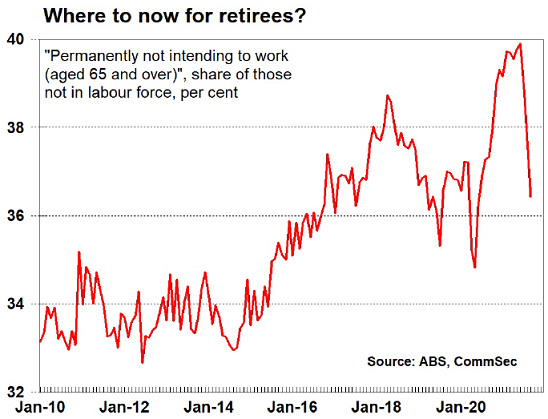
The lockdowns have effectively scrambled the data. The proportion of those not in the workforce because they were retired hit a record 39.9% of the total in June 2021 and this has since fallen to a low of 36.4% per cent in September 2021.

So let's check two other data points at different ages.

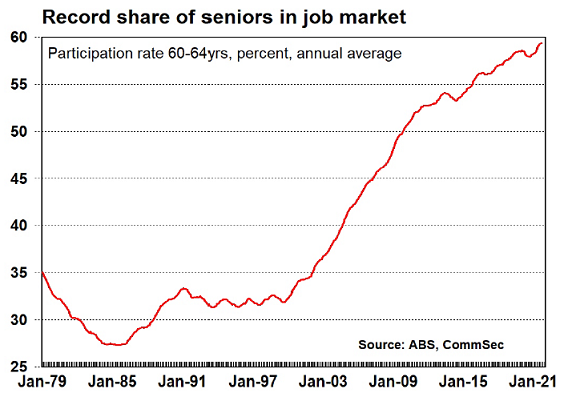
First, a record proportion of people aged 60 to 64 years are in work.
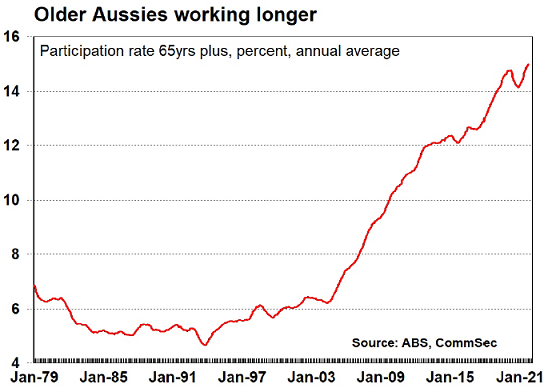
Second, the 65 years plus age group participation rate shows more Aussies are working longer.
Impact on overall job market

Working out why people are not in the job market will be important in coming months. If more people are electing to retire then there are fewer potential workers to fill positions. That may mean the job market tightens more than generally expected, putting upward pressure on wages and prices. And that is especially the case if foreign borders stay closed.

In other words, The Great Retirement could lead to a tighter job market. Older Aussies may see greater health risks in being in the job market in the Covid era. And still others may elect to live large given the experience of the past 18 months.

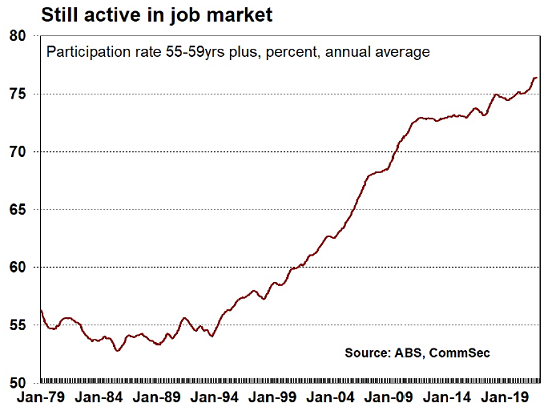
At this stage data still shows that older Aussies are active in the job market with record participation levels. However peak levels may not be far away.
In other countries, notably the US, there are similar concerns about the future state of job markets with more businesses saying they can’t find the workers to fill positions.

The great reopening has led to supply-chain breakdowns and higher prices for goods. The great reopening may lead to similar worker-job breakdowns, with labour shortages driving up wages. With thousands of Aussies reaching retirement age every week, their decisions about work could have broader, long-term inflationary implications.


Craig James is Chief Economist at Commonwealth Securities Limited (CommSec). This article provides general market-related commentary only and has been prepared without taking into account your objectives, financial situation or needs.


  •   3 November 2021
  • 7
  •      
  •   
7 Comments
Robin
November 03, 2021

Lockdowns and WFH have allowed many to experience the greener grass on the other side. I'm not surprised we're seeing 'The Great Retirement' playing out.

C
November 06, 2021

For every person retiring there is a young person leaving school or university in need of a job. As for WFH, people should be careful what they wish for. If their job can be done remotely from home, then maybe the company can save a lot of money using people in the Phillipines as has already happened in some IT sectors.

Geoff
November 07, 2021

A lot of companies started in-sourcing again when countries providing off-shore services just shut up shop with no notice during the pandemic (usually mandated by government, not the choice of the companies). A lot of businesses have learnt from that. And IT and processing sort of work, but you need capable people on shore to control them - I doubt there will be a significant outflux of jobs as a result of the pandemic.

Graham W
November 03, 2021

Centrelink now allows Age pensioners to each work and earn $320 per fortnight without affecting the Income Test.
This means an extra $8,320 pa, double that for a couple. Certainly a no-brainer for those with limited financial assets.
And it accumulated so that you can earn your $8,000 or so in one burst and have the rest of the year off.

Jerome Lander
November 06, 2021

Evidence of change means we need to think about how we build portfolios differently for the future, particularly for those who have accumulated substantial wealth and want to protect it from a changing economic environment. Inflation is certainly one of the big concerns that most aren't ready for.

C
November 06, 2021

People better be careful what they wish for. If their job can be done remotely from home, then maybe the company can save a lot of money using people in the Phillipines instead. And as mortgage rates go up in coming years with rising interest rates , people will still need jobs. For every person who retires there is a young person leaving school or finishing university needing a job.

john
November 07, 2021

J
Yep, made redundant by NSW Govt in 2020. Called "voluntary redundancy" by the HR dept. but certainly wasn't from my perspective. Take redundancy payout and accept voluntary classification or struggle financially.
So job market can get stuffed at this point, will sit on sidelines for as long as possible.
HR gatekeepers and departments are the driving force in the great switch off for many workers.


Leave a Comment:

RELATED ARTICLES

Jobs Summit keynote: the changing Australian economy

Soft labour market's impact on retirement outcomes

Why have Australian living standards 'fallen' and how do we fix it?

banner

Most viewed in recent weeks

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

Latest Updates

Fixed interest

Higher yields are creating opportunities in global bonds

Bond markets are adjusting to a new reality, but not in the ways investors expect. With markets repricing and capital competing for attention, investors may need to rethink where resilience and opportunity lie. 

Economy

Are we in a recession?

What if the warning signs are already everywhere? From supermarket aisles to company failures, investors are being bombarded with recession signals. But most face a different risk that can be just as dangerous for portfolios. 

SMSF strategies

Meg on SMSFs - Division 296 actuarial certificates

The tax bill might be yours, but the event that caused it may not be. A key Division 296 calculation can sometimes attribute earnings in ways that many SMSF trustees won't instinctively expect or fully appreciate.

Property

The first impact of negative gearing reform is not the tax bill

Negative gearing changes formally begin in 2027, but the first consequences may already be here. A subtle shift is quietly influencing who can borrow, how much they can access and which property strategies still stack up.

Economy

The oil market is running out of easy answers

The biggest threat to markets may not be what investors are watching. The numbers have stopped adding up and supply is harder to measure, with forecasts becoming simple guesses. A more fragile reality is being masked.

Investment strategies

The state of investor knowledge in Australia

Australians are investing more than ever, yet a surprising divide is emerging between those building wealth effectively and those making costly mistakes. Surprisingly, the gap has little to do with income, age or starting capital.

Taxation

Complexity and capital gains

A case study shows that the ‘30% minimum CGT’ is a poorly conceived tax that adds significant complexity to an already over-complex system. A less complicated model would create a much fairer progressive tax scale.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.