Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 190

Size matters for SMSF performance

An SMSF needs a balance of at least $200,000 to be cost-effective and sustainable, new research by SuperConcepts and The University of Adelaide’s International Centre for Financial Services has found.

A major study, When Size Matters: A closer look at SMSF performance, based on more than 88,000 fund-year observations, examined the performance of four fund sizes. The study found that SMSFs with balances over $200,000 significantly outperformed smaller funds in both cost-effectiveness and investment diversification. All SMSFs in the study had outsourced their administration.

Just over 20,000 individual funds, with an average asset value of $845,000 and average annual expenses of $8,919, were examined using figures from the 2008-9 to 2014-15 financial years.

The fund sizes were:

Size 1 funds: Asset values less than $200,000

Size 2 funds: Asset values between $201,000 and $500,000

Size 3 funds: Asset value between $501,000 and $1,000,000

Size 4 Funds: Asset values greater than $1,000,000.

As shown below, SMSF performance was found to be relatively similar for size 2 to 4 funds, although fund size 4 outperformed the others slightly during the last three fiscal years of the study period. The smallest size 1 funds consistently underperformed against all other sizes, and posted negative returns in five of the seven sampled financial years, including the last four.
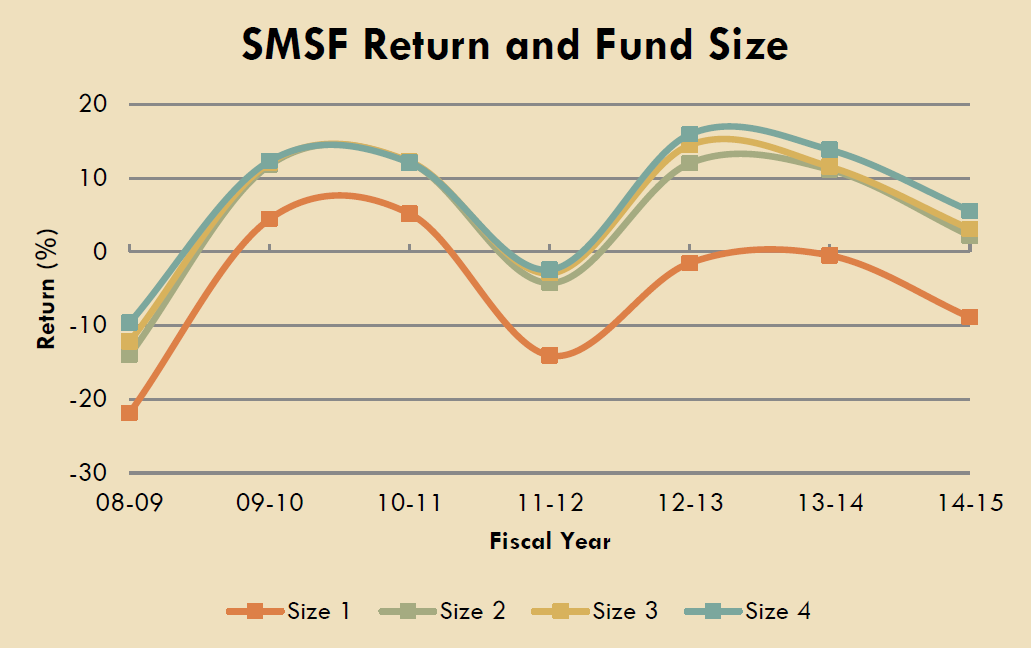
SMSF performance

SMSF performance

Diversification into asset types

The study measured diversification by the number of asset classes in which a fund had invested with a weighting of 10% or more.

The largest size 4 funds held significantly more asset classes than size 1 SMSFs and, in fact, a balance of less than $200,000 showed deterioration in asset diversification.

“Fund diversification has, on the whole, marginally improved over time,” the report says. “At the beginning of our sample period, the average fund held investments in 2.06 asset classes, and this has increased to 2.15 at the end of our sample period. We observe an inverse relationship between the level of diversification and the volatility of fund returns.”

Expenses come in many guises

SMSFs incur many establishment and administration costs. The ATO’s list of common costs include:


  • actuarial costs


  • accountancy fees


  • audit fees


  • costs of complying with Government regulations


  • investment adviser fees


  • SMSF’s annual lodgement fee


  • life insurance or total and permanent disability insurance premiums


  • investment research subscriptions, and


  • costs for amending a trust deed.


As funds grow larger, the expense ratio drops due to greater operational efficiency.

“Expense ratios for the largest funds (size 4) are significantly lower than the expense ratios for the smallest funds (size 1). When a fund passes a threshold of having $550,000 under management, its expense ratio dips below 2%, whilst diversification and performance of the fund is comparable to any of the larger funds. Below this threshold, performance, diversification and expenses begin to deteriorate”.

The study concludes that while performance, diversification and expense ratios continue to improve as funds grow, these traits deteriorate in funds with asset balances below $200,000, making smaller funds inefficient. Some commentators suggest that small SMSFs are not sustainable and that the government should legislate a mandatory minimum size to start an SMSF.


Lee Anthony is studying for her Masters of Publishing at the University of Sydney. The full report can be downloaded here: 'When size matters: A closer look at SMSF performance'.

  •   16 February 2017
  • 5
  •      
  •   
5 Comments
Doug
February 16, 2017

One reason that smaller funds underperform is the size of the Admin fees. I have been quoted anything between $790 for full admin including audit to $3500. I think a lot of advisors and accountants see SMSF management as a new cash cow.

SMSF Trustee
February 16, 2017

Sorry to be really blunt, but that's nonsense Doug. For the work that is done by anyone doing even a half decent job of auditing, doing tax returns and managing ATO relationships, processing investment switches, providing reports on fund income, capital gains, etc, admin fees of anything less than $5000 are very, very cheap in my view.

My fund is at the larger end of what's in the survey and I pay just over $10,000 a year in admin fees, but the work that's done gives me total peace of mind about the Fund complying with the law and being properly managed at all times.

Get real about the costs of investing people!

Doug Reynolds
February 16, 2017

Sorry SMSF but I have to disagree with you. My administrator charges $795 and does a great job.

SMSF Trustee
February 16, 2017

I'm not sure if the Doug to whom I replied is the same as Doug Reynolds, but on the assumption that he is, then I'm sorry if I misunderstood what you were saying. I read the original post as saying that fees of $790 up to $3,500 were a rip off, as advisors just seeing SMSF as a cash cow by charging those fees. If that's not what you were saying then perhaps we're actually in agreement, but that's how I read it.

If you're getting a great service for $795 then that's fantastic. It sounds like just a basic compliance service, not a full self-management capability (mine includes trading on-line, fund information and research, information about legislative changes, full audit and tax returns, daily valuations of all assets and on-line access to valuations, etc). But if it gives you what you want, that's excellent.

Doug
February 16, 2017

Hi SMSF Trustee,
What I meant was I was given those quotes for just the same basic service. I have no problem with paying more for further services but that was not what I was offered by the four administrators that asked for quotes after having personal meetings with three. I ended up going with an internet service.


Leave a Comment:

RELATED ARTICLES

The SMSF gaps in the Productivity Commission’s Superannuation Report

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Higher yields are creating opportunities in global bonds

Bond markets are adjusting to a new reality, but not in the ways investors expect. With markets repricing and capital competing for attention, investors may need to rethink where resilience and opportunity lie. 

Will investors be better or worse off under new housing tax changes?

Housing tax reforms have sparked warnings of market turmoil and promises of greater fairness. But after modelling nearly two decades of property data, the results suggest winners and losers may not be who many investors expect.

Latest Updates

Superannuation

Superannuation’s structural failings

Politicians are fighting over access to super, but they may be arguing about the wrong thing. The system’s three fundamental flaws have been hiding in plain sight for decades, costing Australians far more than they realise.

Planning

The great wealth transfer myth

Why do some families preserve wealth for generations while others struggle to? As the great wealth transfer unfolds, the determining factor is often not the structure of the estate, but the preparation of those who will inherit it.

Investment strategies

What comes after bank hybrids?

For years, bank hybrids have been a cornerstone of portfolio income. With tens of billions of dollars now disappearing from the market, investors face a critical question: what comes next, and are the obvious replacements enough?

Investment insights from the US

What happens when knowledge becomes a commodity? The latest themes emerging from the US tech sector suggest AI could reshape company moats, disrupt incumbents and create winners and losers in unexpected places.

Investing

Can Berkshire thrive without Buffett?

Warren Buffett's departure marks the end of an era. But the more important question for investors is whether Berkshire's culture, discipline and capital allocation framework can survive without the man who built them.

Retirement

The Bengen 4% Rule: Lost in translation

For years, retirees have been told to focus on withdrawal rates. But the real question is far simpler: how many dollars can you safely spend? The answer may be very different from what conventional retirement wisdom suggests.

Interest rates

Super low interest rates came with side effects

For more than a decade, investors lived through an era of near-zero interest rates. With bond yields now surging, it's worth asking whether cheap money solved economic problems, or introduced a much larger set of risks.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.