Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 387

Three reasons why super performance test fails

This year’s Budget included the Your Future, Your Super (YFYS) reform package, which will have a significant impact on superannuation. One reform, a performance test, has proven highly controversial. A performance test sounds like good policy to protect consumers, so why is it proving so controversial?

This article uses some of the findings from a collaborative research effort between The Conexus Institute and five leading industry consultants: Frontier, JANA, Mercer, Rice Warner and Willis Towers Watson. The detailed research (papers and models) can be accessed here.

The performance test explained

The YFYS performance test works as follows:

  • Over a rolling 8-year period the performance of each fund is compared against the performance of a tailored benchmark based off that fund’s strategic (i.e. long-term) asset allocation through time. The benchmarks are all public listed market indices. This could be considered implementation performance, capturing the sum of how well each portfolio position performed against a benchmark as well as the performance of any short-term (tactical) asset allocation calls.
  • Initially if a fund fails the test (underperforms by more than 0.5% pa), it needs to write to its members to advise it has been identified as an underperformer, and provide details of a to-be-developed Government website which will detail performance and fees for the universe of super funds.
  • If the fund fails for a second consecutive year, it is no longer able to accept new members until the fund passes the performance test. The fund can continue to accept contributions from existing members.

This sounds reasonable, so what is the problem?

The concept of a performance test is good policy. Done well, it helps protect disengaged members from sub-standard outcomes from super. Government and Treasury are simply following a recommendation made by the Productivity Commission.

But the devil is in the detail: the performance test has important shortcomings. Additionally, there are concerns that the way the test is applied will likely leave some consumers worse off.

We found three main issues with the test, summarised in the following diagram.
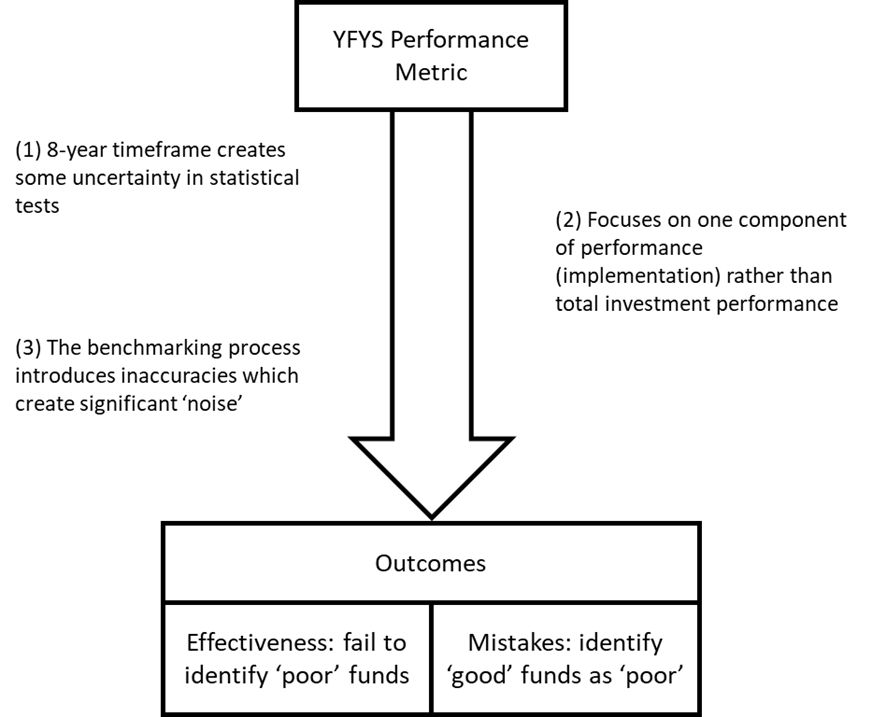
(1), (2), and (3) combine to make for an ineffective performance test.

Here's how to understand (2) better: implementation is an important part of total performance but the asset allocation decisions made by funds are just as, if not more, important. Yet the test ignores the performance of asset allocation decisions. To illustrate, if your fund had made the decision to have 10% more allocated to global shares than to Australian shares over the last 10 years, this would have added more than 0.4% pa to performance. A performance test should capture this component of performance.

The benchmarking challenges noted in (3) impact the assessment of many asset classes including private equity, unlisted property and infrastructure, credit, inflation-linked bonds, and the entire universe of alternative investments.

For example, unlisted property is benchmarked against listed property and there can be huge dispersion in performance between the two sectors which may unduly impact the performance test result at a particular point of time.

In some cases, we calculated that the test would have a very low likelihood of correctly identifying poor performers (likelihood levels akin to a coin toss) while having a reasonable probability of mistakenly identifying good performers as poor.

Finally, none of this acknowledges changes that funds have made to improve themselves, sometimes in response to issues raised by APRA.

Ineffective plus undesirable outcomes

Not only is the test likely to prove ineffective, but we anticipate a range of undesirable outcomes. We summarise these into three categories:

  1. We believe the test will distort the way that funds will manage their investment portfolios. This test will likely be binding compared to other policy and regulatory tools such as APRA’s Heatmaps, the Outcomes Assessment Test and the sole purpose test. The flaws in the test mean it does not align well with the broad investment management principles of focusing on total returns and diversification.
  2. We believe consumers will be confronted with a range of complex and potentially conflicting information. Many will find making a choice difficult and the heavily disengaged may be left in impaired super funds and experience worse performance (because the fund is further impaired).
  3. The focus by industry on the performance test may deter fund mergers. The ‘senior’ fund may not want some of the assets, a membership profile in outflow, nor the distraction that comes with merging with another fund.

Agents, politics, and policy

Unfortunately, superannuation has become highly politicised and some observers view the industry as self-interested agents. Yet strong engagement can contribute to better policy, while poor engagement increases the risk of policy mistakes. Effective engagement requires the trust between policymakers and industry to be strong. Undoubtedly there is room for improvement, but I see both policymakers and industry aligned in their focus on improving member outcomes.

It is good to see that there will be consultation on the performance test and hopefully it is constructive and positive.

Developing an effective performance test is a great opportunity to improve superannuation outcomes for consumers.


David Bell is Executive Director of The Conexus Institute, a not-for-profit research institution focused on improving retirement outcomes for Australians. This article does not constitute financial advice.


  •   9 December 2020
  • 2
  •      
  •   
2 Comments
Ramani
December 09, 2020

DC Super has relied on robust compliance processes (internal, external audits, prudential reporting, disclosures, conflict management and convergence between good performance and inflows) and many motherhoods (fiduciary interests, outsourced and out-of-mind and enforcement that conflates actions with outcomes). This has not worked on disengaged members who when interested find the rules indecipherable. Hence the move towards performance mesaurement, naming and shaming and effective delicensing.
We moved away from the model that promised performance (called DB). For good reasons. Is this a back-door reentry?
This article highlights how great intentions get stuck. Ignoring risk prferences, changing personal needs and potential for ponzi scams would simply raise expectations without altering the likelihood and impact of type 1 and type 2 errors. Makes the fall more traumatic.
The elephant in the room? Governments and regulators getting too close to fund performance exposes them to compensation claims for policy and prudential malfeasance. The bill will be picked up by the taxpayer who already underwrites super through tax subsidies hoping for the mirage of lower age pension outlays.
Not unlike the state getting too close to citizens' health by getting involved in Body Mass Index control. Great but counter-productive.

Jeremy Dawson
December 12, 2020

Is this requirement (to not underperform by more than 0.5% pa) before or after accounting for what my fund calls
"Total investment fees and costs and transaction costs"?

If before - then it's not a good criterion for investors. If after - then it makes it difficult for a fund to not underperform stock market indices (my fund says Total investment fees and costs and transaction costs are 0.46%)


Leave a Comment:

RELATED ARTICLES

Consumers need an effective super performance test

Extending performance tests to retirement super is a bad idea

The current super system fails the poor

banner

Most viewed in recent weeks

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Superannuation’s structural failings

Politicians are fighting over access to super, but they may be arguing about the wrong thing. The system’s three fundamental flaws have been hiding in plain sight for decades, costing Australians far more than they realise.

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Higher yields are creating opportunities in global bonds

Bond markets are adjusting to a new reality, but not in the ways investors expect. With markets repricing and capital competing for attention, investors may need to rethink where resilience and opportunity lie. 

Latest Updates

Retirement

The retirement account that Australia should have

Our retirement system asks one account to do two very different jobs. A dedicated "rainy day" account separating income from emergency savings could deliver better outcomes and greater peace of mind for retirees.

Investing

What the US midterm results mean for investors

Democrats have regained control of Congress, changing the equation in Washington. Whether that proves positive for investors will depend less on the result itself and more on what happens next for growth and markets.

Taxation

Should the capital gains tax reward risk?

A reader query on the recent CGT reforms has revealed a bigger issue. One overlooked feature of the old system may have done more than compensate for inflation. As we move to indexation, are we forgetting to reward risk?

Investment strategies

Bonds: The income and diversification trade-off

Rising yields have made bonds attractive again, but that does not mean they will behave as expected. As inflation, fiscal pressures and geopolitical risks reshape markets, the role of bonds may be more complicated than it appears.

Investment strategies

Why high-dividend investing deserves another look

Income investors have endured several lean years, but signs of a recovery are emerging. As opportunities improve, investors face an important choice between chasing headline yields and building a reliable source of income.

Investment strategies

Why 'overvalued' has been such an expensive word

Investors love simple rules, especially when markets appear stretched. Yet some of the strongest returns have arrived when the outlook seemed least attractive. This leaves an important question that history struggles to answer.

Investment strategies

AI – A good kind of bubble or just a bubble?

Investor obsession with AI is attracting unprecedented amounts of capital and confidence. But beneath the excitement lies uncertainties about returns, funding and risks that enthusiasts may not be paying enough attention to.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.