Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 551

Toyota: How the hybrid engine regeared the investment case

The world’s biggest car company is reaping the rewards for a multi-pronged approach to reducing CO2. Here’s why that’s good news for investors.

Toyota has been a long-term holding for us, and it’s been a relatively easy decision to own it. After all, Toyota is:

  • the world’s largest car maker 1
  • the world’s 6th most valuable brand 2
  • the company that in many ways redefined modern manufacturing through just-in-time delivery and its kaizen and kanban production practices.

In late 2023 we began to positively reassess our Toyota position as we discerned some key trends in the battery electric vehicle (BEV) market.

EVs and a range of anxieties

Over the past few years, growth in Electric Vehicle (EV) sales has been staggering. Global sales doubled in 2021. They grew by 60% in 2022 and were up around 30% in 2023.3 But in late 2023 the pace of growth in EV demand began to slow (especially in Europe and the US, much less so in China). More cost-conscious mainstream buyers baulked at high sticker prices, soaring insurance and repair costs, problematic resale values and range anxiety due to inadequate charging infrastructure.

Meanwhile, regulatory backing for EVs became less of a one-way street. In some countries, subsidies have been reduced. In the US, unions and car dealers are pressuring the Biden government to wind back policies that push rapid BEV adoption.

Toyota says “not yet”

The slowdown in EV growth had some interesting implications for Toyota.

While US giants like Ford and GM and European car makers like Volkswagen had made early commitments to a BEV future, Toyota maintained that hybrid vehicles (a technology they invented with the Prius in the late 1990s) offered the most practical pathway to lower emissions.

Chairman and former CEO, Akio Toyoda said one billion people around the world live in areas without electricity. In the case of Toyota, they also supply vehicles to these regions, so a single battery-electric vehicle option cannot provide transportation for everyone and that’s why they are trying to have a variety of options.

Strategically that’s turned into an astute decision.  Demand for hybrids is soaring.

  • In the first nine months of FY2024, Toyota and Lexus retail sales rose 9.7% Year-on-Year (YoY).
  • Sales of their electrified vehicles - mostly hybrids – accelerated 41% YoY) over that period. They now account for 36% of total sales.
  • In Europe, over 60% of Toyota and Lexus sales in FY2023 were hybrids.

Toyota’s shift to hybrids is good for profitability as well as volume. Partly that’s a function of increasing demand. But its famed engineering excellence also means Toyota can now make the more complex hybrid drivetrains much more efficiently.  They now make as much profit on hybrids as on Internal Combustion Engine cars.

The investment case

Toyota could be entering a period of ‘breakout profitability’. In the short-term, the BEV market is crowded and slowing so there’s lots of pressure on BEV companies outside China to cut costs – a trend that’s already hitting Tesla. Positioned as it is, Toyota avoids getting caught up in a margin-cutting BEV price war while at the same time capturing all the benefits of a growing hybrid market through higher volumes, more pricing power and stronger earnings.

While hybrids have been viewed as a ‘transition’ technology, the Toyota view is that many consumers now prefer hybrids – and may continue to do so. As we write, Toyota is trading on a P/E ratio of 10x, only slightly above its long-term averages. Yet it looks poised for sustained growth.

New technologies - and more chargers - could end 'range anxiety' and take EVs mainstream.
Image Source: Adobe

The future is still bright for electric

It’s crucial to note that Toyota is not writing off the BEV market. Even with the recent blip in Europe and America, the case for electric vehicles remains strong. The driver experience is different – and many say better. New European emissions standards due in 2025 may add impetus to European demand.

Perhaps most importantly, car makers are increasingly focused on making more affordable EVs that can appeal to the mainstream driver. BYD in China, for example, is a leader in this effort but other makers are also adapting their approach to both the underlying technologies and the cost profiles of their BEVs.

Toyota is also focused on developing a range of technologies that will make it even more competitive in a world focused on low-carbon transportation.

They aim to produce around 3.5 million BEVs by 2030 but these will be powered by newly-developed bipolar and solid-state battery technology that promise longer range and faster charging. To deliver those new technologies, it is spending the equivalent of US$60bn on electrification through 2030. Toyota is also unwinding its cross shareholdings of other companies and plans to invest the proceeds in electrification.4

For us, the investment case for Toyota now has further improved:

  • It passed the BEV-trend test by sticking to its strengths (hybrids) in a way that met customer needs whilst boosting the bottom line.
  • It’s investing heavily in R&D to make it competitive in a low-carbon world.
  • In its recent third quarter results the company committed to better shareholder returns through higher dividends and buybacks.
  • Its valuation remains reasonable.

Toyota also has an outstanding competitive position. It’s a quality business with strong brand equity. Their cars are highly rated for reliability and have outstanding resale value. That represents good value for the people driving the world’s Camrys and RAV4s. High demand for hybrids also means limited inventories and Toyota pays out lower incentives than the industry average. So it’s good for investors too.
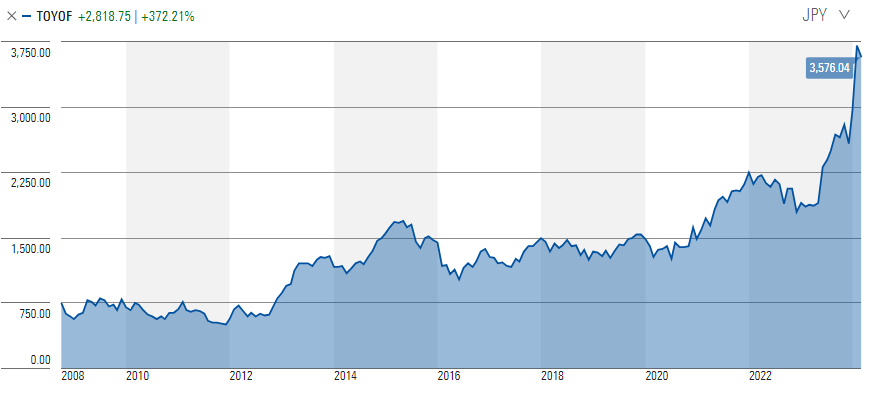

Source: Morningstar.com. End of Date as of Mar 8, 2024.


As at February 2024, Toyota is a holding in the Platinum International Fund and the Platinum Japan Fund.

[1] It sold over 9.5 million vehicles in 2023
[2] Source: Interbrand Best Global Brands, 2023
[3] Source: Benchmark Minerals
[4] For more on a new shareholder-friendly culture in Japan see our recent article: Japan’s reform. New dawn or same old story.


Leon Rapp is Co-Portfolio Manager, Japan Strategies at Platinum. This information is commentary only (i.e. our general thoughts). It is not intended to be, nor should it be construed as, investment advice. To the extent permitted by law, no liability is accepted for any loss or damage as a result of any reliance on this information. Before making any investment decision you need to consider (with your financial adviser) your particular investment needs, objectives and circumstances.

For more articles and papers by Platinum click here.


  •   13 March 2024
  • 4
  •      
  •   
4 Comments
Declan R
March 17, 2024

Still think it will be hard for companies like Toyota to adjust to a greater EV world. It's the innovators dilemma: getting rid of the old ways of doing things and systems to develop something new.

Reckon it's to early to declare victory for Toyota.

George B
March 17, 2024

A company that had the foresight and innovation to develop a reliable hybrid vehicle in the late 90s (Prius) should have no trouble in keeping up with EV technology and to make it reliable in the 20s and beyond. In fact its arguable that hybrid technology is an ideal transitional technology in a world that is transitioning from ICE to EV vehicles and for people that want to dip their toe into EV tech without going the full monty particularly as charging infrastructure is still hit and miss in the country.

Steve
March 17, 2024

It will be interesting to see by 2030 how many of the pure EV plays actually work out; many European manufacturers are back-peddling already. Even now we are seeing the enthusiasm for EV's drop as real world practicalities become more visible to the public. I suspect the Toyotas of the world could grab massive market share when the EV bubble starts to pop. There's a whole lot of world outside the inner cities where EV's are totally impractical for most people.

Richard
March 17, 2024

Hopefully hybrids will come to be seen as an acceptable ‘end game’ and not just ‘transitional’.


Leave a Comment:

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Latest Updates

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Latest from Morningstar

Does an American retirement rule work for Australians?

The 4% rule has survived decades of scrutiny, but Australia's retirement system changes the equation in ways most overlook. Before accepting or rejecting this rule of thumb, it pays to understand what really drives retirement outcomes.

Shares

Glencore lands on the ASX. Should BHP and Rio shareholders switch?

A coal-heavy miner with governance concerns isn't the obvious choice for investors. Yet, Glencore's ASX listing may offer something BHP and Rio can't. The challenge is working out whether the opportunity outweighs the risks.

Why does the system treat capital gains and losses differently?

Investors are often told not to let tax policy drive their investment decisions. Yet, under the new CGT rules, portfolio construction, volatility and even how assets are owned may have an outsized impact on their final outcome.

Economy

Three common sense reforms that Australia needs

What do frozen bank accounts, mortgage traps and pension penalties have in common? They're all symptoms of a system that makes life much harder. Yet the obvious solutions seem to have escaped the attention of Canberra.

Shares

The hidden cost of government debt for investors

Some of the important effects of rising public debt never make the headlines. Research shows the immediate effects may already be unfolding, influencing corporate behaviour in ways that many investors would never suspect.

Investment strategies

When do fundamentals matter?

Is fundamental investing losing its grip on markets? Investors continue to search for valuation-based explanations for every price move, but the dominant force behind short-term returns may be something else altogether.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.