Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 129

Trusted professions go with the Flo’

Trust. It's at the heart of finance. Trust is that special property that bends time, allowing for the provision of a good, service or facility today on the strength of a belief that the other party will honour its financial obligation to make payment at or before some later date.

So central is trust to finance that the word ‘credit’ has its origin in the Latin crédere, which means to believe (and from which credo is also derived). The sudden collapse of trust in finance can be catastrophic, as demonstrated dramatically by the demise of the 158-year-old Lehman Brothers in the space of a few short months during 2008.

If the existence of trust lubricates the wheels of commerce and its absence acts as a retardant, then clearly being 'trusted' is economically advantageous. So just what makes one profession more trusted in the eyes of the public when compared to another?

Trust across professions - a survey approach

Unlike temperature or barometric pressure the measurement of trust resides not in the domain of physics but in sociology. Trust tends therefore to be measured by surveys that rank occupations across a scale from least trusted to most. One Australian example is the annual Roy Morgan Image of Professions Survey, run continuously since 1987 and expanding from an original 19 occupations to 30 now.

The Roy Morgan Survey respondents score people in various occupations for honesty and ethical standards using one of five possible responses; Very High, High, Average, Low or Very Low. A selection of these occupations appears in the table below, ranked highest to lowest for 2015.

The percentage of respondents rating each occupation as “Very High” or “High” for ethics and honesty for 2015 were:
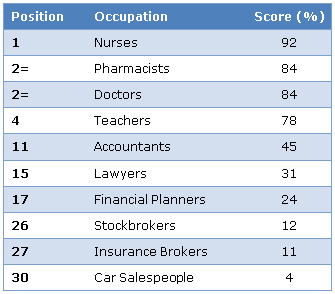
Source: Roy Morgan Image of Professions Survey.

The results are unequivocal. Nursing is the most ethical and honest profession for the 21st year in a row. It's quite a gap to the next most trusted professions at 84%, jointly held by pharmacists and doctors, with teachers rounding out the top four.

And what of professions connected to finance, commerce and investing?  Accountants fare relatively well, sitting in the top half in 11th spot. Lawyers sit mid-pack, holding 15th on 31%, whilst financial planners sit two below lawyers in 17th place on an ‘approval’ score of 24%.

Other professions are clearly perceived as being less trustworthy. Amongst these are stockbrokers (26th), insurance brokers (27th) and finally in last place, car salespeople at a score of 4, a position held for 28 years in succession.

Why are nurses so trusted?

Part of the answer might lie in the high standard of training and education required. Most states require a minimum three year tertiary qualification to become a registered nurse. Further, once qualified, trainee nurses are under strict supervision, gradually increasing the range of treatments and medication they are allowed to administer as their experience builds.

Nursing is also a profession with a rich history of compassion, empathy and service. From Florence Nightingale tending the wounded in the Crimean War to the volunteers who battled the recent Ebola outbreak, nursing is a profession emphatically linked to the service of others over the advancement of self.

Can financial planners bridge the gap to nurses?

It’s clearly a long haul from 24% to 92%. Financial planning’s cause hasn’t been helped by a series of advice scandals over the past several years, some involving Australia’s largest financial institutions. In the wake of these scandals, the laws governing the provision of advice have been strengthened. Yet these are only part of a greater shift that must occur if financial planning is to sit amongst the truly trusted professions.

If you’re in a profession struggling with trust and credibility, nursing is a model of professionalism worth aspiring to. Modern nursing has a clear and unbroken lineage to the pioneering work of The Lady with the Lamp, as Florence Nightingale came affectionately to be known.

Nightingale was not a nurse by training. How could she be when no such training existed in mid-1800s Britain? She was in equal parts social reformer and statistician. Among her many contributions was the development of the pie chart to illustrate numerical proportion. With this and other novel data visualisation techniques she conveyed information vital to both the Crimean War effort and public hygiene more generally, and for her efforts became the first female member of the esteemed Royal Statistical Society.

Nightingale is best remembered, however, for establishing the foundations of the nursing profession in 1860. The principles she espoused; of service, diligence and compassion, together with a body of knowledge based on scientific observation and measurement, still resonates in the Nightingale Pledge which, although modernised since its first incarnation in 1893, remains at the core of nursing’s code of ethics in most jurisdictions.

Earning trust, and keeping it

Professions who find themselves not as universally trusted as nursing might first seek to focus on finding their reason for being, a reason other than the accrual of monetary benefits and material possessions. Unlike financial planning, nursing suffers little in the way of principal/agent effects. These effects present themselves when a person tries to simultaneously serve two parties with opposing interests. It is fair to surmise that in any hospital the patient, loved one, doctor, nurse and hospital board are all pulling in the same direction – a speedy recovery and discharge.

Perhaps the last word on trust is best left to the father of modern economics, Adam Smith, who in his 1759 work The Theory of Moral Sentiments, suggested that one should seek not to be praised but instead first to be worthy of praise.

In a similar vein, if financial planners wish to emulate the trusted status of nurses they should seek first not to be trusted, but to be worthy of trust. The pie chart, a tool used by financial planners the world over to sell complex investment concepts to clients, was after all first perfected by the lady who wrote the book on trust.


Harry Chemay is a former Certified Financial Planner who previously practised as a specialist SMSF advisor and as a consultant to APRA-regulated superannuation funds. He is CEO and co-founder of the automated investment service at www.clover.com.au.


  •   8 October 2015
  • 3
  •      
  •   
3 Comments
Martin Mulcare
October 09, 2015

Thanks, Harry,
I appreciate the lessons from the nursing profession. I also think that there is a valuable lesson to be gleaned from the professions in equal second place. At the risk of being simplistic, they provide a great lesson in the potential value of separating advice (doctors) from product (pharmacists) to the benefit of the reputation of both professions.

Rebecca Boles
October 10, 2015

A great point to raise Harry! It's pretty horrifying to see planners so far down the list. I would be interested to hear how this could be strengthened (or adversely affected) by the introduction of robo-advice.

Harry Chemay
October 12, 2015

Hi Rebecca. Thanks for your comment. On the positive side Financial Planners, whilst at the lower end of the scale, are seen as more trustworthy than business executives, talk-back radio personalities and members of parliament. Make of that what you will. That said, there's clearly a lot more work to be done, above and beyond current regulatory initiatives, to drive financial planning further up the trust rankings.

For financial planning to cement its position among the ranks of highly trusted professions, hard conversations must first be had as to why the industry exists in the first place. Is it to be a source of distribution for product manufacturers? Or does it exist to help people organize their lives so that they can be their best financial selves?

Those planning businesses wedded to the former proposition will struggle. No longer is the planner the font of all knowledge and sole source of information on investment products and strategies. Playing 'gatekeeper' to information that is freely available on the web is a shaky foundation for the planning practice of the 21st century. That train has already left the platform. What's needed, desperately, are planners who coach, mentor and challenge clients to be their best financial selves. And yes, that means the occasional 'honest conversation' to keep clients on track to achieving their goals.

'Robo-advice' (I personally dislike this term for its pejorative connotation) will empower the latter type of planner whilst challenging the former. These automated investment services will allow people with less complex needs to invest without having to go though the traditional financial planning process. And let's face it, for very many Australians that process is cumbersome, time-consuming and of questionable financial value (here the regulatory burden has to share some of the blame).

'Robo-advice' may actually turn out to be an entry point for future full financial planning clients, as the circa 75% of unadvised Australians gain access to this type of technology. Shifting through life-stages will naturally create the need for quality personal advice between an adviser and former 'robo-only' user. There will always be a need for quality personal advice, but at the right time and for the right reasons. Even here however I see robo-advice platforms powering that interaction in the years to come, with 'big picture' conversations between adviser & client framed around future goals, dreams & aspirations, with the adviser's 'robo' doing the heavy quantitative lifting of probabilistic projections, goal optimization & investment strategy execution and monitoring.

'Robo-advice' will not disrupt competent forward-thinking planners any more than spreadsheets disrupted the accounting profession twenty years ago. Rather than disrupting accounting the spreadsheet revolution powered a whole new breed of accountants, able to use this new technology to generate new value-added revenue streams. What we don't see anymore (at least I don't) are dimly-lit rooms full of visor-wearing accountants cranking the arms on their calculators, ready to make written entries into their double-entry journals.


Leave a Comment:

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Latest Updates

Retirement

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

2026 is not 1999

The US market looks eerily similar to the dot-com era with soaring AI spending and tech giants dominating returns. But one difference separates today’s boom from the dot-com bubble and it could determine what happens next.

Planning

Taxing time for trusts

Trusts are facing a shake-up, but an overhaul may not be necessary. Families can explore restructuring strategies that preserve succession and the asset protection benefits that have made these structures valuable.

Economy

Why the US economy is stronger than you might think

War, inflation and higher rates were expected to derail America. But has the market got it wrong? Three forces are driving the economy beyond expectations, revealing implications for stock prices and portfolio positioning.

Gold

How much trust is in your portfolio?

Everyone talks about diversifying assets. Far fewer think about diversifying trust. As inflation, debt and market assumptions collide, the question is whether portfolios need greater protection from unexpected outcomes.

Retirement

Retirement in reality - 7 months in

Seven months into retirement, I'm still uncovering surprises. This month was spent reflecting on the slow pace of health change, the myth of neatly scheduled part-time work and the unexpected persistence of retirement guilt.

The new geography of technology leadership

The next chapter of technology may not belong to the companies or business models many expect. As the landscape shifts, some opportunities are emerging in places that remain surprisingly overlooked by global markets.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.