Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 462

Two companies with clear competitive advantages.

After the turmoil of recent years, many had hoped that 2022 would see a return to a more normal environment. However, the year has been punctuated by macro events such as the crisis in Ukraine, and the Fed’s tightening cycle in the US is impacting equity markets globally.

As this uncertainty continues, it is more important than ever that investors have a sound investment process. It is vital not to get caught up in the hype and noise of the daily market movements, and instead invest with a long-term approach. To help with this, it may be useful to have some guidelines to fall back on when the market noise gets too loud.

Companies that have a sustainable competitive advantage will be better placed to withstand short-term headwinds, maintain market share, and ultimately find new ways to grow.

It can however be difficult to recognise this potential in companies, particularly those that are in the growth stage of their life cycle. And while challenging, it is also important to balance both the narrative and the numbers.

By drilling down into a company’s financials and growth plans, it is possible to identify the quality growth stocks that will prosper over the long-term. The best way to explain how this process works is through a couple of examples.

CSL’s M&A activity

CSL is a multinational biotechnology company that operates in both plasma and influenza markets. It was founded in 1916 and listed on the ASX in 1994.

Throughout its history, it has been able to create a competitive advantage in the areas it operates in through acquisition and combining product portfolios, manufacturing, and distribution to boost the value of the acquired companies.

It has a good historical track record of efficiently deploying capital in attractive growth areas. For example, its acquisition of Aventis Behring, the second largest plasma player, in 2004 has proved to be transformative over the past 18 years. This acquisition enabled CSL to more than double the products produced per litre of plasma from two to five, as it added haemophilia and speciality products. This is now a key source of CSL’s competitive advantage in this area.

For an acquisition cost of $US925 million in 2004, the Behring division now generates US$8.5 billion in sales and US$3.1 billion in earnings before interest, taxes, depreciation, and amortisation (EBITDA).

CSL clearly has what we call a Dynamic Capability - a change-oriented capability that helps a firm redeploy and reconfigure their resource base to meet evolving customer demands and competitor strategies.

CSL has recently entered the renal and iron deficiency market with the acquisition of Vifor Pharma. The market is focussing on the delayed recovery in plasma collections, donation inflation and a US$5 billion capital raising, and has sold down CSL accordingly. However, we believe that CSL will be able to apply the earlier lessons learned via its acquisitions in the plasma and influenza markets to the Vifor acquisition and potentially dominate the renal market as well.
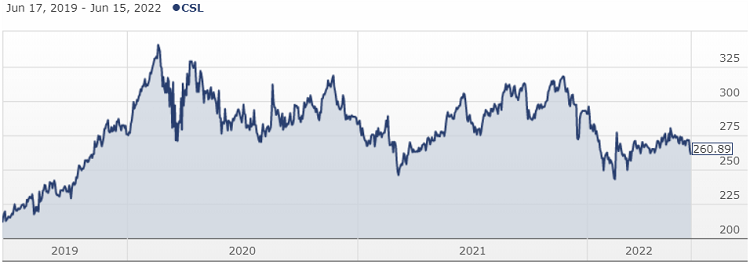

Source: Morningstar

Lovisa’s growth path

Lovisa Holdings is a fast fashion vertically integrated affordable fashion jewellery retailer. It aspires to be a global player and already has more than 70% of its stores operating overseas.

A combination of a clear specialisation in affordable jewellery, vertical integration which enables frequent inventory turnover and speed to market, and negotiating leverage due to scale and capable leadership, makes for a competitive business model.

In addition, Lovisa has a clear top-down focus on data. Stock placement is based on a design created by head office each week, using the prior week’s sales data. This universal approach to product placement generates maximum sales from Lovisa’s wall space.

Because of this focussed approach, Lovisa also has a short payback period for domestic stores of approximately eight months, with new store fitouts taking only 14 days on average.

While Lovisa’s founding CEO Shane Fallscheer retired last year, Inditex Group veteran Victor Herrero became CEO in December. Herrero’s experience managing global expansion at Inditex Group, which owns Zara, Pull & Bear and Massimo Dutti, will be advantageous to Lovisa’s global growth plans.

Lovisa’s proven and astute business strategy, combined with superior management, make it a Quality Franchise that presents a long-term opportunity for investors.
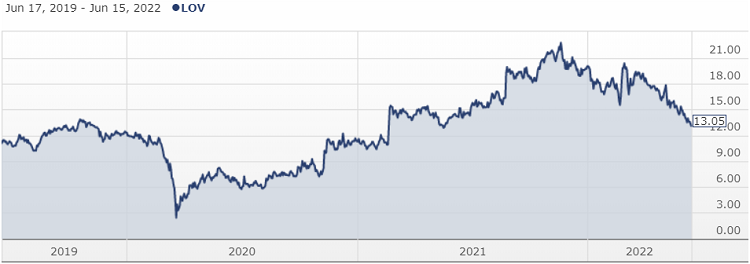

Source: Morningstar

Common ground

While CSL and Lovisa seem, at face value, to be very different companies, they have key characteristics in common. Both have the ability to assess market needs quickly and adjust their offering rapidly to meet changing demand or requirements. They have also successfully expanded into global markets with little impact on the effective management of the business.

The ability to be flexible, to move quickly to take advantage of opportunities as they arise, and capitalise on market trends and demand, will continue to support the ongoing success of such businesses, and provide significant long-term opportunities for their investors.


Dr Manny Pohl is Founder and Chairman of ECP Asset Management. This material has been prepared for informational purposes only and is not intended to provide and should not be relied on for financial advice.


  •   15 June 2022
  •      
  •   


Leave a Comment:

RELATED ARTICLES

UniSuper CIO shares his reflections on the 2025-2026 financial year

Preparing for next decade's market winners

Is there still value in high dividend-yielding companies?

banner

Most viewed in recent weeks

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

The investing rule that explains the next market crash

What if investment success depends less on picking the right assets and more on understanding the decisions of other investors? A principle borrowed from game theory offers a different perspective on markets.

Latest Updates

Fixed interest

Higher yields are creating opportunities in global bonds

Bond markets are adjusting to a new reality, but not in the ways investors expect. With markets repricing and capital competing for attention, investors may need to rethink where resilience and opportunity lie. 

Economy

Are we in a recession?

What if the warning signs are already everywhere? From supermarket aisles to company failures, investors are being bombarded with recession signals. But most face a different risk that can be just as dangerous for portfolios. 

SMSF strategies

Meg on SMSFs - Division 296 actuarial certificates

The tax bill might be yours, but the event that caused it may not be. A key Division 296 calculation can sometimes attribute earnings in ways that many SMSF trustees won't instinctively expect or fully appreciate.

Property

The first impact of negative gearing reform is not the tax bill

Negative gearing changes formally begin in 2027, but the first consequences may already be here. A subtle shift is quietly influencing who can borrow, how much they can access and which property strategies still stack up.

Economy

The oil market is running out of easy answers

The biggest threat to markets may not be what investors are watching. The numbers have stopped adding up and supply is harder to measure, with forecasts becoming simple guesses. A more fragile reality is being masked.

Investment strategies

The state of investor knowledge in Australia

Australians are investing more than ever, yet a surprising divide is emerging between those building wealth effectively and those making costly mistakes. Surprisingly, the gap has little to do with income, age or starting capital.

Taxation

Complexity and capital gains

A case study shows that the ‘30% minimum CGT’ is a poorly conceived tax that adds significant complexity to an already over-complex system. A less complicated model would create a much fairer progressive tax scale.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.