Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 435

Understanding the benefits of rebalancing

Good Strategic Asset Allocation (SAA) modelling should factor in rebalancing rules, as the rebalance benefits may be material, especially in a low-return environment. Using a simulation-based approach is sensible as it can help capture path dependencies and rebalance rules, but unfortunately it’s not implemented in practice as much as it should be.

As a result, the rebalance benefits of bonds are often ignored in formal SAA modelling and the diversification benefits are simply limited to the volatility reduction benefits only, resulting in a lower allocation to liquid defensive assets than would otherwise be the case.

Rebalancing benefits are not, however, the result of statistical anomalies or luck, but can be attributed to a unique source of risk premia (the additional return derived from accepting unique, or non-diversifiable, sources of risk).

How does Strategic Asset Allocation modelling work?

The standard approach to SAA modelling is largely as follows:

  1. Make your capital market assumptions, including asset class expected returns, confidence intervals and return correlations between asset classes
  2. Input the capital market assumptions into a mean-variance optimisation engine
  3. Observe the output (commonly called an 'efficient frontier'), select the appropriate efficient portfolio based on overall risk tolerance, and tweak where appropriate.

While in theory this makes sense, the way this is often applied in practice has some glaring issues, including conflating the return volatility over time with the dispersion of the future return distribution over a set horizon.

The other big flaw is applying a one-period approach to the entire SAA horizon despite the existing of rebalancing rules. Ignoring path dependency and one’s own rebalancing rules result in not appreciating that actual portfolio returns do not equal the weighted average returns of each building block in a multi-period framework.

The long-run benefits of rebalancing 

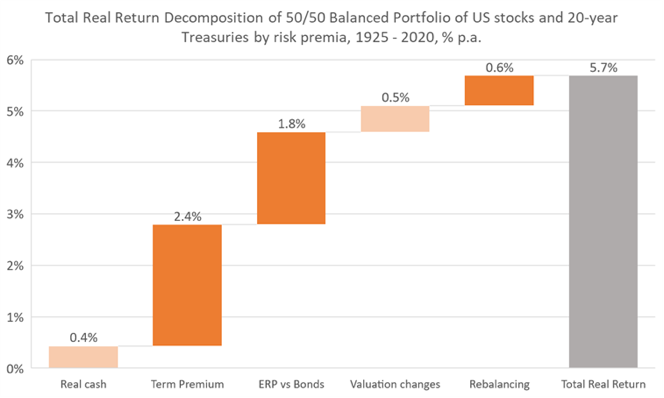
The following waterfall charts and tables demonstrate the material performance benefits rebalancing provides, using US data in 50/50 balanced portfolios of stocks and bonds from 1925 to 2020.

Chart 1 shows the total return contributions of the various building blocks to overall real returns of a balanced portfolio. In contrast, Chart 2 decomposes the contributions into risk premia, specifically:

* the term premium for duration exposures (both equities and long-term government bonds) and

* the equity risk premium (the excess returns of stocks in excess of long-term government bonds, stripping out the effects of valuation changes).

Chart 1: Real Total Return Decomposition by Asset Class Contribution
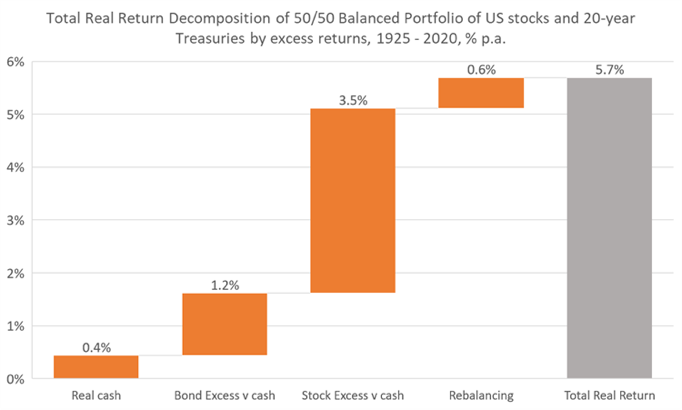
Chart 2: Real Total Return Decomposition of Balanced Portfolio by Risk Premia Contribution
Sources: Morningstar, BetaShares Capital

The ‘costs’ of chasing yield 

It’s important to be aware that rebalancing benefits are not equal across fixed income exposures.

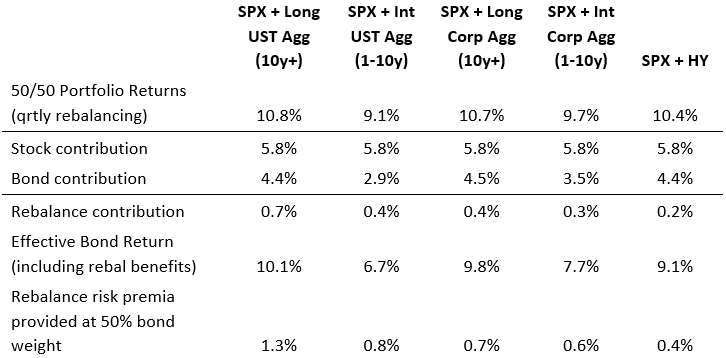
Cash and government bonds generally provide the greatest rebalancing benefits, with the benefits eroding as more credit risk is taken on. This is important, as it may be tempting to replace high-grade bonds with high-yield credit on the basis of standalone expected returns. This however ignores not only the volatility and drawdown reductions of high-grade bonds, but also their rebalancing benefits in balanced portfolios.

Table 2 illustrates this using the S&P 500 (SPX) and five different fixed income indices: 10yr+ US Treasuries (“Long UST Agg”), 1-10yr US Treasuries (“Intermediate UST Agg”), 10yr+ Investment Grade (IG) corporate bonds, 1-10yr IG corporate bonds, and US high yield corporate credit (i.e. junk bonds).

For example, on a standalone basis, US high-yield credit delivered identical returns to long duration US Treasuries, but the latter provided a much higher marginal total return contribution to a balanced portfolio.

Table 2: 50/50 Balanced Portfolio, Quarterly Rebalancing, 1983-2020
Sources: Bloomberg, BetaShares Capital

Why does a rebalancing risk premium exist, and who ‘pays’ it?

There is a common belief that what matters for diversification benefits is simply correlation. This, however, is an incomplete explanation. Correlation can assist with volatility suppression, but rebalancing benefits arise from a combination of correlation, volatility (covariance), absolute return dispersion, and mean reversion in relative returns.

One interpretation is the rebalancing premium can be seen as compensation for mean-reverting rebalancing rules, which on their own expose the investor to risk of unlimited underperformance relative to not rebalancing at all (such as being on the wrong side in a heavily trending market).

The other interpretation is the rebalancing premium is compensation for providing liquidity on demand (i.e. automatically buying stocks/selling bonds during equity drawdowns) and using liquidity when the market is supplying it (selling stocks/buying bonds during a strong equity rally).

This begs the question: who is taking the other side and therefore ‘paying’ the premium to balanced portfolios?

Observation would suggest it is the type of investor who benefits from an environment of trend, momentum and growing return dispersion between asset classes (i.e. leveraged, trend and momentum based strategies). Leveraged strategies benefit from getting a magnified exposure to higher risk premium assets, but the cost is the risk of losses exceeding capital.

In order to insure against the risk of a complete wipe-out, rules around leveraged ratios are typically employed, such as periodic rebalancing to a leverage target or threshold levels. However, this insurance in the form of rebalance rules comes at a cost, with the benefits accruing to unlevered multi-asset strategies.

In one way or another, all types of leveraged strategies, whether they are leveraged ETFs, trend-following strategies, active managers taking positions against a benchmark, or discretionary retail investors trading in margin or CFD accounts, are all subject to Loan-to-Value (LVR) rules that limit downside losses, and this rules-based insurance comes at a cost. This is the whole ‘cutting losses early and letting winners run’ mantra embedded into LVR-based rules.

In conclusion, rebalancing a multi-asset portfolio takes on increased importance, not just from a volatility mitigation perspective, but as a source of risk premium that can be captured through the systematic and counter-cyclical nature of the rebalancing process.


Chamath de Silva is a Senior Portfolio Manager at BetaShares, a sponsor of Firstlinks. This article contains general information only and does not take into account any person’s objectives, financial situation or needs. It is not a recommendation to make any investment or adopt any investment strategy. Before making an investment decision you should consider the relevant product disclosure statement ('PDS'), your circumstances and obtain financial advice. See the BetaShares website (www.betashares.com.au).

For more articles and papers from BetaShares, please click here.


  •   24 November 2021
  • 3
  •      
  •   
3 Comments
Howard
November 24, 2021

I am not a financial analyst but I had assumed that portfolio rebalancing isn't rocket science so surely it could be explained without using jargon such as a mean variance-optimisation engines. 

Graham Hand
November 24, 2021

Thanks, Howard, yes, agree this is a technical piece and we acknowledge it is not an easy read. Rebalancing is a topic many institutions devote a lot of time to so we decided to run it knowing it would be tough for many readers.

Yahya Abdal-Aziz
November 27, 2021

The most illuminating part of the article comes under the heading: "Why does a rebalancing risk premium exist, and who ‘pays’ it?" and I thank the author, de Silva, for tackling it head on. Mind you, the explanation is a little opaque for most of us!

When presented with the notion of rebalancing their portfolio, an investor may well be tempted to ask (as I did for a long time): "Why should I forgo further growth in my investments that are winning, and why should I use the profits I take to buy more of those that are losing?" Or, as de Silva writes: "mean-reverting rebalancing rules ... expose the investor to risk of unlimited underperformance relative to not rebalancing at all (such as being on the wrong side in a heavily trending market)." His answer, clearly, is that there is a premium - the so-called "rebalancing [risk] premium" - paid by (a section of) the market to those that do rebalance, and thereby run that risk - of underperformance, on his first interpretation.

However, I don't grasp the liquidity interpretation; where's the risk in that?


Leave a Comment:

RELATED ARTICLES

The new capital gains tax trap for your portfolio

Solving the Australian equities conundrum

With markets near record highs, here's what you should do with your portfolio

banner

Most viewed in recent weeks

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

Latest Updates

Fixed interest

Higher yields are creating opportunities in global bonds

Bond markets are adjusting to a new reality, but not in the ways investors expect. With markets repricing and capital competing for attention, investors may need to rethink where resilience and opportunity lie. 

Economy

Are we in a recession?

What if the warning signs are already everywhere? From supermarket aisles to company failures, investors are being bombarded with recession signals. But most face a different risk that can be just as dangerous for portfolios. 

SMSF strategies

Meg on SMSFs - Division 296 actuarial certificates

The tax bill might be yours, but the event that caused it may not be. A key Division 296 calculation can sometimes attribute earnings in ways that many SMSF trustees won't instinctively expect or fully appreciate.

Property

The first impact of negative gearing reform is not the tax bill

Negative gearing changes formally begin in 2027, but the first consequences may already be here. A subtle shift is quietly influencing who can borrow, how much they can access and which property strategies still stack up.

Economy

The oil market is running out of easy answers

The biggest threat to markets may not be what investors are watching. The numbers have stopped adding up and supply is harder to measure, with forecasts becoming simple guesses. A more fragile reality is being masked.

Investment strategies

The state of investor knowledge in Australia

Australians are investing more than ever, yet a surprising divide is emerging between those building wealth effectively and those making costly mistakes. Surprisingly, the gap has little to do with income, age or starting capital.

Taxation

Complexity and capital gains

A case study shows that the ‘30% minimum CGT’ is a poorly conceived tax that adds significant complexity to an already over-complex system. A less complicated model would create a much fairer progressive tax scale.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.