Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 547

UniSuper's CIO on why the market rally could continue

Editor’s note: This is an edited transcript of UniSuper’s latest investment update with CIO, John Pearce, in which he discusses what’s behind the recent market rally, and whether it's on solid ground. The full video and transcript can be viewed here.

---

In non-technical terms, the market has been ripping. Since the lows in October last year, the Aussie market's up about 14% and the US market is up about 18%. Why? Well, before I dive into the answer, I’d like to show you this graph. I'm sure some of you will remember as I presented it in November last year - it shows the performance of the Australian stock market over the course of 2023, and the graph depicts the rollercoaster ride that the market found itself on. And I said Mr. Market was in his usual mood swings and there were four distinct phases. We got off to a very good start for the year when the mood was very positive with the prospect of immaculate disinflation.

Then of course, we had the regional bank crisis in the US. You remember Silicon Valley Bank. Then, we had the market being gripped by euphoria around artificial intelligence (AI). And then Mr. Market got into a bit of a swoon because the bond market crashed.

Let's roll the clock forward to 31 January this year, and what do we see? Another sharp rally. 

Figure 1: The ‘rollercoaster’ performance of the Australian stock market over the course of 2023
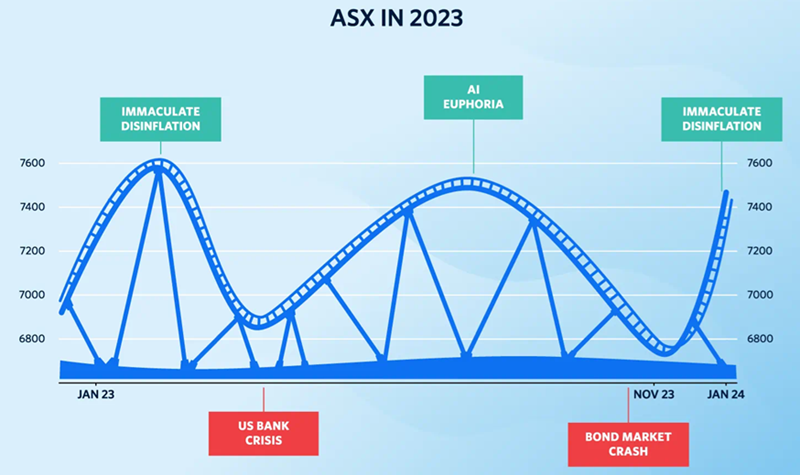
Once again, I put it down to the prospect of immaculate disinflation.

Is this justifiable? Well, firstly, let's define exactly what immaculate disinflation is. Disinflation is simply a fall in the rate of inflation, and the market is pretty confident that we're going to trend towards that magical 2.5%, 3% level that central banks are typically targeting. What's immaculate about this? It's all going to happen without having to crash the economy.

Central banks are not having to tighten to the point where we're forcing the economies into a recession. If you think about this combination, strong economies, low inflation - that is utopia for company profits and share prices.

Is the market rally justified?

So let's get back to that question: is the market rally on solid ground or are we experiencing just another bout of irrational exuberance?

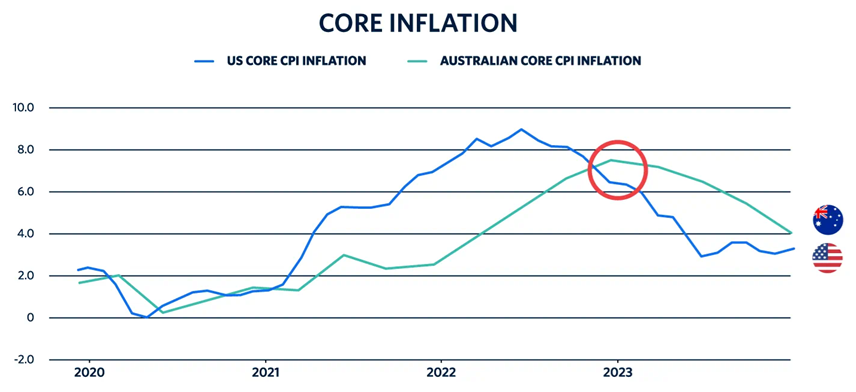
Market commentators love being pessimistic and negative about things, but let me give you three reasons why I think the market could indeed be on solid ground. Firstly, the concept of disinflation is real. Take a look at this graph showing core inflation in both Australia and the US. It's all heading down. Contrast where we are today to where we were in January last year when we experienced this bout of euphoria. Inflation in the US was around 6.5%, it's now closer to 3% - inflation in Australia was around 7.6%, it's now getting closer to 4%, so all very much heading in the right direction.

Figure 3: Core inflation in Australia and the US from 2020 to 2024
Point number two, and this is really important - the Federal Reserve, the most important central bank in the world, really important for other developed countries as well - look at the pivot that the central bank in the US has undertaken.

And to give you an idea of the speed of the so-called Fed pivot, I'd like to refer to the comments made by Jerome Powell, the all-important chair of the Fed Reserve. It was not that long ago, in November of last year, that the chair was basically saying, “Hey, we're still going with these rate hikes- watch out, market”. Then in December, “Hmm, we believe that is room for a pause”. Then in January, two months after November, he's basically saying, “There are grounds for rate cuts this year, but March is probably too early”. Wow. That's a hell of a pivot in a very short period of time. I would have ruled out any possibility of rate cuts if you asked me in November last year.

So they’re three reasons why the market could indeed be on solid footing.

Risks for the market

Of course, what could go wrong? And once again, there's no shortage of risk factors that people will allude to. Let me talk about the three most common risks that commentators like to talk about.

First, geopolitical conflict. Now, I've been around long enough to beware of fund managers parading as geopolitical experts, and what I can say in my four decades or so of working in markets, I can't recall a time when the world was totally at peace, when there was no conflict, and frankly, I don't see much difference today. And what's more, when there is an outbreak of hostilities, historically, it tends to be a good buying opportunity. Second, the prospect of a hard landing. Now we can have an exogenous shock such as a pandemic, we can't stop that from happening. But hard landings are typically driven by policy, and given the current posturing of central banks, I don't think a hard landing is a high probability.

The one that I am concerned about is the possibility of reacceleration of inflation. So the market at the moment is saying that inflation indeed will trend down to that 2.5%, 2% mark and we're going to get rate cuts.

And if we don't get that, well, the market could get into a bit of a tailspin. I'm not so sure. Firstly, I'm not sure what's so magical about a 2% inflation rate versus a 3% or 3.5% inflation rate. Also, I don't believe that we necessarily need rate cuts to sustain the current market rally. However, it does change if we get a reacceleration in the rate of inflation.

Could that happen? It could, but I won't be blaming central banks if it does, I'll be blaming governments. To me, economies are really strong at the moment. Governments around the world should be printing large surpluses. They are not - many governments are still printing large deficits. It's imprudent, and I hope that they will become more prudent. What about the prospect of a Trump victory? Well, the election happens in November, there's plenty of time before then so we'll leave that for another day.

As we sit today, if you ask me what do I think about the current state of the economic and financial world, I say it feels about normal and that's not a bad place to be. 


John Pearce is Chief Investment Officer at UniSuper, a sponsor of Firstlinks. This article provides general information and may include general advice. It doesn’t take into account your financial situation, needs or objectives. Consider your situation before making financial decisions, because we haven’t, as well as the PDS and TMD relevant to you at unisuper.com.au/pds, and whether to consult a qualified financial adviser. Past performance isn’t an indicator of future performance.

For more articles and papers from UniSuper, click here.


  •   14 February 2024
  • 6
  •      
  •   
6 Comments
Dudley
February 15, 2024

"what's so magical about a 2% inflation rate versus a 3% or 3.5% inflation rate":

Taxation of Imaginary Gains that are Un-Real.

Nominal Return 10%, Inflation 'Return' 3.5%, Nominal Tax Rate 47%:

Real return before tax;
= (1 + (1 - 0%) * 10%) / (1 + 3.5%) - 1
= 6.2802%

Nominal Tax;
= 47% * 10%
= 4.7000%

Real Tax Rate;
= 4.7000% / 6.2802%
= 74.838%

Try with 6% inflation:
Real Tax Rate;
= 4.7000% / 3.7736%
= 124.550%

That's what is so magical about inflation. Negative after tax return.

Philip - Perth
February 15, 2024

You've answered the wrong question... Why is inflation rate of 2% better/more magical than 3%? It's not...because it may herald not just disinflation but deflation - an enemy at least as bad as inflation. That's why a rate of 2-3% is acceptable, but below 2% can be dangerous.

Dudley
February 15, 2024

"not just disinflation but deflation - an enemy at least as bad as inflation":

Deflation is much preferable to inflation.

Same goods cost less cash and no Un-Real tax where interest rate is 0% or less.

Jeff O
February 15, 2024

the marginal tax rate of the marginal investor is not 47%...only rich Aussies

well managed multi asset funds should have met their expected return - CPI+ objectives over past 5 years but not the past couple of years

You miss Pearce's major point....global growth is being sustained a bit below potential, inflation a bit above target, real rates are arguable a bit high and risks a bit to the downside...that's pretty normal ....and the perma bears - short global equities and long bonds - have underperformed over past couple of years

Bob Burford
February 19, 2024

Deflation is one we never want to see, if the consumer stops buying because it will be cheaper in 6 to 12 months' time, the World stops manufacturing goods. Millions of jobs are lost and then it's a depression. The 2 to 3% inflation target has been well thought out.

Dudley
February 19, 2024

"if the consumer stops buying because it will be cheaper in 6 to 12 months' time":

Give them time to consider the value and utility of potential purchases while saving and being paid interest savings and avoiding debt.

"Millions of jobs are lost and then it's a depression.":

Leaves plenty of time to till a garden, take nice walks and chat.

"The 2 to 3% inflation target has been well thought out.":

It provides governments with Un-Real taxes plucked from the tax payer goose that results in minimal hissing.


Leave a Comment:

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Will investors be better or worse off under new housing tax changes?

Housing tax reforms have sparked warnings of market turmoil and promises of greater fairness. But after modelling nearly two decades of property data, the results suggest winners and losers may not be who many investors expect.

Latest Updates

SMSF strategies

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

Planning

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Exchange traded products

The hidden trade-off in fixed income ETFs

Some investment trade-offs are immediately visible. Others are embedded in the way a portfolio is constructed. Understanding the difference may explain why similar-looking investments can produce surprisingly different results.

Retirement

The mortgage free retirement is fading

What happens when a generation reaches retirement carrying obligations previous generations largely avoided? New research suggests we may need to rethink both how much we need in retirement and what life could look like.

Retirement

The key question to inspire a confident and purposeful retirement

Most people spend decades planning for retirement. Far fewer plan for what happens when they get there. The difference may explain why so many find the transition harder and less fulfilling than expected, despite careful preparation.

Latest from Morningstar

Making the case for a 'good enough' portfolio

Some investors spend years chasing the perfect strategy. Others choose a path that’s simply good enough and move on. Which approach is more likely to deliver both better outcomes and a happier financial life over the long run?

Investment strategies

Is the US market as expensive as CAPE says?

Many investing ideas survive for decades. But that does not make them right. A famous valuation measure implies that US shares are dangerously expensive, but the evidence may point to a very different conclusion.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.