Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 386

7-point checklist for managing the uncertain timing of death

It has been said that the only certainties in life are death and taxes. I’ll leave it to the accountants to discuss how taxes can be managed, but there is another problem with the uncertainty of death. No-one actually knows when it will happen. The problem with many financial plans is that they implicitly assume a particular age of death as if it is known in advance. There are several problems in this approach.

Average life expectancy is a poor measure

Consider ‘Helen’ who recently turned 66. Her life expectancy is currently another 24 years to age 90. This doesn’t mean that she will live to exactly age 90 or even close to that age. Around two-thirds of females her age will live to somewhere between 81 and approaching 99. In fact, there is only about a 5% chance that Helen’s or any particular 66-year-old female’s life will end in the year starting on her 90th birthday.

Life expectancy is a case where the average is a very weak predictor of individual (as opposed to group) outcomes.

The Actuaries Institute recently recommended that life expectancy results be shown in a way that includes the range of probable lifespans. So, what everyone should be thinking, and advisers should be saying to 66-year-old females, is vastly different from ‘your life expectancy is 90…’

A plan that only lasts up to the average life expectancy will disappoint every second retiree.

Exploring the distribution of actual lifespans

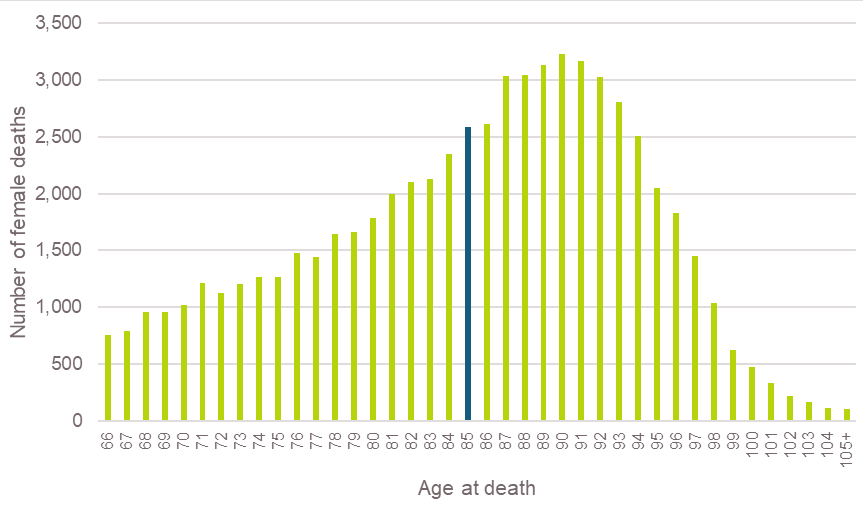
The distribution of actual lifespans can be seen in Figure 1 below, which shows the age of death for older Australians in 2018. The data in the chart are historical (i.e. the peak of the histogram reflects people who were 66 back in 1994) and don’t capture the mortality trend for younger retirees but are still indicative. The highest point (at age 90) still represents less than 5% of over-66s, while the weighted average was only 85.

Figure 1: Actual age of death for Australian females aged over 66, 2018
Source: ABS Cat 3302.0

The charts shows how unhelpful life expectancy figures are in predicting an individual lifespan. Predictions of life expectancies bely a broad range of actual outcomes. With at best a 5% success rate, a plan that relies on a certain age at death, even if it is the correct life expectancy, has an almost immaterial chance of success. The projected lifespan will either be too short and leave a retiree to live only on the age pension or it will be too long and leave a lot of unspent wealth.

Another takeaway on the difference between actual lifespans and predicted life expectancies is that the most common age of death (or statistical mode) in 2018 was 90 for females. If the life expectancies being used in financial planning tools aren’t at least as high as this, then there is an assumption that life expectancies will go down. This would potentially let down retirees and for advisers, nearly all of their clients.

The potential issues are even larger for an advice practice with say 1,000 retired clients. The distribution of their lifespans would look a lot like the chart above. For smaller shops, with only four of five advisers, the client mix might not match the pattern exactly, but it will still be close. The key point is that many clients will need a plan that extends beyond average life expectancy.

Life expectancy of couples

A significant majority (nearly 70%) of people enter retirement as a couple, and the life expectancy of a couple is actually greater than their individual life expectancies. This is because a couple is a pool of two people, rather than one. This increases the risk that one of them will live longer than their combined individual life expectancies. This needs to be factored into retirement income planning.

Wealthier people live longer

There is a well-known link between wealth and life expectancy. People with more wealth tend to have better health and live longer. Accurium studied the mortality of SMSF trustees. They found that SMSF trustees (aged between 55 and 75 in their study) were materially less likely to die than the rest of the population. This means that their life expectancy is longer than the average population.

Even the average client of a financial adviser is likely to be wealthier, and possibly better educated than the average person. As a result, they will also have a higher life expectancy than average. For an adviser, there is a ‘selection bias’ in that the people with enough wealth to seek financial advice are likely to be people who live longer than average.

Understanding longevity uncertainty

The uncertainty around life expectancy is significant. Most investors are aware that equity markets can be volatile. What they probably don’t realise is that the variation around life expectancy is about the same as 10-year equity market returns. For a retiree, the uncertainty around how long they will live is as big as the uncertainty around average real Australian equity returns over successive 10-year periods from 1900 to 1910 and so on through to 2010 (based on Morningstar data).

A longevity checklist 

There are a lot of issues for the average retiree to understand. For both retirees and advisers, it is important that longevity risks are understood. The following checklist could help in that process:

  1. Use up-to-date life tables - currently 2015-17 at aga.gov.au
  2. Use an appropriate mortality improvement table – 25-year improvements (explained in 2015-17 life tables) which are the ‘most optimistic’ and hence safest to use
  3. Never use a ‘from birth’ life expectancy. They are not relevant to retirees
  4. Build in a margin of error – 50% of people will live longer than average life expectancies 
  5. Use a range when thinking about how long you might live
  6. Remember the gender differences and plan for them
  7. Remember the ‘joint lives’ issue – the age of the second death is potentially longer than each single life expectancy.


Aaron Minney is Head of Retirement Income Research at Challenger Limited. This article is for general educational purposes and does not consider the specific circumstances of any individual.


  •   2 December 2020
  • 7
  •      
  •   
7 Comments
George
December 03, 2020

Yes indeed, and if only I knew when was going to die, I could also ensure I left no money in super for my non-dependent children to pay 17% tax. Who said Australia does not have an inheritance tax?!

David Wearne
March 31, 2021

Easy legal Tax dodge!
Life support machines can save this tax. Just have the kids ensure you are kept alive until your remaining super is withdrawn then turn you off.

David Williams
December 03, 2020

This is a valuable summary of the conventional view of life expectancy. Actuaries do a great job of analysing the past and projecting the future of cohorts based on supportable assumptions. But as the article disclaimer says ‘it does not consider the specific circumstances of individuals’. Now we can.
We become more different from each other with age. The challenge of understanding this been very widely and professionally researched. We already know a great deal about personal longevity, why it is continuing to increase (except in the very old), why this may or may not continue and how to respond should issues arise. We more clearly understand the stages of later life.
We can use this information to inform individuals about their potential for much longer, healthier and productive lives than expected when they were born – their longevity bonus. Today those aged 65 have almost reached their life expectancy at birth. More than half of them are likely to live another 20 years or more, most of it in good to reasonable health. Even the final (dependent, not necessarily frail) stage is likely to be much better than today.
As well as informing and empowering potential beneficiaries of this bonus, we need to prepare those who may be less fortunate. We can already support individuals with current personal longevity information and quality of life management processes which go well beyond health issues. As research continues, the quality of this support will continue to improve.
It’s time for financial advice to fully embrace what is known about longevity and incorporate it into a more holistic (and optimistic) approach to advising each client on managing and making the best of the rest of their life.

Jeremy Cooper
December 04, 2020

George, looked at another way, at 17%, you're giving back about half the tax concessions you got in building up your super in the first place.

Jeff
December 05, 2020

Also critical is a tailored personal family health plan - testing & tracking, treating & rehab, recovery etc - I’d argue more important than financial advice - for your longevity and wellbeing

George Wilson
December 09, 2020

What this doesn't take into account is how ageing people will look upon their increasing health problems, worrying about getting dementia and spending years in aged care. Aged care will create an increasing cost for the ageing, with already public discussions about using family home in assets assessment. With euthanasia in Victoria now being accessible to certain groups, I anticipate euthanasia changes will go similarly to the abortion changes in the 70's. Initially abortion was only legal is the woman's life was in danger, then gradually loosened up to abortion on demand.
I expect euthanasia will become on demand in the next 10 years, and people will start to choose this as an option, perhaps as their money is declining or early dementia begins.

b0b555
December 10, 2020

Good to see the Australian Government Actuary isn't spending all its funding on web site design.


Leave a Comment:

RELATED ARTICLES

Will you run out of money in retirement?

How not to run out of money in retirement

How long will you live?

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Latest Updates

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Latest from Morningstar

Does an American retirement rule work for Australians?

The 4% rule has survived decades of scrutiny, but Australia's retirement system changes the equation in ways most overlook. Before accepting or rejecting this rule of thumb, it pays to understand what really drives retirement outcomes.

Shares

Glencore lands on the ASX. Should BHP and Rio shareholders switch?

A coal-heavy miner with governance concerns isn't the obvious choice for investors. Yet, Glencore's ASX listing may offer something BHP and Rio can't. The challenge is working out whether the opportunity outweighs the risks.

Why does the system treat capital gains and losses differently?

Investors are often told not to let tax policy drive their investment decisions. Yet, under the new CGT rules, portfolio construction, volatility and even how assets are owned may have an outsized impact on their final outcome.

Economy

Three common sense reforms that Australia needs

What do frozen bank accounts, mortgage traps and pension penalties have in common? They're all symptoms of a system that makes life much harder. Yet the obvious solutions seem to have escaped the attention of Canberra.

Shares

The hidden cost of government debt for investors

Some of the important effects of rising public debt never make the headlines. Research shows the immediate effects may already be unfolding, influencing corporate behaviour in ways that many investors would never suspect.

Investment strategies

When do fundamentals matter?

Is fundamental investing losing its grip on markets? Investors continue to search for valuation-based explanations for every price move, but the dominant force behind short-term returns may be something else altogether.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.