Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 156

Rules can change, but the final score still matters most

Amid the furore over the potential changes to superannuation rules, investors should not turn away from the continuing taxation benefits. Super is still the best place to save for retirement for the majority of people.

I am reminded of events during the GFC. It was as if some investors had a view on how the game should be played, rather than how it will be played. There is no point sulking over the rights and wrongs of retrospectivity, but rather, focus on the remaining advantages.

As the GFC was unfolding, some bearish friends seemed certain the whole financial system would collapse and probably never fully recover, especially after the fall of Lehman Brothers. The problem in their case was that more than anything, they wanted the system to collapse because it deserved to collapse.

Their only question was timing. Inevitably, I’d pipe up, “But don’t you think governments might take some action to prevent the complete destruction of the global economy?”, to which the reply was usually, “Investors should have known the risks and they will have to pay the costs.”

(My preference was that the destructive impact of the GFC should have been more widespread. The buying opportunities would have been even better and the lessons imparted would have been better learned. It would have been a lot longer before they were repeated.)

However, the job of an investor is to discount probabilities. The likelihood that the governments of the major economies of the world standing idly by seemed fanciful, so I steadily deployed capital into the ongoing destruction of the markets. I finally ran out of available funds in February 2009, which was only a month before the market eventually bottomed.

Understanding the rules

It is critical to operate within the rules of the system to achieve the best results, even if you don’t agree with the rules. For example, you may think that negative gearing is a foolish system that causes more harm than good and distorts the market. But while the system exists, if you intend to own investment property, you need to understand the system and structure your financial affairs to create the greatest long-term benefit. As Kerry Packer famously said, “Of course I am minimising my tax - if anybody in this country doesn't minimise their tax they want their heads read”. If the rules on negative gearing change and the benefits disappear, then you must find the most advantageous setup available under the new regime.

Another under-exploited opportunity is when couples find themselves in different tax brackets. Investment earnings should be in the lower-earning spouse’s name, and opportunities such as superannuation spouse contributions’ should be thoroughly investigated.

Superannuation remains a place where people can exploit the rules of the game, provided there is a willingness to lock precious capital away and notwithstanding the ever-changing rules of the system.

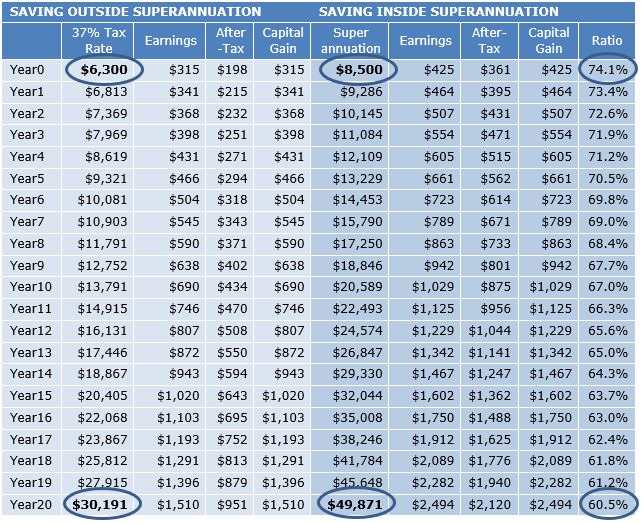
Consider the taxpayer in the 37% tax bracket who expects to be in that bracket for the rest of their working life and then retire in 20 years’ time. The table below shows the different path of $10,000 saved inside and outside of superannuation. For simplicity, the investor will make 10% per annum, equal parts earnings and capital growth with the after-tax earnings reinvested.

The capital saved out of ordinary income begins life as $6,300 (after paying 37% tax on $10,000 income). The capital contributed pre-tax to superannuation begins its life as $8,500 (after paying the 15% contributions tax). The immediate disadvantage of ordinary savings leaves the saver with only 74.1 cents ($6300/$8,500) for every superannuation dollar.

The pernicious effect of the higher tax rate widens the advantage by roughly 0.7c per dollar every year, culminating in the amount saved out of ordinary earnings being worth only 60.5% of the same amount saved behind the shield of superannuation. That is, in this 20-year example with the same earnings rate, the investor has $30,191 when saving outside super while they have $49,871 inside super, making the non-super investment only 60% of the super balance.
The Government still wants people to fund their own retirement

If you are nervous about potential changes to the superannuation system, remember that the Government wants you to fund your own retirement. They may poke around to extract additional tax revenues from the enormous superannuation savings pool, but it remains the place where the average saver is likely to generate the best return on an after-tax basis.

Know the rules of the game and exploit them to your greatest advantage.


Tony Hansen is Chief Investment Officer at Eternal Growth Partners. This article is for general educational purposes and does not address the investment needs of any individual.


  •   19 May 2016
  • 2
  •      
  •   
2 Comments
Ramani
May 20, 2016

Tony Hansen

While most of us saw GFC as the inevitable culmination of asinine asset liability mismatch, securitisation taken to a fine art form without substance, intermediaries placing themselves ahead of consumers and investors, auditors colluding with managers in falsifying valuations and the mythical belief that Governments can never fail, you appear to divine - decades later - missed opportunities.

The rest of us lack the blinding hindsight you have retrospectively been endowed with. The next Nobel prize in medicine (ophthalmology) is surely in the post...

Sure you are not working behind the scenes to provide more opportunities via GFC Mark- 2?

Despite all this, your conclusion that super is the best long term savings vehicle for most is fair. In this case, the end justifies the means, and we will overlook your medical escapades.

Tony Hansen
May 20, 2016

I certainly am doing nothing that I'm aware of to expedite the next GFC. I abhor and avoid leverage, and so avoid it entirely. I am likewise leery of most other forms of complex financing.

Believe me when I say that it was with a cautious hand and no sense of where we would be seven years hence when I was deploying my life-savings into the wreckage wrought by the GFC.

All I was attempting to do was to assess the risk/reward and make what appeared to be the economic choice that would provide the greatest benefit for my family.

I was very fortunate, that like every other major midnight in the history of capitalism, a new dawn eventually came.

It is that self-same assessment of risk/reward I encourage others to employ by stacking the tax system in their favour in utilising the superannuation system to the greatest extent they can.


Leave a Comment:

RELATED ARTICLES

Superannuation and retirement policies

There's a reason why your super is locked up until your 60s

Will you run out of money in retirement?

banner

Most viewed in recent weeks

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

Testamentary trusts have secured the CGT exemption

Treasury’s latest CGT reform draft delivers a win for testamentary trusts and deceased estates, exempting estate-derived gains from the 30% floor. However, questions on death and divorce rollovers remain unresolved.

Meg on SMSFs: What do we think about reversionary pensions these days?

Reversionary pensions have long been a staple of SMSF estate planning, but are they still the best option? Meg Heffron revisits a once-clear favourite and asks whether changing super rules have shifted the balance.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

How does the 4% rule stack up?

The 4% rule has long been retirement's gold standard. But after a difficult period for investors, fresh analysis suggests a more conservative approach may significantly improve the chances of making savings last.

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

Latest Updates

Planning

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

Superannuation

There's a reason why your super is locked up until your 60s

For decades, it seemed settled. Then one controversial idea reignited a debate that could reshape the financial future of millions. The real question isn’t who’s right or wrong, but whether a long-held assumption deserves another look.

Property

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Retirement

Under-retiring: The greatest retirement risk in a generation

Two retirees. Similar savings. Completely different lives. New research from Challenger reveals why some Australians confidently spend in retirement while others hold back and the overlooked factor shaping retirement decisions.

Five risks to watch in markets

Things you may often hear are: a recession is around the corner, markets are overpriced, the AI sector is about to flop at any moment. It’s like the never-ending laundry pile that sits in my house, it never really disappears.

Investment strategies

Do you qualify as ‘rich’?

What does it mean to be 'rich'? For something so universally desired, it is surprisingly difficult to define. That ambiguity creates a challenge for investors and raises a bigger question about what financial success really looks like.

Investment strategies

If you’re worried about your bond portfolio, you’re missing the point

Most investors think they know what bonds are for. But when markets turn volatile, a surprising misunderstanding can lead to costly decisions. Here’s the overlooked lesson that could change how you view your portfolio.

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.