Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 565

The new retirement challenges facing Australians

[Vanguard has released its second annual report called 'How Australia Retires'. It surveyed more than 1,800 people about our attitudes towards retirement and how we feel about this phase of life. Here is an extract from the report.]

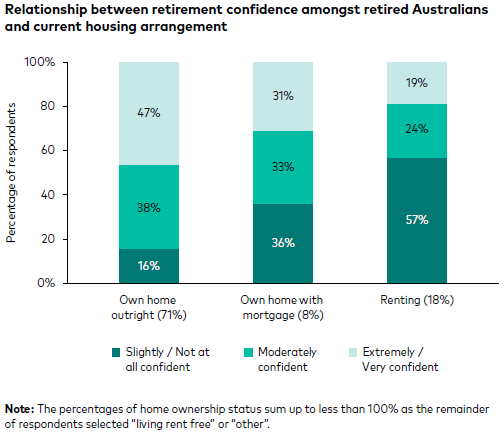
Housing, and whether or not it is owned outright, was found to have a material impact on a retiree’s retirement confidence level. Of the 18% of retired Australians who are renting their home, more than half (57%) said they were slightly or not at all confident in their ability to fund their retirement. This contrasts with the 71% of retired Australians who owned their home outright, of whom only 16% said they were slightly or not at all confident, suggesting renters are more than 3 times as likely to be of relatively low retirement confidence than those who own their home outright.

Only 8% of retired Australians owned a home but still had a mortgage to pay. Of these retirees, retirement confidence was lower than for those who owned a home outright, but higher than for those who rent.
Role of housing in retirement

Australians have long harboured a strong affinity for property, with 72% of Australians believing that home ownership is a very important factor that contributes to retirement readiness. In 2019-20, the family home was the largest asset held by Australians households, making up 37% of net household wealth, ahead of superannuation at 22% 1.

Home ownership not only contributes to wellbeing in the form of shelter and security, but it is also a key factor in determining retirement outcomes as housing costs such as rent and mortgages impact retirement wealth. The rate of home ownership however is changing, with particular decline amongst Millennials aged 25 to 39 years old 2.

Australians have a strong emotional attachment to the family home; only 1 in 7 Australians see the home mainly as a source of retirement funding.

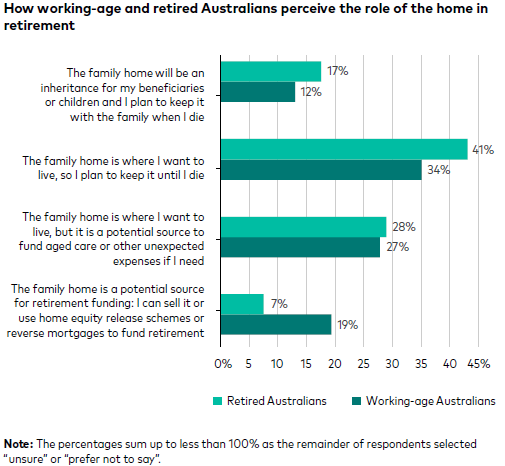
Most Australians believe the family home is where they will age. 34% of working-age Australians and 41% of retirees are most aligned with the statement that “the family home is where I want to live, so I plan to keep it until I die”, showing significant emotional attachment to the family home, and highlighting the unique role of housing in retirement assets.

27% of working-age Australians view their family home as where they want to ultimately live, but also believe it can potentially fund aged care or unexpected expenses if needed. 28% of retired Australians believe the same.

19% of working-age Australians view their family home mainly as a source of funding, willing to sell it or use home equity release schemes or reverse mortgages to fund their retirement. In contrast, only 7% of retired Australians echoed this sentiment.

A lower percentage of working-age Australians (12%) than retired Australians (17%) considered their family home as an inheritance for their beneficiaries or children.
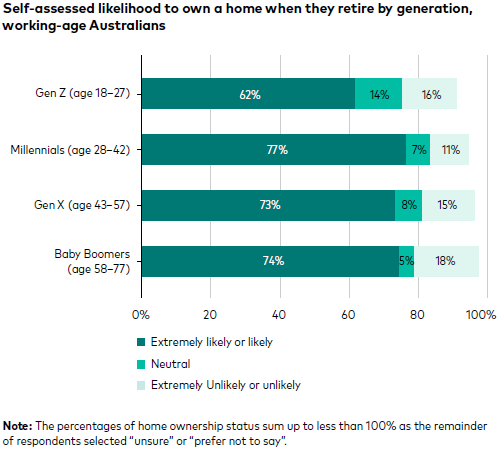
Most working-age Australians find home ownership likely but 30% still expect to pay a mortgage in retirement.

Positively, expectations amongst working-age Australians of home ownership in retirement are generally high amongst all generations. Compared to older generations, however, Gen Z are the least optimistic about their chances of home ownership in retirement (with 62% finding it extremely likely or likely that they will own a home, compared to 77% of Millennials, 74% of Baby Boomers and 73% of Gen X).

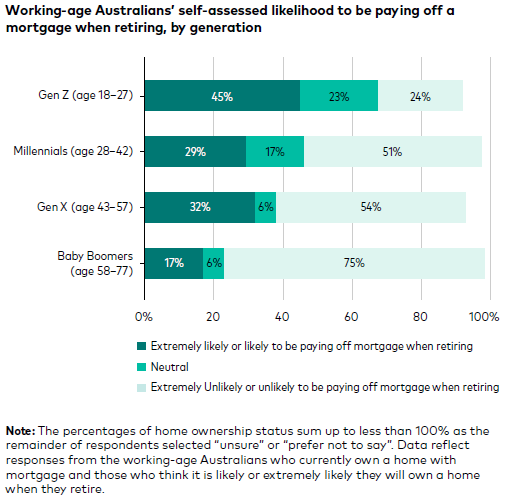
Gen Z is also the generation most likely to believe that they will be paying off a mortgage at retirement, with almost half (45%) of respondents in that generation who expect home ownership citing it is extremely likely or likely that they will still be paying off a loan.

When it comes to Millennials, 29% who either currently own a home or find it likely they will own a home in retirement also believe they will still be paying off their mortgage at retirement.
Perhaps of most concern is 32% of Gen X respondents who currently own a home with a mortgage or expect to own a home in retirement believe it is extremely likely or likely they will still have a mortgage in retirement, despite approaching the traditional age of retirement and therefore likely to have the least amount of time (when compared with other generations) to pay off debts before retiring. When asked about their plan to pay off their mortgage, 38% of these Gen X respondents intend to keep paying their mortgage through retirement and 18% would consider selling their home and using the proceeds to repay their mortgage. 25% of these Gen X respondents have plans to use their superannuation to pay off their mortgage in one transaction.

Working-age Australians who believe they are unlikely or extremely unlikely to own a home when they retire are also more likely to not have a clear plan for retirement (55% vs 33% who expect to own a home in retirement) and are also more likely to be of relatively low retirement confidence (55% vs 23%).
Nearly 1 in 5 retired Australians are renting

Given those who rent in retirement are more likely to exhibit lower retirement confidence than those who own their home outright, a lack of home ownership remains a key issue, considering its impact on retirement savings and financial security.

18% of retired Australians are renting in retirement, and 8% own their home but with a mortgage. The percentage of retirees renting or with a mortgage is significantly higher (31%) for those who are not in a relationship (separated, divorced, widowed or never married) than those with a partner (8%).


Daniel Shrimski is Managing Director of Vanguard Investments Australia, a sponsor of Firstlinks. This article is for general information and does not consider the circumstances of any individual. Additional contributors: Junhao Liu, Ph.D., Timothy Smart, Martha Wood, and Sarah Ge.

For articles and papers from Vanguard, please click here.


1 2023 Intergenerational Report published by the Federal Government Treasury, p169.
2 Australian Bureau of Statistics (20 October 2022), ‘Owning a home has decreased over successive generations’ [media release].


  •   19 June 2024
  • 5
  •      
  •   
5 Comments
Retirement Dr
June 20, 2024

Thanks Daniel. Very informative. Two observations. 1. More evidence again that the ASFA retirement standards need to extend beyond homeowners. 2. 41% of retirees indicating that they want to stay in their homes until they die. Downsizing incentives need to recognise that home is where the heart is (and not just the back pocket). This includes providing suitable accommodation options that facilitate access to valued services and community.

Neil
June 20, 2024

Or put another way, 59% (a majority) realise that the large family home they raised their children in is not appropriate for their frail bodies as they age.

Paul
June 20, 2024

I'm not surprised that the majority of current and future retirees plan to remain in the family home, with an increasing number also seeing the home's utility re equity release and acute age care bond security.

To me, it further highlights and evidences the lukewarm reception and take up of the government's downsizer option. People are not overly enthused at selling up and potentially moving away from their community and familiar community surrounds, to free-up some capital for income or capital needs, but then having all the stresses and costs attached to finding a new home.

I hope the government is reading these sorts of soundings from the community and will in turn encourage product innovation and solution (even via Regulators upping the ante on super trustees via instruments such as the SIS Act's Retirement Income Covenant) to deliver Australians better equity access and drawdown outcomes, that don't require home ownership recycling.

Dudley
June 21, 2024

"When asked about their plan to pay off their mortgage, 38% of these Gen X respondents intend to keep paying their mortgage through retirement" ... "25% of these Gen X respondents have plans to use their superannuation to pay off their mortgage in one transaction.":

... and on the Age Pension as soon as possible.

Real net interest rates are not large enough to make buying a home without a mortgage competitive with buying using a mortgage except for those with large incomes and small home requirements.

Hence the small savings rate and large Debt Mountain and large risk of an uncontrolled collapse.

Anne
June 23, 2024

Like so many surveys, this one makes assumptions.

My mother in law would tick "Stay in my home until I die" - except that her home is not the one she raised her kids in, but the one she and my father in law bought shortly after retirement. She downsized years ago, but this survey doesn't seem to be able to record that fact.


Leave a Comment:

RELATED ARTICLES

Retirement in reality - 7 months in

Retirement in reality - 6 months in

Retiring from work is easy, retiring into life is harder

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Latest Updates

SMSF strategies

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

Planning

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Exchange traded products

The hidden trade-off in fixed income ETFs

Some investment trade-offs are immediately visible. Others are embedded in the way a portfolio is constructed. Understanding the difference may explain why similar-looking investments can produce surprisingly different results.

Retirement

The mortgage free retirement is fading

What happens when a generation reaches retirement carrying obligations previous generations largely avoided? New research suggests we may need to rethink both how much we need in retirement and what life could look like.

Retirement

The key question to inspire a confident and purposeful retirement

Most people spend decades planning for retirement. Far fewer plan for what happens when they get there. The difference may explain why so many find the transition harder and less fulfilling than expected, despite careful preparation.

Latest from Morningstar

Making the case for a 'good enough' portfolio

Some investors spend years chasing the perfect strategy. Others choose a path that’s simply good enough and move on. Which approach is more likely to deliver both better outcomes and a happier financial life over the long run?

Investment strategies

Is the US market as expensive as CAPE says?

Many investing ideas survive for decades. But that does not make them right. A famous valuation measure implies that US shares are dangerously expensive, but the evidence may point to a very different conclusion.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.