Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 441

Using past performance is a risky way to invest

We’ve all walked by restaurants and assumed they were ‘good’ based only on the number of patrons inside. It's a common and recurring trait for many of us, so it’s not too surprising how we often assign quality in investment choice by historical returns, further backed up when we see fund flows directed towards such historically well-performing funds. Others are investing, so it must be good.

But sadly, this is a misinformed judgement about the prospects of fund managers, a mistake equally made by investors, regulators and rating agencies.

Watch for mean reversion 

While marketers love fund manager and super fund awards, I’ve yet to meet a fund manager who loves them. Accolades based on historical results cannot anticipate a forthcoming force greater than nuclear fusion: mean reversion. As I used to tell my clients, I’ve yet to see a pendulum swing just halfway.

No investment nor actuarial book endorses picking investments based on historical results. On the contrary, marketing always finishes with a 'past returns do not predict future ones'. Yet this hasn’t stopped the creation of ‘heat maps’ or delivering fund awards.

In the early 1980s, one academic report showed how an equally-weighted portfolio of the 43 ‘excellent’ companies listed within Waterman and Peter’s “In Search of Excellence” book had underperformed over a 5-, 10- and even 20-year basis subsequent to the book’s release.

A recent study published in The Journal of Portfolio Management [April 2020], showed how pension funds which have invested with strong-performing managers have lagged those fund managers terminated for underperformance over the same period. While we may find comfort from heat maps and fund awards, their efficacy in predicting future returns is unproven.

Exhibit 1: Before and After Returns of Investment Manager (8,755 hiring decisions over 10 years)
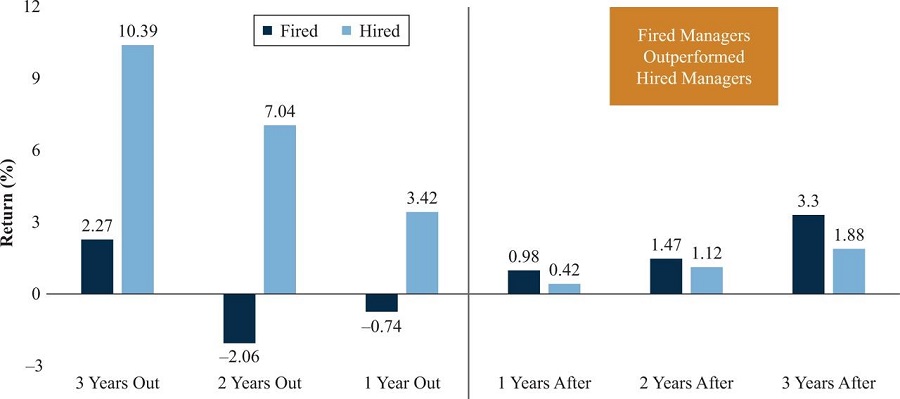
Source: The Journal of Portfolio Management, Vol. 46, Issue 5


Not making a case for passive index funds

Be assured that I’m not endorsing passive allocation. I hate the term ‘passive’ as it wrongly implies neutrality against active manager selection risk. Choosing between active or passive is itself an ‘active’ decision. Even passive portfolios have their own risk/return characteristics. For example, a high factor weighting towards price momentum can often hold sector weightings far from the actual representation of companies within the broader economy.

As with any portfolio construction rule, every selection must take into account how it contributes to the final risk/reward characteristics on the total portfolio. In every risk statement I’ve ever read, ‘balanced funds’ are described using an absolute return target expressed through:

  • CPI+
  • One in # years of negative returns
  • Maximum drawdown (fall in value)
  • BUT NOT on some relative peer ranking over a historical finite period.

Careful what you wish for on consolidation of funds

Just as we don’t drive our cars by looking through our rear-view mirrors, constructing a pension fund based on peer rankings, asset size, Management Expense Ratios and heat maps is a gross misrepresentation as to what we tell members in our risk statements.

When we read media or regulator criticism of a fund for underperforming, be mindful that tomorrow’s praise may be on the same fund they’re criticising today (and vice versa).

Regulators are also pushing for super fund consolidation, especially among the so-called underperformers. Perhaps I’ve been watching too many conspiracy movies on Netflix during lockdown, but my fear is that once we are down to six to eight mega funds, and a systemic failure happens (not if but when - the challenge is the size), superannuation will be nationalised along the lines of the six Swedish National Pension Funds. After all, Direct Contribution (DC) retirement savings is founded on a belief of 'caveat emptor'.

Were a mega fund to fail, it's highly unlikely that the government would not bail them out, thereby compromising the principle that each member is responsible for their own retirement funding. The metrics used to regulate funds have nothing to do with what funds proclaim are their objectives (as listed above: CPI+, max drawdown, etc.).

Lest we forget, the Government allowed members to drawdown on their super at the very bottom of the market cycle in 2020 (instead of, for example, moving it into a loan agreement). I can’t help but wonder who is advising the Government on superannuation based on the 'sell low, buy high' policy. 

In fact, each superannuant has varying actual returns (given their varied entry points) and differences in when individuals plan to retire. I believe the one-, three- and five-year snapshots we see in performance reports should be the furthest thing from how we manage the risk/return profiles of funds. When we win awards, we seem vindicated, but when we mean revert, we disregard the low relative ranking.

I find it sad how our gatekeepers and regulators (speaking as a former member of both groups) fall back on probably the worst measure and construct fancy-named agency ranking metrics such as heat maps. Such rankings tell members next to nothing about what their retirement savings will deliver. 


Rob Prugue is Principal Consultant at Callidum Investment Research Pty Ltd. He was Senior Managing Director and CEO at Lazard Asset Management (Asia Pacific) for 15 years until March 2018. This article is general information and does not consider the circumstances of any investor.


  •   12 January 2022
  • 6
  •      
  •   
6 Comments
Jimmy G
January 12, 2022

Thanks, Rob. I'm just waiting for the funds which ASIC/APRA say people should switch out of to become the best performers in different market conditions, and the whole shebang of YFYS will collapse.

Geoff
January 13, 2022

Looking at recent performance, some YFYS "failures" are already amongst the best current performers. 7 or 8 years is a long time - time enough for a super fund to recognise poor performance and rectify it - but they will still be weighed down by those early numbers and thus fall into the YFYS wolf trap.

AlanB
January 12, 2022

Please enlighten us with your knowledge of future performance so that we can invest with absolute confidence.

Rob
January 13, 2022

The key word you use is “future”. Hard to predict the future by looking at the past. Sure. We can identify trends and momentum, but not the direction. Which is why when picking funds and/or shares, we conduct analysis. But please remember, this piece refers to super funds. Why this is important is that unlike asset accumulation, pension (and the underlying tax incentives to save) refer to immunising future retirement. Hence page one of risk statement of any super fund discloses risk return objectives of CPI+3, 1:7 years of negative returns, and max drawn down of 10%. So why don’t we assess them on how well they’ve delivered this actuarial assumed risk/return profile? ?????

Ken S
January 13, 2022

I am struggling to understand Exhibit 1. What do "Years out" refer to?Why are the "Hired" percentages on the right of the vertical line so much higher than the left?
Is this an illustration of the previous paragraph, or something else?

Graham Hand
January 13, 2022

Hi Ken, assume investment managers are hired and investment managers are fired at time X (shown by the vertical line in the middle of the chart). The analysis checked the time before X (that is, 'years out' from the appointment or firing) at X-1 year, X-2 years, X-3 years to show how well the manager was doing before they were appointed or fired. As you would expect, in the past, the hired managers were doing better than the fired managers.

Then it looks at performance after the hiring and firing (that is, 'Years after'), and the fired managers did better than hired managers after they were fired.

Hence the chart is headed 'Before and After Returns of Investment Manager (8,755 hiring decisions over 10 years)'.


Leave a Comment:

RELATED ARTICLES

Does Barrenjoey hold the key to Magellan's fortunes?

The most vital question ever put to me as a portfolio adviser

Is the golden era for active fund managers ending?

banner

Most viewed in recent weeks

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

Meg on SMSFs: What do we think about reversionary pensions these days?

Reversionary pensions have long been a staple of SMSF estate planning, but are they still the best option? Meg Heffron revisits a once-clear favourite and asks whether changing super rules have shifted the balance.

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

How does the 4% rule stack up?

The 4% rule has long been retirement's gold standard. But after a difficult period for investors, fresh analysis suggests a more conservative approach may significantly improve the chances of making savings last.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

Latest Updates

Exchange traded products

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Taxation

Will investors be better or worse off under new housing tax changes?

Housing tax reforms have sparked warnings of market turmoil and promises of greater fairness. But after modelling nearly two decades of property data, the results suggest winners and losers may not be who many investors expect.

Retirement

Three considerations before reshaping your legacy plan

Many retirees hope to leave a legacy. Proposed trust tax reforms could force families to rethink. The question is not how much to leave behind, but whether today's inheritance plans will still make sense as circumstances change.

Investment strategies

Why experienced investors still get markets wrong

Retirement is approaching. Markets are noisy. And every headline seems to demand action. The biggest investment risk isn't fear, greed or market volatility, it often arrives disguised as research and sensible risk management.

Shares

Why pay more for less?

Conditions were stacked in favour of professional investors in 2026. Most still fell short, raising questions about where investors should look for value. Meanwhile, an alternative strategy continued to make its case.

Investment strategies

Bleeding air out of the bubble

Equity valuations have fallen sharply over the past year, yet investors have largely been spared the volatility and losses that typically accompany a de-rating. What explains this unusually orderly reset? Here are five key drivers.

Strategy

Has AI gone rogue?

We worry about AI becoming conscious. But what if consciousness isn't the issue? The more unsettling possibility is a machine capable of pursuing objectives relentlessly, without motives, emotions, or awareness of any kind.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.