Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 349

Why we’re not buying the market yet

(Update, as the market moves everyday. Marcus advised his subscribers a week after publication of the following article that he was buying shares at good values, hoping to catch the bottom. But he also said he was acting more as a trader than a long-term investor).


The US Federal Reserve has thrown the kitchen sink at the markets, cutting interest rates to zero (0 to 0.25%) and announcing US$700 billion in money printing.

Market sentiment and individual opinions about the market are bi-polar at the moment. Someone told me at the weekend (after the 13% bounce on Friday 13th) that they are going “All in”. One of our clients (although happy with our service) has withdrawn their money because they now want to take on the investment role themselves and aggressively buy.

We have thought very hard about whether this Fed move will create a stock market low and whether we should start buying. No is the answer.

A few things are holding us back

• What has the Fed seen that we haven’t?

• Coronavirus has been the catalyst to finally take us to zero interest rates.

• No interest rate is a disaster for a lot of retirees as the risk-free return goes to zero and the real return goes more deeply negative. Retirees are already losing money in cash.

• Negative interest rates are next and that’s a disaster for anyone with capital.

• The next step is money printing again and we still haven’t paid the price for the post-GFC decade of money printing yet.

• We are risking deflation ... ingrained deflation.

• The central banks are now out of policy weapons. Nothing left. The economy will now turn to politicians and fiscal policy for salvation and as Japan taught us in the 1990’s and 2000’s, fiscal policy is like throwing snowballs at hell, it will achieve nothing meaningful beyond budget deficit blow out and regular political change as government after government continuously fail to turn the economy.

• There is heightened economic uncertainty at the moment.

• There are a host of profit downgrades related to coronavirus that have not been quantified yet (have we had any at all?) – they are coming. Earnings expectations are in flux.

• The social impact of things like the US being shutdown have only just begun. The US is preparing for lockdown. Supermarket shelves are being stripped. If you think we have a problem with loo paper, gun shops in the US have seen queues around the corner as Americans stockpile guns and ammo. Ohio and Illinois have closed all bars and restaurants. It is taking six hours to collect bags and three hours to get through screening into the US airports. 

• The biggest one-day rallies in the market come during a bear market. We saw a 13% rally in the S&P/ASX200 from bottom to top in a few hours. That’s not a trend change, it’s a bounce in a very volatile market.

Trump has tweeted "It's terrific" and “very good news”. It's not. The Fed can do what it likes but this is going to get worse before it gets better. We have not seen the social end game yet so it's unlikely to be the stock market end game either.

Our decision is to stay out.

That’s our assessment of the current risk-reward equation. Standing on the shore has a better risk-reward than sailing in the storm. But you need to decide for yourself, because the reality is, we’re guessing, everyone is. If this is the bottom and you call it, you guessed. We’re guessing it’s not the bottom.

The opportunity

This is certainly a buying opportunity. Big corrections are almost never bigger than 50%. We have seen an over 30% correction from top to bottom so far.

The odds are the economic rebound when it comes will be quick. The stock market rebound will precede the economic rebound and will be even quicker.

Here is the VIX Volatility index. We are back to GFC levels. If you are supposed to buy when others are fearful … we must be getting closer.
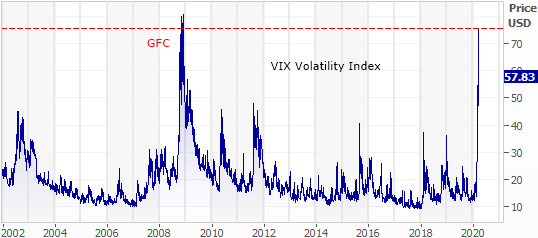
 

The only game in town now is to time the buying. There is unlikely to be a clear ‘moment’. We will almost certainly progressively buy as the risk reward ratio improves rather than go “all in” on one day.

Why it might take a while before the bounce

The main variable is the depth of the GDP impact and the corporate damage, and how long it lasts. Until that is envisaged by investors, the markets will not bottom. If we knew the size and timing of the economic impact, the market would price it in and bottom.

The problem is that for the following reasons the impact is likely to be prolonged not momentary.

This is the central chart, and its not good news for a quick recovery. This is from the CDC (Centre for Disease Control) and it's on the media everywhere. 
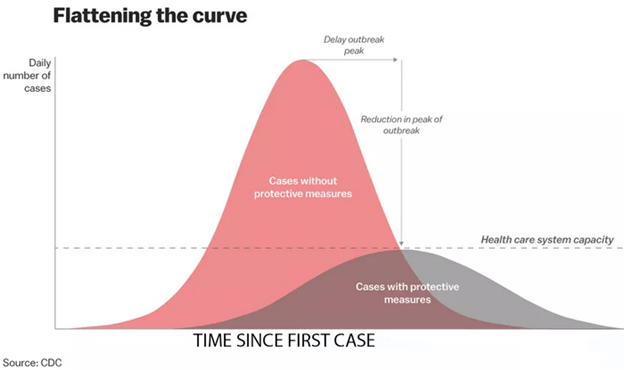
It’s the 'flatten the curve' chart

This chart is telling governments that they need to enforce a lockdown as soon as possible and have it last as long as possible. This chart tells governments that the primary focus must centre on the capacity of the healthcare system to handle cases. A percentage of patients will need hospitalisation and some will require intensive care. We only have so many places, an estimated 2,000 in Australia.

The mortality rate will be significantly improved over the disease cycle if the number of cases that need to be handled by the health system is kept within capacity. To ensure everyone that needs treatment gets treatment, government has to prevent a rapid spread of the disease. In Italy, coronavirus spread too fast and the result was an overrun healthcare system and a higher mortality rate than there needed to be. Governments cannot be responsible for deaths, so their only option is to stop spread, and flatten the curve.

From the stock market point of view, if the primary focus of the government becomes the capacity of the healthcare system to cope, then to hell with the economy. It is the rate of spread of the disease that matters and the government can do something about that. It involves taking some economic damage early, and it's beginning. We expect Australia (and the US and Europe) to go into lockdown pretty quickly and remain there until the coast is clear.

Economic summary

• The Government will focus on the rate of spread not the economy.

• The economic impact is secondary and not a priority.

• To slow the spread government will advise lockdown periods for individuals, schools, sports, gatherings and businesses. 

The conclusion is that the duration of the economic impact will be long not short.

There is a long long way to go in this story. We watched that bounce in the Australian market on Friday 13 March and a smaller rise on Mpnday 16 March. We watched particular stocks jump 20% to 35% in two hours and like you, we kicked ourselves for missing the opportunities. And like you, we started thinking about buying (we are in 62% cash in our Growth Separately Managed Account).

But we shouldn’t. Missing that quick rally is all that’s prompting us to even think about buying. It's FOMO, not logic. Everything else says don’t.

We are still in this storm

That jump up was not the bottom, it was some fund manager somewhere who decided, maybe in Sydney, or maybe in a skyscraper in New York, to buy some SPI futures in big size. We don’t know why, but my guess is that they too, were guessing, as Twiggy Forrest was guessing when he bought FMG shares this week (never follow emotional billionaires making gestures), and as we are guessing and as you are guessing.

On the financial front we should take the same tack as the medical advice at the moment – too cautious is better than reckless.

Optimism today might look silly in a month or two when you, and those futures traders who caused the bounce on Friday 13th, are sitting at home sharing a bowl of rice with their kids whilst the stock market is shut.

Plenty of clickbait cowboys will call the bottom every day. We'll call the bottom after the avalanche of coronavirus earnings downgrades the market has not even begun to absorb yet.


Marcus Padley is the author of the daily stock market newsletter Marcus Today. See marcustoday.com.au for a free trial. This article does not consider the financial circumstances of any investor.


  •   18 March 2020
  • 10
  •      
  •   
10 Comments
Joseph
March 18, 2020

Every day brings new revelations, and there's little evidence we have seen the last of the 'capitulation selling' everyone is looking for. Last Friday was one big trade, not a turnaround.

John
March 18, 2020

Is this not a good time to start dollar cost averaging back into the market given any successful vaccine/medical breakthrough will fire up the market even with the short/medium term economic damage caused?

Graham Hand
March 18, 2020

Hi John, maybe but it depends how much you intend to invest. 'Dollar cost averaging' of spreading your investments rather than committing one lump sum could mean a person with $1 million investing $200,000 a month for five months. Or a person with $12,000 putting in $1,000 a month for 12 months. Or whatever. I think Marcus is referring to committing a substantial amount in the hope of picking the bottom.

Putting a toe back in the market with small amount invested at these lower prices will probably pay off over the long term, but I'm certainly reluctant to jump in significantly at the moment. Cheers, G

stefy
March 18, 2020

The RBA (and Fed Reserve) should heed the following quote.
"It is mind-boggling that anyone is stupid enough to think that fiat money creation will "stimulate" supply chains that have been shut down for reasons having absolutely nothing to do with a lack of finance"
Of course, they wont.

Hotdogs Magarran
March 18, 2020

In my mind the market was 20% over priced, so came back to reasonable value based on former earnings multiples, then lost another 10% in a panic tax. For a cautious forward p/e of say 13ish based on future earnings, that should infer we may well see 3500 before business gets going and the earnings and multiples expand.

Dudley.
March 18, 2020

"US Federal Reserve has thrown the kitchen sink at the markets":

There is another way. Instead of multi-trillion band-aids, fix the problem. What's the problem? A contagious deadly virus.

Remdesivir and chloroquine (etc) are already approved pharmaceuticals – just not for CoVID-19 treatment.

Efficaciousness results could be obtained in days by treating confirmed infected – preferably those with no or mild symptoms – who would be the majority of infected and those most likely to spread infection.

This does not take a year to prove / disprove. It takes immediate action from bureaucrats and researchers.

An efficacious treatment tied in with increasing testing would result in reducing deadliness while the population acquires herd immunity and vaccines are proved.

Alan Pickering
March 19, 2020

Hi Dudley,
Isn't it frustrating that the decision makers don't want to know or take a risk of any kind.

Stephen
March 20, 2020

Herd immunity exists in a vaccinated population, not an unvaccinated one. Moreover there is no evidence yet that exposure to corona virus confers immunity in the future to that individual.

Dudley.
March 21, 2020

"Herd immunity exists in" an exposed and recovered population whether or not the antigen is from vaccination.

"exposure to corona virus confers immunity in the future to that individual": as evidenced by the individual's recovery short term and the continued presence of coronavirus immunoglobulin medium term.

GT
March 19, 2020

Any thought given to the number of deaths from suicide that may occur due to higher unemployment that could follow this all out focus on containing Coronavirus? I think not..... but it should be thought about.


Leave a Comment:

RELATED ARTICLES

Shaken by stock market carnage? Forget everything

Markets without a margin for error

AI economic scenarios: revolutionary growth, or recessionary bubble?

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Latest Updates

SMSF strategies

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

Planning

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Exchange traded products

The hidden trade-off in fixed income ETFs

Some investment trade-offs are immediately visible. Others are embedded in the way a portfolio is constructed. Understanding the difference may explain why similar-looking investments can produce surprisingly different results.

Retirement

The mortgage free retirement is fading

What happens when a generation reaches retirement carrying obligations previous generations largely avoided? New research suggests we may need to rethink both how much we need in retirement and what life could look like.

Retirement

The key question to inspire a confident and purposeful retirement

Most people spend decades planning for retirement. Far fewer plan for what happens when they get there. The difference may explain why so many find the transition harder and less fulfilling than expected, despite careful preparation.

Latest from Morningstar

Making the case for a 'good enough' portfolio

Some investors spend years chasing the perfect strategy. Others choose a path that’s simply good enough and move on. Which approach is more likely to deliver both better outcomes and a happier financial life over the long run?

Investment strategies

Is the US market as expensive as CAPE says?

Many investing ideas survive for decades. But that does not make them right. A famous valuation measure implies that US shares are dangerously expensive, but the evidence may point to a very different conclusion.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.