Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 100

The comprehensive income product for retirement

[Editor's note: The words in Jeremy's heading and their abbreviation, CIPR (pronounced 'sipper'), come from the Financial System Inquiry and they are quickly becoming part of the superannuation industry lexicon. We need another word or abbreviation. Such a clunky set of letters will do nothing to encourage engagement with post-retirement products. Suggestions welcome.]


The retirement income stream market in Australia is unusual by global standards, being dominated by the ‘balanced’ account-based pension (ABP). It has usually been recommended to investors on the basis of underlying investment choice, flexibility, control and liquidity.

As observed by the Financial System Inquiry (FSI) in its final report, and made clear by their impairment during the GFC and in its aftermath, the average ‘balanced’ ABP can’t adequately manage the unique risks of retirement. It should be viewed as part of any retirement portfolio, rather than the entire solution.

So it makes sense that the FSI recommended that all large APRA-regulated super funds ‘pre-select’ a comprehensive income product for retirement (CIPR) that addresses the need for retirees to have:

  • high income
  • risk management features
  • flexibility

The FSI believed that this requirement is likely to be satisfied by using a combination of products, starting with the ABP. This was illustrated in the FSI’s final report as follows:

Desired features of retirement income products
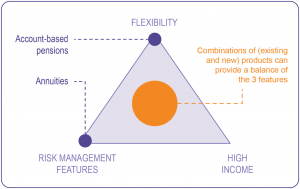
The final report suggested the potential for a wide range of CIPRs which, in addition to the existing ABPs and annuity products, included combinations with:

  • deferred lifetime annuities (a product commonly used overseas, but not yet here)
  • group self-annuitisation schemes (GSAs) (a new concept)
  • deferred GSAs and
  • other future innovations.

Making the comprehensive income product more understandable

One challenge faced by the broad, non-prescriptive CIPR concept is that any product or portfolio will have to be easily understood and evaluated by fund members. To provide guidance, minimise subjectivity and promote more consistency of retiree outcomes, we might wish to consider the use of a balanced scorecard approach. The scorecard would assign a qualitative rating to each strategy or feature addressing the three CIPR requirements.

The scorecard could be developed by APRA using its standards-making power under broad principles that could be set out in the SIS Act. This process would allow for appropriate consultation with the industry. Designing the scorecard would, however, involve making some qualitative decisions about the differences between certain retirement income strategies. For example, a core principle should be that an investment strategy or asset allocation alone does not satisfactorily deal with longevity risk. Higher expected returns should be a positive, but income volatility should lower the rating. Similarly, CIPRs that did not have an express inflation management strategy or a means for combating sequencing risk would also get lower scores under the balanced scorecard idea.

Using a scorecard would enable easy comparison for retiring fund members and their advisers, and provide some regulatory guidance, without reducing the ability of fund trustees to tailor their offer to the specific needs of their own members (eg taking into account different demographic factors and the like). The balanced scorecard would essentially operate as a ‘nudge’, using a transparent rating system to influence the behaviour of product providers and retirees alike.

Recognise every retirement is different

To take our retirement income system to the next stage of its evolution, the CIPR concept must be impactful, while at the same time allowing tailoring, innovation and the accommodation of different demographics, account balances and so on. After all, every retirement will be different.

It also needs to be palatable. Given that workers are already forced to save some of their own wages through compulsory superannuation contributions, further compulsion is unwarranted. Murray has highlighted though, that the system is letting retirees down in leaving them exposed to risks that they cannot manage on their own.

Disclosure of the ratings to consumers in a meaningful way could be key to the success of the concept. Getting the disclosure right will involve attention to other global examples and, ultimately, consumer testing. Something similar to the ENERGY STAR® ratings used for new electrical appliances in Australia might be a start. Ideally, the rating system would be something that consumers will understand and trust.

If done properly, it should be possible for the scorecard to highlight trade-offs between risk management, flexibility and returns. If retirees, as consumers, come to understand that they cannot have the highest income with full flexibility and be protected from every risk, then advisers and funds can have a discussion about the mix that they provide.

The scorecard is likely to be both informative and slightly normative in effect. Funds and product makers are likely to respond to the incentive to seek higher, rather than lower, ratings. A low-scoring CIPR would still be compliant and there would be nothing preventing retirees from investing in it. Retirees might be advised to opt for a low-scoring CIPR because they have, for example, substantial assets, an expected inheritance or a longevity product in another structure. Similarly, the scorecard would not supplant advice and is really a ‘labelling’ idea. It would necessarily be only part of the process of determining the appropriate retirement strategy for a retiree. There is no silver bullet solution in retirement.

More choice for retiring members

There is only upside in introducing CIPRs. A CIPR simply provides more choice for retiring members. Super funds will be free to retain their existing range of retirement options and to introduce new products alongside CIPRs. Retirees would have no obligation to participate in a CIPR. In every way a CIPR would be a ‘choice’ product, especially when compared with MySuper. Whereas MySuper requires a young, typically less-interested worker to do nothing or opt-out, a ‘nudged’ CIPR requires a mature, engaged retiree to opt-in. This is a key point.

It is a well-recognised feature of pension systems around the world that a retirement solution put forward by the fund itself carries with it an implicit recommendation that it is appropriate. This, again, positions the CIPR as a useful policy initiative. Fund trustees will be aware of the duty of care involved. The underlying policy purpose of the CIPR concept is to provide better risk management for retirees than is currently being afforded to them.

The retirement phase is the remaining aspect of super that needs to be brought into the 21st century. If the idea of some sort of qualitative filter or signal, such as the balanced scorecard, is embraced by the industry, then the CIPR might just be the springboard for super to become recognised as the world’s leading retirement income system.


Jeremy Cooper is Chairman, Retirement Income at Challenger Limited, former Chairman of the Super System Review (the Cooper Review) and Deputy Chairman of ASIC from 2004 to 2009.


  •   13 March 2015
  • 8
  •      
  •   
8 Comments
Jeremy Cooper
March 13, 2015

A new name is essential. 'CIPR' is a crock. It's pronounced 'SIPPER'. The letter 'C' plays the same role as the 'C' in cigar.

David Brown
March 13, 2015

well at least "Sipper" sounds better than "Kipper" - as they say - better than a slap in the face with a wet kipper.....

I agree that we have a duty to the system to develop something truly world-beating to top off, complete and complement our system. However, all the above suggestions are quite expensive and potentially complex. Difficult to boil down to a single "star rating". However, the sooner we agree on what our Kipper/Sipper looks like - not to mention - sounds like... the better we will be at ultimately determining the sort of investment strategies that will best land the correct lump sum at retirement - the point of conversion into a CIPR. Without this we have no way of knowing how "successful" our accumulation system has been to date. I would suggest that aside from the fact that contributions have enlarged the system to its vast quantity - but before we slap ourselves on the back and say what a good job we have done investing - we should first count what it has actually bought us. Bring on the CIPR debate - we have no benchmark of success without it.

Len Williams
March 13, 2015

Back in 2007 when a financial advisor put the surplus from a house sale into an annuity I was not all that keen. However, since that time, I feel it has worked well with an existing allocated pension to give a reasonable amount of flexibilty in deciding income requirements.
In regards to CIPR, perhaps the inference is that's how one should draw down; in small sips.

Adrian
March 15, 2015

How about Retirement Income Product or RIP?
At least that will get people's attention.

Bob
March 15, 2015

I note that some super funds and a peak body or two are (deliberately?) mischaracterising this FSI recommendation as requiring trustees to default members into a certain product or portfolio, which is not the case at all.

David Murray was abundantly clear that he was recommending an 'opt-in' pre-selection where the member had to make a conscious choice to invest in the CIPR when s/he reached preservation age.

I find it very curious that the big super funds have not embraced this idea as it is grounded in commonsense and is simply making sure members have more choice beyond the current account-based pension. How can this be a bad thing?

Or are they irked at being told they're not doing a good enough job when members reach retirement age?

Tony R
March 16, 2015

All very interesting but no-one seems to mention that all Australians already have access to a default 'CIPR'. It's guaranteed for life and indexed. It's called the Age Pension.
At current interest rates, the full Age Pension for a couple is valued at over $900,000. Not a bad base to build on with a flexible Account Based Pension to provide discretionary funding and quality of lifestyle. Add a $250k ABP and you have the best of both worlds.

Bob
March 17, 2015

i'd say the average Cuffelinks reader won't be entitled to the the Age Pension when they reach super preservation age, and even those who are, won't find $338 a week adequate.

Have you seriously thought about what it would be like to live on $20k a year for 25 years in retirement. That's most people's idea of penury.

And isn't that the whole point of our super system to replace all or most of the pension, in time?

We need to stop treating the age pension like a birthright and restore its (sustainable) position as a welfare safety net.

The average taxpayer finds the industry's notion of the age pension as a cornerstone risk-free asset or free option quite morally repugnant, i can assure you of that.

George
July 11, 2017

I came back to this article because the real issue is Superfunds need to start focusing on the pension phase not the accumulation (which is the easier solution). I still do no see innovation here,and in fact the system is being questioned whether it is capable of being an alternative to the government pension in the majority of situations.


Leave a Comment:

RELATED ARTICLES

Retirement: Making income the outcome

Retirement income products - what's ideal?

Retirement affordability myths

banner

Most viewed in recent weeks

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

Latest Updates

Fixed interest

Higher yields are creating opportunities in global bonds

Bond markets are adjusting to a new reality, but not in the ways investors expect. With markets repricing and capital competing for attention, investors may need to rethink where resilience and opportunity lie. 

Economy

Are we in a recession?

What if the warning signs are already everywhere? From supermarket aisles to company failures, investors are being bombarded with recession signals. But most face a different risk that can be just as dangerous for portfolios. 

SMSF strategies

Meg on SMSFs - Division 296 actuarial certificates

The tax bill might be yours, but the event that caused it may not be. A key Division 296 calculation can sometimes attribute earnings in ways that many SMSF trustees won't instinctively expect or fully appreciate.

Property

The first impact of negative gearing reform is not the tax bill

Negative gearing changes formally begin in 2027, but the first consequences may already be here. A subtle shift is quietly influencing who can borrow, how much they can access and which property strategies still stack up.

Economy

The oil market is running out of easy answers

The biggest threat to markets may not be what investors are watching. The numbers have stopped adding up and supply is harder to measure, with forecasts becoming simple guesses. A more fragile reality is being masked.

Investment strategies

The state of investor knowledge in Australia

Australians are investing more than ever, yet a surprising divide is emerging between those building wealth effectively and those making costly mistakes. Surprisingly, the gap has little to do with income, age or starting capital.

Taxation

Complexity and capital gains

A case study shows that the ‘30% minimum CGT’ is a poorly conceived tax that adds significant complexity to an already over-complex system. A less complicated model would create a much fairer progressive tax scale.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.