Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 216

The dangers lurking for credit investors

After a few small wobbles earlier in the year, the chase for yield has resumed, pushing US equities to record peaks and taking credit indices close to their most expensive post-GFC levels. Fixed interest managers are reaching further along the credit rating menu in the search for higher returns. The credit market is sufficiently diverse to cater to different investor tastes in terms of risk and return, however, behind the lure of the high yield lies some not-so-hidden dangers which every investor should be wary of. We examine the case for spread decompression and the near-term catalysts that render high yield debt vulnerable.

High yield more vulnerable with falling inflation

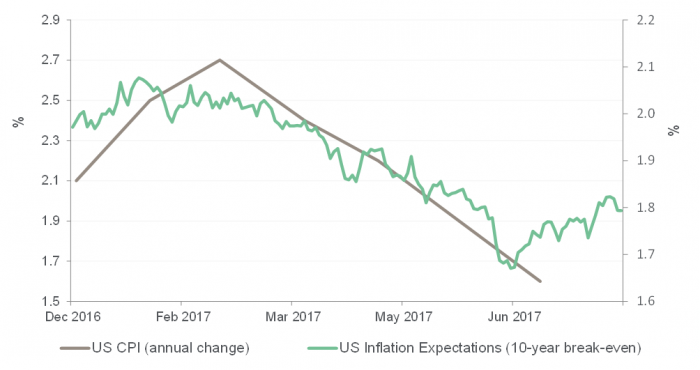
One of these dangers is the evolving broader macroeconomic backdrop. For the first time in the post-GFC era, most of the world’s developed market central banks are on the path to policy normalisation. Critically, this is in the absence of a material pick-up in inflation and inflation expectations. In fact, both measures have actually fallen this calendar year as reflected in the chart below.

Inflation expectations have fallen recently
Source: Bloomberg

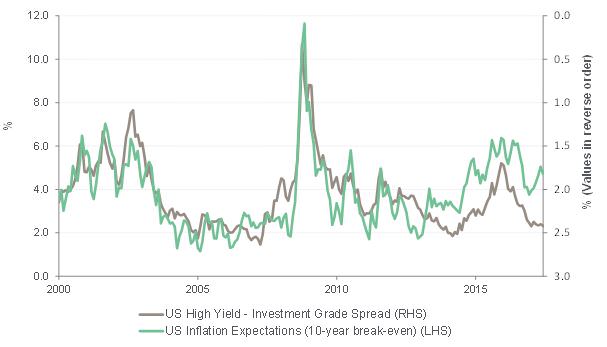
Historically, such declines in inflation expectations have been a negative for credit. Inflation expectations provide a gauge of sentiment towards future economic growth, which helps drive company revenues and debt servicing. It is important to make a distinction between debt in the investment grade camp (BBB or above) and junk bonds (BB or below), also known as high yield. It is the latter camp that is the most sensitive to a shift in the economic landscape. For example, the spread between the difference in yield on junk and investment grade typically widens when inflation expectations fall i.e. junk bonds underperform.

Contraction in high yield spreads versus inflation
Source: Bloomberg

Risks vary considerably within each credit rung of the junk bond category. While many credit investors turn to this area in an attempt to boost yields, there are varying degrees of risks that do not necessarily compensate the investor with a higher return. For example, in the CCC rating category, the extra yield declines considerably as debt increases. On average, a company with three times leverage only offers an extra 10 basis points above a company with two times leverage. Further, the ability of CCC issuers to service their debt would be severely impeded if rates rose just 1%, to the extent that the interest payments would need to be funded by issuing further debt.

Structural change leads to risks at sector level

There are also varying vulnerabilities at the sector level due to ongoing structural industry changes. These shifts cannot be weathered as easily by the high yield space when compared with their investment grade counterparts, given the former lacks the same financial flexibility.

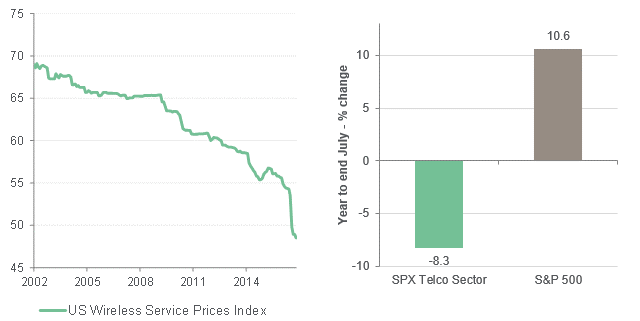
Delving deeper, while the energy sector faces challenges from weaker oil prices, the telecommunications and consumer spaces look increasingly concerning as they endure significant drops in the price of their services. The Wireless Services Price Index has fallen 11% in the six months to the end of June 2017. While the reaction has been relatively muted in high yield credit so far, the negative impact has clearly hit share prices.

High yield telecommunications vulnerabilities increase as service prices plunge
Source: Bloomberg

The consumer-orientated areas are also a worry as supermarkets and food have joined the longer-term weakness in broader retail on the back of the Amazon-Wholefoods announcement.

High yield (junk) bonds to underperform

With these factors in mind, we believe the high yield credit area is much more vulnerable than its investment grade counterpart. Benefitting from the underperformance of junk bonds is achieved through buying protection on high yield indices and selling protection on safer investment grade credit. By selling protection on investment grade, the cost of our high yield trade is reduced. In turn, the trade performs well if we see a widening of high yield spreads versus investment grade. This is a relatively defensive approach that aims to protect portfolios, as well as offering a more active alternative that can still deliver returns when more conservative credit outperforms.

Within yield-focused funds, we advocate for a more diversified approach to generating regular income by looking beyond credit markets by exposure to Australian shares that are generating consistent dividends. The Australian share market has established a reliable track record of delivering dividend yields of around 4% since 1982 and presents a suitable complement to a portfolio of high grade credit and corporate debt. With this approach investors can mitigate the exposure to risks that are gathering steam in parts of the credit spectrum.


Amy Xie Patrick is Portfolio Manager, Income & Fixed Interest at BT Investment Management. This article is general information and does not consider the circumstances of any individual.


  •   24 August 2017
  • 1
  •      
  •   

RELATED ARTICLES

Yields take centre stage again

The case for high yield bonds

BBB worries seen from beyond the headlines

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Latest Updates

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Latest from Morningstar

Does an American retirement rule work for Australians?

The 4% rule has survived decades of scrutiny, but Australia's retirement system changes the equation in ways most overlook. Before accepting or rejecting this rule of thumb, it pays to understand what really drives retirement outcomes.

Shares

Glencore lands on the ASX. Should BHP and Rio shareholders switch?

A coal-heavy miner with governance concerns isn't the obvious choice for investors. Yet, Glencore's ASX listing may offer something BHP and Rio can't. The challenge is working out whether the opportunity outweighs the risks.

Why does the system treat capital gains and losses differently?

Investors are often told not to let tax policy drive their investment decisions. Yet, under the new CGT rules, portfolio construction, volatility and even how assets are owned may have an outsized impact on their final outcome.

Economy

Three common sense reforms that Australia needs

What do frozen bank accounts, mortgage traps and pension penalties have in common? They're all symptoms of a system that makes life much harder. Yet the obvious solutions seem to have escaped the attention of Canberra.

Shares

The hidden cost of government debt for investors

Some of the important effects of rising public debt never make the headlines. Research shows the immediate effects may already be unfolding, influencing corporate behaviour in ways that many investors would never suspect.

Investment strategies

When do fundamentals matter?

Is fundamental investing losing its grip on markets? Investors continue to search for valuation-based explanations for every price move, but the dominant force behind short-term returns may be something else altogether.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.