Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 8

Jumping frogs and rhyming markets

Who is the greatest market analyst of all time? Some will nominate Benjamin Graham. Some may opt for his student Warren Buffett. I liked Ron Brierley in his day, although his lustre has faded.

But towering above them all is Mark Twain. Mark Twain, you may ask?  Wasn’t he a writer and a Mississippi riverboat poker-shark? What does he know about markets? Well, everything apparently.

"The Celebrated Jumping Frog of Calaveras County" is an 1865 short story by Twain, his first success as a writer, bringing him to national attention. In it the narrator tells a story about a gambler betting on a jumping frog.

In this story, Twain pens an immortal line for stockmarket scholars about his favorite theory: “no occurrence is sole and solitary, but is merely a repetition of a thing which has happened before, and perhaps often ...”

Like Twain, we have asked ourselves, “Haven’t I seen this all before?” At an individual level this is usually called déjà vu and can strike with incidents in life, memories triggered by visits to different places, smells or sounds.

On a bigger canvas, this is called historic recurrence and is the repetition of similar events in history often separated by long periods of time. The concept of historic recurrence has been applied particularly to the rise and fall of empires and the continual and relentless wars that erupt between tribes and nation states. Nowhere is this better observed than in the history of Afghanistan. Since the time of Alexander the Great, this beautiful but blighted region has been subjected to continual periodic invasions where the invader always and inevitably loses and goes home with its tail between its legs. If G.W. Bush had been a student of historic recurrence, much American blood and treasure (and a not inconsiderable amount of Australian) could have been saved. Alas, he doesn’t appear to have been much of a student of anything!

While people often say, “History repeats itself" in cycles, this is never exactly true. This was also appreciated by Twain, obviously a student of the long cycle, when he wrote, "History does not repeat itself, but it does rhyme."

Recurrences take place due to sometimes subtle and not readily identifiable circumstances. Some of these factors may not be understood at the time the event is occurring and may only become apparent years later. The reason for the recurrence will often be hotly debated. Nowhere is this better evidenced than in the stockmarket.

As the chart below shows the stockmarket may not be repeating history but it’s rhyming, with all the exuberance of a Wordsworth poem.
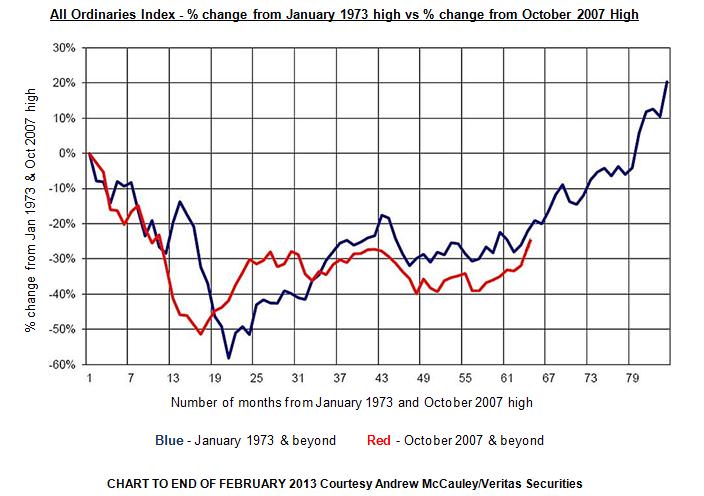
The Australian equity market is presently repeating a performance pattern similar to the mid 1970’s recovery. It’s not performing exactly the same way, but it’s close. It is now 65 months with a 25% decline since the Australian equity market peaked in late 2007. Over the same time frame (65 months) from the pre-decline peak in January 1973 to March 1978, the All Ordinaries Index had fallen by approximately the same amount as shown in the chart. Both periods experienced peak to trough reversals of more than 50%.

The chart shows the returns from the All Ordinaries Index post the 1973 and 2007 peaks. As is readily observable, the moves in the two periods tend to mirror each other. Let’s say it is not repeating itself but it sure is rhyming.

“So what?”, you may ask. The model, if it is a true example of historical recurrence, may predict the course of the sharemarket over the next couple of years. Or it may not.

Why would this rhyming model work? Simple. The stockmarket is a barometer of human emotion and particularly human frailty. It registers them all … fear, greed, lust, paranoia, confusion, panic, herd-mentality, envy and disappointment. It’s a big human stew but the ingredients never change so the taste is the same, although it comes to the boil at different times. “Gee haven’t I tasted this somewhere before?” The ingredients never change because people never change. Not really. Not even over long periods of time.

The herd always charges off together in one direction then just wait, what’s that sound you hear? It’s the herd charging back again in the opposite direction. They head off over the hill. What is the only thing you know for sure? That given time you will see them all come thundering over that same hill heading in the direction they first came from. Humans, like jumping frogs and migrating wildebeest, never change. The graphs from 1973 and 2007 demonstrate this.

Writing novels and playing poker on riverboats, while consuming large quantities of whisky, does not a great market analyst make! Or does it? I think I’ll try it.


Kieran Kelly is Managing Director of Sirius Fund Management and has over 30 years’ experience in fund management and sharebroking.


  •   28 March 2013
  •      
  •   


Leave a Comment:

RELATED ARTICLES

ASX reporting season: Room for optimism

An odd and wild ASX reporting season

Why long term investing is not easy

banner

Most viewed in recent weeks

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Superannuation’s structural failings

Politicians are fighting over access to super, but they may be arguing about the wrong thing. The system’s three fundamental flaws have been hiding in plain sight for decades, costing Australians far more than they realise.

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Does an American retirement rule work for Australians?

The 4% rule has survived decades of scrutiny, but Australia's retirement system changes the equation in ways most overlook. Before accepting or rejecting this rule of thumb, it pays to understand what really drives retirement outcomes.

Latest Updates

Superannuation

Bill Kelty: Super can't solve everyone's problems

One of the key figures behind Australia’s superannuation system reflects on how it began, what has changed, and why some of today’s biggest debates may be asking too much of a retirement savings system.

Investment strategies

Rising yields have put bonds back in business

For the past decade, investors were forced to chase income wherever they could find it. With yields now offering competition to dividends, the new challenge is deciding whether they're still being adequately rewarded for risk.

Strategy

Do you want a bucket with that?

Retirees, advisers and super funds all talk about the bucket strategy as if it's one thing. It's not. The differences can be significant, and some may matter far more than investors realise when markets become volatile.

Investment strategies

What The Odyssey can teach us about valuation discipline

Investment temptations are hard to resist in the moment, but successful investing is not about ignoring compelling opportunities or ideas. For value investors, the smart move is to prepare before momentum clouds judgement.

Shares

Does market concentration really mean more risk for investors?

One of the most closely watched trends in global markets has become a growing source of investor concern in recent years. Whether that concern is justified, however, turns out to be a far more complicated question.

Retirement

Retirement in reality - 8 months in

Health goals, new friendships and lingering questions about identity have dominated this month. The experience has challenged widely held beliefs about purpose, belonging and what it really means to leave work behind.

Shares

Stagnation might be OK at this point

Australia's economic problems are hardly a secret. The more interesting question for investors is whether the stock market is as exposed to those problems as commonly assumed, or whether the picture is more nuanced.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.