Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 189

The SMSF sector by the numbers

The best available data on the SMSF sector as a whole comes from the latest ATO statistics. The report released in December 2016 is based on 2014/15 SMSF tax returns, with the time lag due to the tax return process.

Largest sector but slower growth

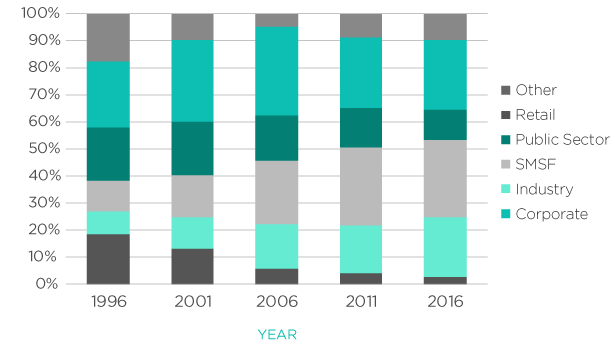
SMSFs remained the largest sector of the Australian superannuation industry, with 29% of the $2.1 trillion total super assets as at 30 June 2015. However, in the past five years, SMSFs are no longer the fastest-growing sector due to increased growth of institutional funds. During this period, total super assets grew by 59%, while SMSF assets grew by 55%, and non-SMSF funds by about 61%. The SMSF net cash flow, based on contributions and rollovers minus benefit payments, fell from $16 billion in 2011 to $7.8 billion in 2015.

Superannuation assets by industry sector, as at 30 June 2015 (Source: ATO)
 

Larger SMSFs share rising quickly

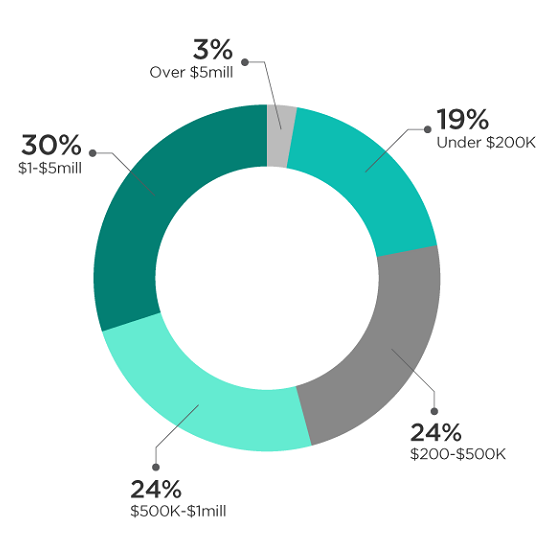
The average balance per SMSF was about $1.1 million as at 30 June 2015. Referring to the chart below, the number of SMSFs with more than $1 million of assets grew from 27.5% in 2011 to 33.0% in 2015, with 3% over $5 million. Conversely, the number of SMSFs under $200,000 fell from 24.7% in 2011 to 19.1% in 2015.
SMSF member balances and ages

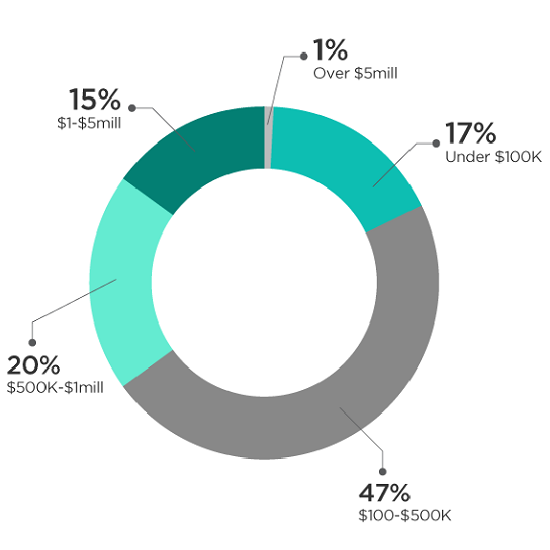
The average member balance was $589,636 compared with the average non-SMSF member balance of $46,000. The largest group of members (47.5% of the total) have balances between $100,000 and $500,000. Almost 17% of members have balances below $100,000 while 15.9% of members have individual balances in excess of $1 million.
About 38% of SMSF members also had entitlements in other superannuation funds, presumably to maintain insurance.

About 71% of SMSF members were over 50 years of age. This contrasts with non-SMSFs where 71% of members are under age 50. However, there are signs of increasing SMSF uptake among a younger age band. The 2015 year shows members below age 35 representing slightly over 10% of the newly established funds, compared with 5.7% for the whole SMSF member population.

Contribution levels

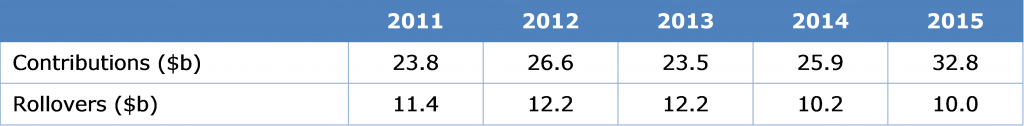
In the five-year period to 30 June 2015, contributions to the SMSF sector averaged $26.6 billion a year (member contributions $20.0 billion, employer contributions $6.6 billion). Member contributions to SMSFs increased by 54% over this period, while employer contributions decreased by 0.5%. In comparison, both member and employer contributions to all super funds increased by approximately 48% and 24% respectively. This discrepancy is driven by age differences between members of SMSFs and other super funds, with non-SMSFs having fewer retired members and thus receiving more compulsory employer contributions.
Form of benefits heavily skewed to pensions

94% of all SMSF benefit payments now are pension payments, a significant increase from 74% in 2011. The proportion of benefits relating to transition-to-retirement pensions is 19% for SMSFs compared to 12% for superannuation overall.

Despite the higher average age demographics of SMSFs, only 48% were paying pensions to at least one member, while 52% of SMSFs reported they were solely in the accumulation phase.


Philip La Greca is Executive Manager of SMSF Technical and Strategic Solutions at SuperConcepts, a leading provider of SMSF services. SuperConcepts is a sponsor of Cuffelinks.

  •   9 February 2017
  •      
  •   


Leave a Comment:

RELATED ARTICLES

7 vital steps to compliance for your SMSF

Six advantages of an SMSF

When death benefits include life insurance

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

Latest Updates

SMSF strategies

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

Planning

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Exchange traded products

The hidden trade-off in fixed income ETFs

Some investment trade-offs are immediately visible. Others are embedded in the way a portfolio is constructed. Understanding the difference may explain why similar-looking investments can produce surprisingly different results.

Retirement

The mortgage free retirement is fading

What happens when a generation reaches retirement carrying obligations previous generations largely avoided? New research suggests we may need to rethink both how much we need in retirement and what life could look like.

Retirement

The key question to inspire a confident and purposeful retirement

Most people spend decades planning for retirement. Far fewer plan for what happens when they get there. The difference may explain why so many find the transition harder and less fulfilling than expected, despite careful preparation.

Latest from Morningstar

Making the case for a 'good enough' portfolio

Some investors spend years chasing the perfect strategy. Others choose a path that’s simply good enough and move on. Which approach is more likely to deliver both better outcomes and a happier financial life over the long run?

Investment strategies

Is the US market as expensive as CAPE says?

Many investing ideas survive for decades. But that does not make them right. A famous valuation measure implies that US shares are dangerously expensive, but the evidence may point to a very different conclusion.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.