Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 269

Five structural headwinds hitting the global economy

The bad news is that low interest rates, low inflation and low economic growth are likely to be our global economic reality for at least for the next decade. This means challenging business conditions for businesses and investors.

However, the good news is that quality businesses will come into their own. The cyclical improvement in economic growth that has occurred over the past two years is likely to run its course over the next 18 months or so, and average businesses and speculative stocks that have enjoyed temporary macro tailwinds will face a more difficult environment as the cycle turns. Only quality companies with fundamentally solid business propositions will produce long-term growth.

Let’s look at some of the key structural headwinds facing the global economy.

1. The future fall-out from high levels of debt

Consumer and government debt have both increased substantially in most major economies over the past decade. Gross Federal Government debt to GDP in the US has risen from around 40% in the 1980s to approximately 105% in 2017.
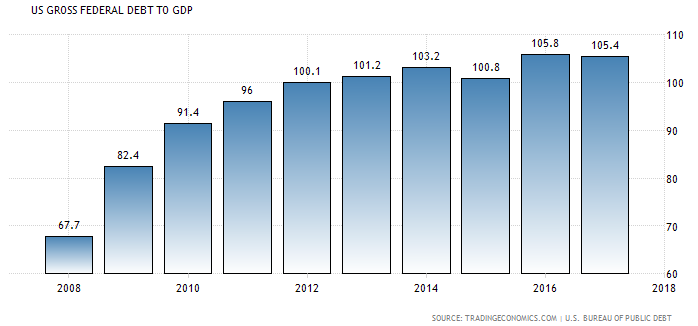
Over the same period, household debt to GDP in the US has risen from just under 50% to around 80%. And the same story has played out in China, where gross government debt to GDP has risen from under 25% in the 1990s to approximately 48% in 2017, and household debt to GDP in China has increased from under 20% to 48%.

Higher levels of debt have provided a one-off boost to historical economic growth rates by bringing forward consumption and investment, but at the same time, higher financial gearing has increased financial risk levels generally. The global economy’s ability to respond to economic shocks is lowered, while society’s sensitivity to future increases in interest rates has risen.

2. Globalisation drives wealth inequality in developed countries

As the world has become more interconnected, materials and workforces can be more effectively sourced from countries with the lowest cost. Access to foreign capital has improved the lot of workers in less developed countries, but placed downward pressure on the income of workers in developed countries.

Furthermore, migration rates and the declining influence of unions in developed countries have also had the effect of reducing labour costs. The benefits of globalisation have become particularly evident in the increasing numbers of high net worth individuals in countries such as China and India. From 2012 to 2017, the growth in individuals with US$50 million or more in the Asia-Pacific region grew by 37%, and it’s predicted that the number of ultra-wealthy individuals in China will double in the next five years.

The wealth of high net worth individuals is growing relative to individuals in the middle and lower economic brackets. A hollowing out of the middle class is occurring due to downward pressure on wages and increases in automation at the middle-income level. Also, a general trend towards lower corporate tax rates and lower effective marginal tax rates for high-income earners over the past few decades has also accelerated the trend towards inequality. Lower corporate tax rates primarily benefit the wealthy because they are the biggest owners of businesses. According to the World Inequality Database, in 2014, the wealthiest 1% in the US owned 39% of total wealth, up from 22% in 1978.

3. No higher productivity despite technological innovation

Humans have always innovated to improve production output and reduce human labour hours for economic gain. At certain stages, technological advancement has caused huge leaps in both productivity and the average standard of living. However, since the late twentieth century, technological changes in the form of computing, communication, robotics and artificial intelligence have not resulted in higher levels of productivity, and average wage levels have remained depressed in most developed countries.

We have reached a point where some predict that most of the jobs currently undertaken by humans will be replaced by machines and artificial intelligence, and the nature of jobs will change fundamentally. The emergence of some fundamental changes are already impacting the workforce: increasing use of robotics and 3D printing in warehouses, manufacturing and medicine, to name a few. Businesses generally benefit from automation through lower costs, whereas workers only benefit if they can be redeployed into better quality, higher paying jobs.

4. An ageing population will supress real economic growth

An ageing population has implications for labour force growth, both the number of work hours per person and consumer spending. As a population ages, fewer people will be engaged in full-time employment or be able to generate an income from human labour activities. The retirement of the baby boomers is predicted to negatively impact the growth in labour hours per person from 2008 to 2034, with negative implications for real economic growth.

Also, living longer means that individuals will have extended economic requirements that will need to be funded. This may be through government pensions, pension funds or working longer. However, lower incomes mean lower income taxes, at the same time that increasing numbers of retirees are placing strains on pension systems.

5. Climate change and other environment-related constraints

According to the Worldwide Fund for Nature Living Planet Report from 2016, the bio capacity equivalent of 1.6 Earths was needed in 2012 to provide the resources and services humans consumed in that year, and the situation has since worsened. Demand for natural resources is fast outpacing the rate at which resources can be renewed, and the burning of fossil fuels is most to blame.

The link between climate change and investment markets may not be immediately obvious, but every business and household in the world will be negatively affected.

Extreme weather events, including prolonged drought and super storms adversely affect agricultural production, and acidification of the ocean as it absorbs excess CO2 does the same to the marine ecosystem and fishing. It is difficult to predict with certainty what the specific outcomes will be, but the geographic distribution of the supply and demand of goods and services will change, redefining global trade.

Concluding

Global economic activity has experienced a cyclical uptick in the past couple of years, but in our view, the longer-term outlook for economic growth remains subdued due to these structural headwinds.

In a low-growth world, most asset classes will produce relatively low total returns. Our base case is for global equites to produce total real returns that average around 3.5% to 4.5% p.a., and many sectors of the market will find it difficult to maintain current levels of earnings in real terms over the next decade.

For investment managers, tackling low growth is challenging. When the economic tide turns, average businesses frequently fail, and only those businesses with strong fundamentals, in the form of high-quality business models, including low gearing, and large addressable markets will have the ability to offer earnings growth and long-term returns for investors.


Mark Arnold and Jason Orthman are the Chief and Deputy Chief Investment Officers respectively at high-conviction equities manager, Hyperion Asset Management. This article does not consider the individual circumstances of any investor.


  •   29 August 2018
  • 4
  •      
  •   
4 Comments
Gary M
August 29, 2018

Of course, many of these 'headwinds' are 'tailwinds' for some companies, such as climate change, technology and an aging population.

Warren Bird
August 29, 2018

1 - 4 are fairly standard medium to long term influences on the investment environment.

5 is qualitatively and quantitatively different. It's potentially a game changer! Just read the final paragraph of that dot point and try to think that this is just a 'headwind' and not a new paradigm with a new set of risks for how people live, let alone for how companies earn money.

Yes, Gary M, these are tailwinds for some - and the funds I oversee are seeking those opportunities constantly - but the bigger issue is the challenge that climate change and its impacts represents to all companies, governments and households to change the way they do a lot of things. As a colleague of mine wrote a few months ago: "Integrating climate and natural disaster risks and resilience into financial systems presents opportunities to help save millions of lives and livelihoods in the coming decades and to protect billions in assets and property in a cost effective and rational way when weighted against competing priorities."

More like a hurricane headed towards us than a headwind!

John Bedson
August 29, 2018

These "Headwinds" are merely the proverbial "Wall of worry" that stocks have climbed for the past two hundred years. Pessimistic articles like this are a dime a dozen and mean nothing. Nine years ago Dr Doom, Nuriel Roubini said that the stock market rebound was a "Fools rally" because the outlook was bleak and it turned out to be the longest bull market in all of history! I think that the future looks great.

The US is on the rise again and China and Russia are going broke. - What could possibly go wrong for us?

Peter S
August 30, 2018

Graham

I have the classic 4 phases in mind.

Pessimism
Skepticism
Optimism and
Euphoria

I feel we are only in the first few minutes of the Optimism phase given the long period of time we remained in Skepticism. The Trade War successes of Trump this far have commenced the optimism momentum.

I am also seeing a golden period of interest rate equilibrium ahead. Even inverted yield curves at extraordinarily low rates that give us nothing more than controlled and precise deceleration, not the recessionary hard braking of the past when yield curves inverted at high rates.

I favour overexposure to growth assets and am “All In” for at least the next 2 - 4 years minimum…….maybe a 2023 slowdown after a couple of preceding years of Euphoric overshoot.

Cheers

Peter


Leave a Comment:

RELATED ARTICLES

America eats the world

Why Australia’s roaring population growth won’t last

Two companies well-positioned amid supply chain disruption

banner

Most viewed in recent weeks

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

Testamentary trusts have secured the CGT exemption

Treasury’s latest CGT reform draft delivers a win for testamentary trusts and deceased estates, exempting estate-derived gains from the 30% floor. However, questions on death and divorce rollovers remain unresolved.

Meg on SMSFs: What do we think about reversionary pensions these days?

Reversionary pensions have long been a staple of SMSF estate planning, but are they still the best option? Meg Heffron revisits a once-clear favourite and asks whether changing super rules have shifted the balance.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

How does the 4% rule stack up?

The 4% rule has long been retirement's gold standard. But after a difficult period for investors, fresh analysis suggests a more conservative approach may significantly improve the chances of making savings last.

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

Latest Updates

Planning

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

Superannuation

There's a reason why your super is locked up until your 60s

For decades, it seemed settled. Then one controversial idea reignited a debate that could reshape the financial future of millions. The real question isn’t who’s right or wrong, but whether a long-held assumption deserves another look.

Property

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Retirement

Under-retiring: The greatest retirement risk in a generation

Two retirees. Similar savings. Completely different lives. New research from Challenger reveals why some Australians confidently spend in retirement while others hold back and the overlooked factor shaping retirement decisions.

Five risks to watch in markets

Things you may often hear are: a recession is around the corner, markets are overpriced, the AI sector is about to flop at any moment. It’s like the never-ending laundry pile that sits in my house, it never really disappears.

Investment strategies

Do you qualify as ‘rich’?

What does it mean to be 'rich'? For something so universally desired, it is surprisingly difficult to define. That ambiguity creates a challenge for investors and raises a bigger question about what financial success really looks like.

Investment strategies

If you’re worried about your bond portfolio, you’re missing the point

Most investors think they know what bonds are for. But when markets turn volatile, a surprising misunderstanding can lead to costly decisions. Here’s the overlooked lesson that could change how you view your portfolio.

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.