Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 1

To be perfectly franked, and pay no tax

Kerry Francis Bullmore Packer would have loved superannuation and franking credits. In 1991, he was subpoenaed to appear before a Parliamentary Committee enquiring into the print media, and it was wonderful theatre. He bellowed out his responses and left most of the Committee members cowering. But his most memorable response came when asked about his company’s tax minimisation schemes:

"Of course I am minimising my tax. And if anybody in this country doesn't minimise their tax, they want their heads read, because as a government, I can tell you, you're not spending it that well that we should be donating extra!"

You may not feel quite as critical as Mr Packer, since our taxes pay for health, schools and pensions, but the superannuation system has been designed to encourage people to finance their own retirement, so it makes sense to use it. Income in superannuation is taxed at 15% in the accumulation phase, and personal marginal tax rates rise from 15% to 19% when earnings exceed $18,200, so income in superannuation is tax effective for anyone earning above this amount.

But that’s only half the story. Let’s put franking credits into the mix by understanding how dividend imputation works. Companies pay tax on their profits at a rate of 30% before dividends are paid to shareholders. In the hands of an investor receiving the dividend, the tax paid is called a franking credit or an imputation credit. For tax purposes, the shareholder receives both a cash dividend plus the imputation credit, and is treated as if they paid tax equal to the imputation credit.

The system operates like this to avoid double taxation of income. In effect, the shareholder receives back the tax that has already been paid by the company and instead pays tax at the investor’s own tax rate. If the owner of the shares is on a tax rate less than the 30% company tax rate, such as superannuation funds, they are entitled to a rebate of the overpaid amount.

Let’s consider a simple example. A company earns a profit of $10,000, and pays tax of $3,000, leaving $7,000. It pays this amount as a franked dividend to its only shareholder, which is a super fund. In its tax return, the super fund adds the tax already paid by the company to the cash dividend received. The 'grossed up dividend' is $10,000, and the super fund pays tax on this at 15%, or $1,500. However, it receives a credit worth $3,000 for the amount of tax already paid by the company, leaving a tax refund of $1,500. Neat!

So it’s a matter of relatively simple maths to calculate how much fully franked dividends is needed to offset the income tax due on the rest of a super fund’s portfolio, and therefore pay no tax, meaning that no investments need to be sold to fund the tax bill.

Skip the following box if you don’t have a mind for numbers.
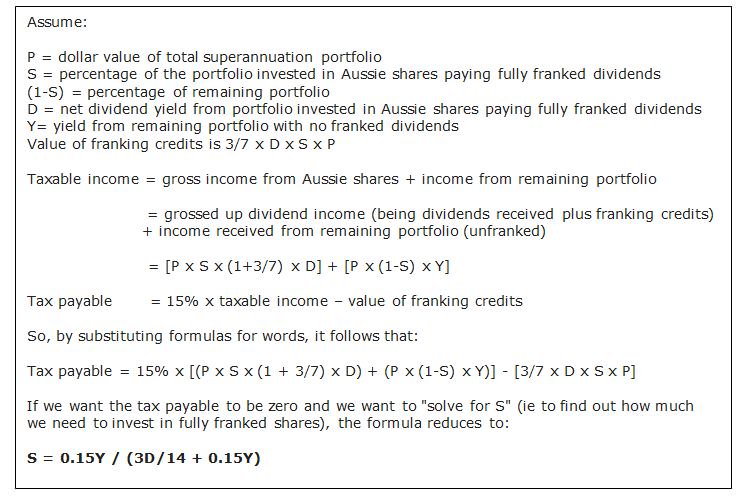
So with some current day numbers, this formula can be used with actual values for D (the dividend yield on the shares) and Y (the yield on the rest of the portfolio) to determine how much of a portfolio needs to be invested in fully franked shares to have a zero tax rate on the entire portfolio.

  • a franked dividend yield on the Australian shares portfolio of 6%
  • an unfranked yield on the remaining portfolio of 4% (eg term deposits).

The portfolio would only need to contain 32% of Australian shares paying fully franked dividends to have a zero tax rate. And without getting into a discussion on portfolio construction, most Australian super funds can justify an allocation to Australian shares of at least one-third.

The calculation ignores the impact of any realised capital gains and expenses from running the portfolio.

The combination of favourable tax rates and dividend imputation shows the power of saving in a superannuation vehicle. Once a fund converts to paying a pension, there is no tax payable by the fund on earnings. In this case, imputation credits are refunded in cash. Furthermore, if the pension recipient is aged over 60, then pension drawdowns are also tax free.

Kerry Packer would have loved it. All that income and no tax. And later, a refund from the government.  Kerry probably learned a lot from his father, and maybe it's no coincidence that this powerful process carries the same name as that equally powerful man. Sir Frank.
 

  •   3 February 2013
  • 2
  •      
  •   

RELATED ARTICLES

The missing link in the CGT debate

No, Division 296 does not tax franking credits twice

Clearing up confusion on how franking credits work

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Latest Updates

Retirement

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

2026 is not 1999

The US market looks eerily similar to the dot-com era with soaring AI spending and tech giants dominating returns. But one difference separates today’s boom from the dot-com bubble and it could determine what happens next.

Planning

Taxing time for trusts

Trusts are facing a shake-up, but an overhaul may not be necessary. Families can explore restructuring strategies that preserve succession and the asset protection benefits that have made these structures valuable.

Economy

Why the US economy is stronger than you might think

War, inflation and higher rates were expected to derail America. But has the market got it wrong? Three forces are driving the economy beyond expectations, revealing implications for stock prices and portfolio positioning.

Gold

How much trust is in your portfolio?

Everyone talks about diversifying assets. Far fewer think about diversifying trust. As inflation, debt and market assumptions collide, the question is whether portfolios need greater protection from unexpected outcomes.

Retirement

Retirement in reality - 7 months in

Seven months into retirement, I'm still uncovering surprises. This month was spent reflecting on the slow pace of health change, the myth of neatly scheduled part-time work and the unexpected persistence of retirement guilt.

The new geography of technology leadership

The next chapter of technology may not belong to the companies or business models many expect. As the landscape shifts, some opportunities are emerging in places that remain surprisingly overlooked by global markets.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.