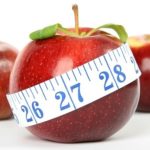
[Editor's comment. Check this image. Anyone offended? We had to laugh. Here at Cuffelinks, we regularly promote articles on Facebook (yes, for a cost). When we posted an ad for this article, Facebook's multi billion dollar AI engine knocked it back within minutes for the following reason:
"This ad isn't running because it uses images that excessively focus on a person's body or any given body part (ex: focusing on abs or belly fat). This can make users feel bad about themselves, and goes against our core value of fostering a positive global community. What to do next: Avoid images with close-ups of specific body parts or before-and-after photos."
You have to worry about AI, supposed to be the way of the future, when it cannot distinguish between an apple and a body. Maybe that's why it's called 'artificial' intelligence. At least the apple's sensitivities are safe while they work out how to restrict posts by terrorists and extremists.
We apologise to any apple that we offended. Or is that Facebook protecting apple?
Now, on with the real article.]
More than ever before, people of the world are keeping a close eye on their diets. Obesity has trebled since the 1970s, conditions such as diabetes and heart disease are rising, and in some high-income countries, life expectancy is flattening out. Food and beverage producers are under immense pressure to reform, both from stricter regulations and consumers demanding healthier choices.
As we consider how shifting health and nutrition trends impact business models, we see four outcomes which present both risk and opportunities.
1. Making food healthier
Taxation aimed at promoting better standards of nutrition has been introduced by dozens of national governments, states and individual cities, especially since 2015 when a damning World Health Organisation report was published.
Much of the focus is on sugar. In Mexico, for example, the world’s second-most obese country and where diabetes is the leading cause of death, a levy is placed on all sugary drinks except milk. In the UK, where a new tax on sugar levels was introduced in 2018, more than 50% of manufacturers reduced the sugar content of drinks ahead of its implementation.
Some leading companies have already made big commitments. Britvic, for example, has promised to reformulate its drinks in most countries, cutting sugar content and reducing average calories per 250ml by 20%. Meanwhile, Pepsico pledges to reduce sugar, saturated fat and sodium across many of its food and beverage products as part of its 2025 goals.
2. Right-sizing the product
Where reformulation is not possible, companies are instead focusing on portion size. Drinks manufacturers like Coca Cola (which notably had to reverse plans to introduce a new sweeter Coke recipe in the 1980s) has introduced slimline cans, meaning sugar content for the consumer is reduced with no reformulation required.
However, companies that go down this route have to exercise caution, as such a move could be damaging from a consumer perception that it is simply protecting margins via ‘shrinkflation’ (where the product shrinks in size but remains at the same price). Confectionary giant Mondelez tried to change the shape of its iconic Toblerone to guard against rising cocoa prices but was forced to change back and put up prices after a public outcry.
3. Transparency and labeling for consumers
A key factor for consumers is wanting more control over the choices they make. Transparency from companies over what their products contain is paramount. Making more information available on the nutritional value of products is an important factor in retaining their license to operate.
Voluntary ‘traffic-light’ schemes, displaying levels of calories, fat, sugar and salt have been introduced in many countries. Some companies are preempting the changes, such as Danone which is rolling out its ‘Nutri-Score’ colour-coding system in countries across Europe, even those where there is no labeling system in place yet.
4. Product change to healthier products
Finally, many businesses are making wholesale changes to their product lines to reflect the new environment. As consumers begin to view ultra-processed food in the same vein as smoking, companies are either simply cutting unhealthy products or switching to healthier alternatives.
Britvic, for example, now says 70% of its innovation pipeline is focused on developing low or no-sugar drinks (less than 5g per 100ml). Meanwhile, Kerry Foods has developed four ‘consumer nutrition pillars’ consisting of ‘free-from’ foods, diet brands, natural foods and products tailored to particular nutritional needs such as infants or individuals with specific medical conditions like diabetes.
Coca-Cola Amatil, based in Australia, is one of the largest bottlers of non-alcoholic ready-to-drink beverages in the Asia-Pacific region, operating also in New Zealand, Indonesia, Papua New Guinea, Fiji and Samoa. In the Australian domestic market, Coca-Cola Amatil has launched low-calorie alternatives, such as Coke Zero, and innovative sparkling waters to reduce the distribution of products causing obesity and related health issues. They are taking advantage of the growing demand for healthier beverages.
Change in emerging markets is slower
Coca-Cola Amatil’s approach to developing markets, such as Fiji and PNG, is however different to that in Australia, with the new healthy alternative not being distributed to those markets due to lack of demand.
Martin Currie Australia initiated discussion with the Coca-Cola Amatil Board in 2018 to enact change. The company has acknowledged the obesity and related health implications from their predominately full-sugar drinks, and they are working with the governments on solutions and further health education.
The investment perspective
The scale of opportunity from an investment perspective goes further than simply food and drink manufacturers. Food technology plays an increasingly important role, and the trend of health and wellness involves science-based companies like the developers of supplements (such as vitamins or flavour enhancers), and probiotics – live bacteria which can help reduce gastrointestinal problems and strengthen the body’s immune system.
There are also investment opportunities that provide investors with more control over how their funds are invested. For example, the Legg Mason Martin Currie Ethical Income Fund range explicitly will not invest in companies that are involved in the production or sale of alcohol or tobacco, leading to companies such as Coca-Cola Amatil, Woolworths, Coles, Metcash and Amcor being excluded from the investible universe.
The food and beverage sector is fiercely competitive and many companies are sensitive to both the large shifts in consumer sentiment towards healthy eating, as well as the heightened focus from politicians on nutrition and wellness. In all of our investment strategies, this requires us to look at which companies are successfully tackling the challenge, as well as those that are not. ESG analysis provides a valuable future view on the impacts for companies in this sector, including the opportunities and the threats, and by extension, the winners and the losers.
David Sheasby is Head of Stewardship & EGS at Martin Currie and Will Baylis is a Portfolio Manager with Martin Currie Australia, Legg Mason affiliates. Legg Mason is a sponsor of Cuffelinks. The information provided should not be considered a recommendation to purchase or sell any particular security. It should not be assumed that any of the security transactions discussed here were, or will prove to be, profitable. Please consider the appropriateness of this information, in light of your own objectives, financial situation or needs before making any decision.
For more articles and papers from Legg Mason, please click here.