Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 302

3 key risks: banks are too big to behave badly

It’s difficult to imagine the landscape without them. Indeed, history has shown that they’re too big to fail. However, revelations from the Financial Services Royal Commission have certainly taken a toll on how we perceive our major banks.

As investors, we have been long-term beneficiaries of the regular dividends they pay and yet some of the conduct uncovered has been reprehensible. So as investors, how should we look at banks in the future?

For me, there are three key areas to consider:

1) The importance of managing risk

Since the GFC, banks have made many changes to shore up what were already strong capital foundations. Capital ratios have risen almost three-fold in 10 years to ‘unquestionably strong’ levels. Liquidity management has also strengthened with banks switching to more stable sources of funding and increasing their holdings of liquid assets. As a consequence, Australian bank return on equity (ROE) has slightly decreased to around 12% but still remains strong by international standards (around 8% for large US banks).

Today, we’re largely at the tail-end of this shoring up process, although as highlighted by the Royal Commission, there’s still some work to do to mitigate operational risk stemming from poor culture. To date, the financial implications for ‘banks behaving badly’ have been relatively minor, but the consequences of reputational damage could significantly impact profitability if it continues.

2) A slowing credit market

In the last 12 months the credit market has noticeably slowed, as shown below. This is likely to continue, at least on the investor side, as a result of households becoming more cautious and banks tightening their lending standards. With household debt at high levels relative to global benchmarks, this isn’t altogether a bad thing. In fact, longer term it will have a positive impact on our financial security as Australia and the banks will be more resilient to a downturn.

Credit growth (six-month-ended annualised)
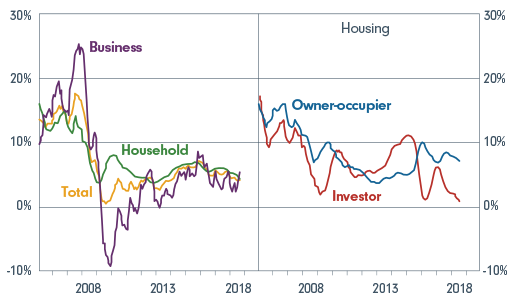
Source: APRA, RBA

Shorter term however it does have a couple of implications for the majors:

  • Fewer loans mean less profit.
  • Tighter lending practices mean more stringent checks and balances which increases the time it takes to process a loan application.

Tighter lending standards have meant more paperwork because it’s new and the process is still quite manual. Over time, it will become increasingly automated making the process much faster and importantly cheaper. We can expect to see technology projects replace people as the need to reduce the cost of labour intensifies.

3) Disruption from an intruder

In the last 10 years, we have witnessed some remarkable changes in market leadership in other industries. Established Goliaths have fallen as disruptors have swept in and completely sidelined their business models. So, could something like this happen to the major banks?

There will continue to be smaller companies which pick off individual niches. For example, OzForex in foreign exchange and AfterPay in payments. But when it comes to the core banking operations, Australian banks have invested heavily in technology particularly around service and convenience and a disruptor would have to offer something unique to displace them in a material way. This is especially true in banking, given the time it takes to establish the ‘trust’ many of us seek from our institutions.

Perhaps what strikes me most about Australia’s banks is their ability to adapt. Whether it be self-regulation to strengthen their financial health or investing heavily in technology to meet the changing needs of their customers, they really are the ultimate market chameleons. And they’ll need to be.

The GFC proved they were ‘too big to fail’ but today the message from the Royal Commission is clear - they’re 'too big to behave badly'.


Kate Howitt is a Portfolio Manager of the Fidelity Australian Opportunities Fund. This document is issued by FIL Responsible Entity (Australia) Limited ABN 33 148 059 009, AFSL 409340 (‘Fidelity Australia’), a member of the FIL Limited group of companies commonly known as Fidelity International. This document is intended as general information only. You should consider the relevant Product Disclosure Statement available on our website www.fidelity.com.au.

Fidelity International is a sponsor of Cuffelinks. For more articles and papers from Fidelity, please click here.

© 2019 FIL Responsible Entity (Australia) Limited. Fidelity, Fidelity International and the Fidelity International logo and F symbol are trademarks of FIL Limited. FD18634


  •   17 April 2019
  • 1
  •      
  •   

RELATED ARTICLES

The sorry tale of our big banks

The outlook for Australian banks

Clime time: A big win for bank customers against scammers

banner

Most viewed in recent weeks

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Superannuation’s structural failings

Politicians are fighting over access to super, but they may be arguing about the wrong thing. The system’s three fundamental flaws have been hiding in plain sight for decades, costing Australians far more than they realise.

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Does an American retirement rule work for Australians?

The 4% rule has survived decades of scrutiny, but Australia's retirement system changes the equation in ways most overlook. Before accepting or rejecting this rule of thumb, it pays to understand what really drives retirement outcomes.

Latest Updates

Superannuation

Bill Kelty: Super can't solve everyone's problems

One of the key figures behind Australia’s superannuation system reflects on how it began, what has changed, and why some of today’s biggest debates may be asking too much of a retirement savings system.

Investment strategies

Rising yields have put bonds back in business

For the past decade, investors were forced to chase income wherever they could find it. With yields now offering competition to dividends, the new challenge is deciding whether they're still being adequately rewarded for risk.

Strategy

Do you want a bucket with that?

Retirees, advisers and super funds all talk about the bucket strategy as if it's one thing. It's not. The differences can be significant, and some may matter far more than investors realise when markets become volatile.

Investment strategies

What The Odyssey can teach us about valuation discipline

Investment temptations are hard to resist in the moment, but successful investing is not about ignoring compelling opportunities or ideas. For value investors, the smart move is to prepare before momentum clouds judgement.

Shares

Does market concentration really mean more risk for investors?

One of the most closely watched trends in global markets has become a growing source of investor concern in recent years. Whether that concern is justified, however, turns out to be a far more complicated question.

Retirement

Retirement in reality - 8 months in

Health goals, new friendships and lingering questions about identity have dominated this month. The experience has challenged widely held beliefs about purpose, belonging and what it really means to leave work behind.

Shares

Stagnation might be OK at this point

Australia's economic problems are hardly a secret. The more interesting question for investors is whether the stock market is as exposed to those problems as commonly assumed, or whether the picture is more nuanced.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.