Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 443

It's time to assess your super fund’s carbon footprint

We now hear it from just about all corners of our industry - the race to net zero emissions is an investment thematic that can’t be ignored.

However, here in Australia (and many other parts of the world) investors can draw little confidence from the political environment.

Our government is willing to keep kicking the can down the road, begrudgingly agreeing to a net zero 2050 target with a pathway full of technological holes. The problem is 2050 is about 10 election cycles away.

So, we face a hugely-consequential economic transformation that’s not yet a priority for governments and oppositions.

Bigger than government

Despite the lack of political leadership, Australia is in fact doing reasonably well on the climate front. Emissions are falling at the total level, while emissions from electricity generation have halved from their peak. At one stage in September 2021, around 60% of Australia’s electricity demand was fulfilled by renewables.

But it is individuals and corporates responsible for this change, not governments. For families, not only does renewable energy make economic sense, but feeling good for our planet’s future is no doubt part of the motivation.

The same goes for corporates. Many of Australia’s largest companies (and largest emitters) have already adopted some very aggressive carbon reduction targets.

As an example, we recently met with Mineral Resources, which mines lithium and iron ore. Mineral Resources has scoped out over 80 Net Present Value positive projects that will help put it on its path to net zero by 2050, as it moves from a diesel-fueled mining company to a renewables-based electrified mining company.

Companies such as Amcor, CIMIC, Coles, RIO, Telstra and Woolworths have adopted targets of 50% or more carbon emissions reductions by 2030. Wesfarmers’ retail businesses (Bunnings, Kmart, Officeworks) are targeting net zero in 2030.

In some areas companies are literally falling over each other to make their businesses green. Aldi, Coles and Woolworths are all moving to 100% renewable electricity for their stores and distribution centres by 2025 or earlier. Charter Hall is looking for its buildings to go net zero by 2025, not 2050.

Overall, we estimate that approximately 75% of Australian ASX/S&P200 companies by market value have adopted net zero, carbon neutral or net positive carbon targets.

But a damaging carbon footprint remains in investment portfolios

Despite this positive progress, Australian and global companies have a long way to go.

Using Plato’s carbon database, we can assess the carbon footprint of leading investment indices. The chart below shows that if an investor placed $US1 million in an ASX/S&P200 index fund, the equity ownership share of those holdings was responsible for annual emissions of over 133 tonnes of carbon dioxide.

The Australian index is far more carbon intensive than the US or MSCI World markets, reflecting Australia’s industry mix, which is highly weighted to materials and energy stocks and relatively lowly weighted to information technology.

Index Carbon Footprint


ASX 200

S&P 500

MSCI World

Carbon Footprint (tonnes CO2e/USD $M invested)

133.66

52.81

87.58

As of June 30, 2021. Source: Plato, FactSet, MSCI, scope 1 and 2 emissions.

Using this information, we can also estimate the carbon footprint of a typical superannuation investment.

According to the latest information from the ASFA’s superannuation statistics, we find that a typical couple aged 60-64 has assets worth around $650,000. Using just the average exposure to listed equities and property, we estimate this equates to approximately 28 tonnes of CO2 equivalent per annum in emissions through their equity ownership of company emissions.

This is larger than the average emissions of typical Australian household, which sits at around 15-20 tonnes.

For perspective, 28 tonnes is equivalent to 63 return Sydney-Melbourne economy flights, 2.8 return economy flights Sydney-London, or 8.4 medium petrol cars driving around 12,000 kilometres per year.

Unlocking a ‘net zero now’ investment portfolio?

Plato has been able to achieve a net zero carbon footprint without using costly carbon credits in the portfolio of our Plato Global Net Zero Hedge Fund. This is through a combination of shorting high carbon emitting global stocks and going long stocks with below average carbon footprints.

There are also a growing number of other low carbon investment alternatives rapidly emerging in the broader listed and unlisted managed funds space.

Why? The sceptics might argue it’s opportunistic, but like the families and corporates, investors (and many investment managers) are growing more and more carbon conscious and the economics are growing more and more attractive.

An insight into the European market illustrates this, and perhaps provides an insight into why going ‘net zero now’ could be so lucrative for investors in the years ahead. Europe is the most advanced economic block when it comes to decarbonisation, so it provides a strong indication of what’s to come for the laggard economies, such as Australia.
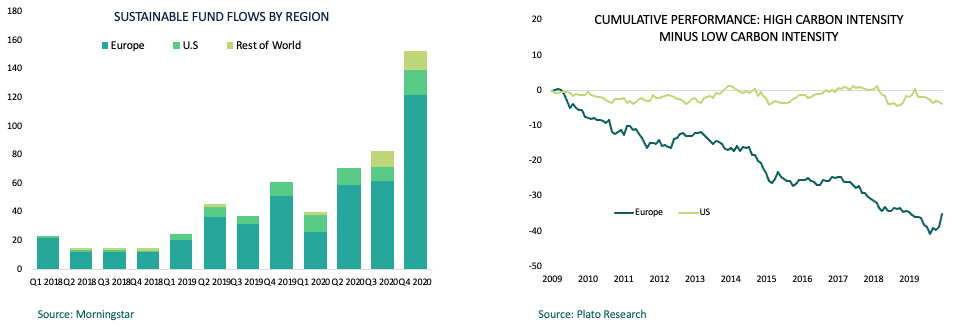
You can see above (left of page), European capital has dominated flows into sustainable funds since 2018. The rest of the world remains markedly behind.

This is no surprise when comparing performance of high carbon intensity stocks versus low carbon intensity stocks in Europe after controlling for sectors. Right of page we see that in Europe high carbon intensity stocks within a sector have underperformed low carbon intensity stocks by cumulative more than 30%.

Remember, Europe has had a price on carbon since 2005. In a regulatory sense it is the most developed market globally when it comes to decarbonisation. This, along with the aforementioned proliferation of flows into sustainable funds has led to that significant outperformance seen by low carbon intensity stocks.

We compare this to the US (light green line) and there is little different between the performance of high carbon and low carbon stocks. However, the rest of the world has no choice but to catch up and we believe a similar market dynamic to what’s occurred in Europe will likely play out across the globe in the years ahead.

Action begins at home

Regardless of what our politicians do, the buck stops with all of us to help limit climate change. When a company or an individual makes an investment decision, be it for a new mine or office building or a new house or car, or even a new appliance, that decision is locking in future emissions for many years.

Indeed, we think the race to net zero will be the most important thematic for investment returns over the next 30 years, but we think the time to reach net zero in your investment portfolio can be now.


Dr Don Hamson is Managing Director at Plato Investment Management. Plato is affiliated with Pinnacle Investment Management, a sponsor of Firstlinks. This article is general information and does not consider the circumstances of any investor.

For more articles and papers from Pinnacle and its affiliates, click here.


  •   26 January 2022
  • 6
  •      
  •   
6 Comments
Joey
January 27, 2022

Let me think about that ... going short a carbon-emitting company is like buying a carbon offset. Doesn't strike me its like planting a tree or installing solar.

Don Hamson
January 29, 2022

Hi Joey. So ok we are not growing trees, but we are punishing high carbon emitters by selling their shares and putting downward pressure on their share prices. We also engage with companies like AGL to encourage them to have a fair dinkum plan to get to net zero. We need to get the companies to reduce their emissions, because there are only so many trees one can plant. If we can help make a company decide to install solar and reduce their emissions that is a win.

AlanB
January 31, 2022

If, as you say, action begins at home, then why haven't you accounted for the significant home gardening services performed by most SMSF trustees (and members). Like planting a tree. Or lots of roses.

James
January 31, 2022

I'd rather Fund Manager's stuck to their knitting and concentrated on getting the best returns for their customers, given the expensive, excessive fees some charge! Don't join the woke brigade!

SMSF Trustee
February 01, 2022

James, fund managers who take this issue seriously ARE focussing on returns for investors. Whether you like it or not, the world is moving against carbon emissions and anyone who owns assets that produce emissions is taking a risk. Don't you want your fundie to manage that risk? Or would you like to be stranded owning the last, worthless, coal mine in Australia?
This has nothing to do with "wokeness" and everything to do with maximising long run returns.

james
February 01, 2022

Last time I checked neither wind, solar, batteries or hydrogen were near to solving the emerging European energy crisis. Merkel's all but killed nuclear and now they burn Russian gas, coal, wood chip and oil. The "cart" is way ahead of the horse at this juncture, so let's respectfully disagree that some fund manager's are going a bit woke as the herd charges to "green" energy (at whatever cost). It doesn't mean I want my fund manager to. As Charlie Munger apparently once said: "Show me the incentive and I'll show you the outcome". The incentive for fund managers is to harness concerned investors and hence create "green, ethical" funds!


Leave a Comment:

RELATED ARTICLES

Big Super’s asset allocation and future headwinds

Why ESG can still play a crucial role in investor portfolios

Mike Murray on watching for the changing narrative

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Higher yields are creating opportunities in global bonds

Bond markets are adjusting to a new reality, but not in the ways investors expect. With markets repricing and capital competing for attention, investors may need to rethink where resilience and opportunity lie. 

Will investors be better or worse off under new housing tax changes?

Housing tax reforms have sparked warnings of market turmoil and promises of greater fairness. But after modelling nearly two decades of property data, the results suggest winners and losers may not be who many investors expect.

Latest Updates

Superannuation

Superannuation’s structural failings

Politicians are fighting over access to super, but they may be arguing about the wrong thing. The system’s three fundamental flaws have been hiding in plain sight for decades, costing Australians far more than they realise.

Planning

The great wealth transfer myth

Why do some families preserve wealth for generations while others struggle to? As the great wealth transfer unfolds, the determining factor is often not the structure of the estate, but the preparation of those who will inherit it.

Investment strategies

What comes after bank hybrids?

For years, bank hybrids have been a cornerstone of portfolio income. With tens of billions of dollars now disappearing from the market, investors face a critical question: what comes next, and are the obvious replacements enough?

Investment insights from the US

What happens when knowledge becomes a commodity? The latest themes emerging from the US tech sector suggest AI could reshape company moats, disrupt incumbents and create winners and losers in unexpected places.

Investing

Can Berkshire thrive without Buffett?

Warren Buffett's departure marks the end of an era. But the more important question for investors is whether Berkshire's culture, discipline and capital allocation framework can survive without the man who built them.

Retirement

The Bengen 4% Rule: Lost in translation

For years, retirees have been told to focus on withdrawal rates. But the real question is far simpler: how many dollars can you safely spend? The answer may be very different from what conventional retirement wisdom suggests.

Interest rates

Super low interest rates came with side effects

For more than a decade, investors lived through an era of near-zero interest rates. With bond yields now surging, it's worth asking whether cheap money solved economic problems, or introduced a much larger set of risks.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.