Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 13

An historical (not hysterical) look at gold

Around the world in the last two weeks, people have rushed retail stores to buy physical gold. Perth Mint has reported sales are at their highest level in five years, and they traded over the weekend to cope with demand. People are queuing across Asian cities in panic-like conditions, while the US mint has been forced to cancel sales of its gold coins. Buyers are responding to the rapid price fall to USD1,322 per ounce in mid-April, the lowest level for two years.

What is most extraordinary is that retail investors usually react to rapid market falls in the opposite way. When equity prices drop, investors usually panic from fear it will fall further. Inflows to managed funds are always at their strongest when the market is at its peak, and outflows at their highest when markets bottom. But something else is happening with gold.
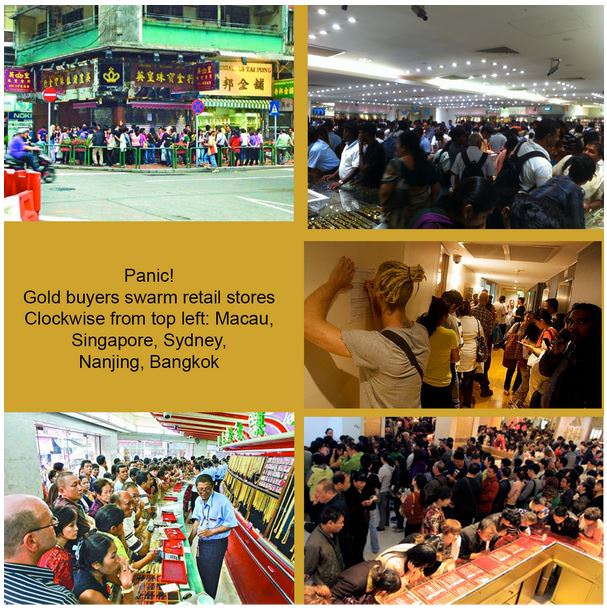

Source: Compiled by Grant Williams of Mauldin Economics from various public sources.

A brief look at gold price history

Most of the time over history, one ounce of gold has been able to buy items worth the equivalent of around USD500 in today’s dollars adjusted for inflation. It has done so for much of the past 2,500 years through many societies. Occasionally the gold price (when measured in paper currencies) surges when paper currencies devalue, but it then falls back again in real terms. If bought below its long run level, gold can provide a hedge against the devaluation of paper, but if bought above the level it is speculation, not ‘investing’. It is not a matter of whether gold represents a store of value or some other safe haven characteristic. For an investor, it is only worth buying when it is cheap.

The gold price reached USD1,900 per ounce on 5 September 2011 in the midst of the US debt ceiling and credit downgrade crises. Since then it has fallen by more than 20%, including a 10% fall on 15 April 2013, triggered by fears that Cyprus and the PIIGS may have to sell their gold reserves to repay debts.

Gold may shoot up to USD4,000 or USD5,000 in one of two scenarios: (a) an extreme left wing outcome resulting in run-away US inflation leading to a breakdown of society; or (b) an extreme right wing scenario with a Tea Party-led Republican government bringing back the gold standard. These scenarios look remote. People who bought gold in the last bubble in 1979-80 are still waiting to get their money back in real terms after inflation 33 years later.
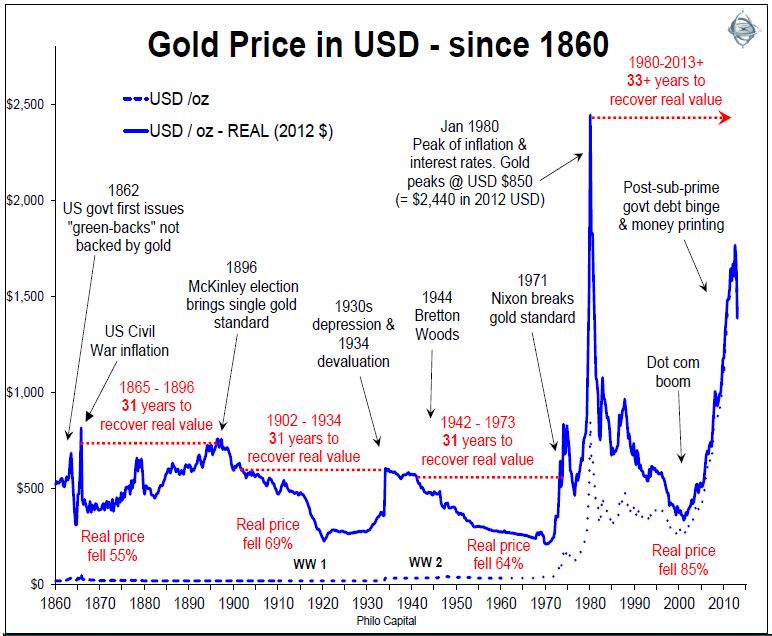
Investors cannot consider gold without also thinking about currencies and inflation, as the three are inextricably linked. Long term holding of gold makes sense as an inflation hedge or as a store of value if bought at or below the long term price around which it has oscillated for thousands of years. However, if paper currencies collapse, the nominal value of gold expressed in paper money terms can rise dramatically. So gold has most appeal if the investor’s home currency is about to experience massive hyper-inflation which destroys the value of paper money, which is unlikely in Australia in the near future. Or since the price of gold is expressed in USD terms, any expected rapid destruction in the value of a home currency may merit purchases of gold.

Of course, profits from short term trading are always possible as a more speculative bet, but long term portfolios are designed to look after long term needs, such as producing income and protecting wealth.

A copy of our comprehensive 2012 study of gold can be found here.


Ashley Owen is Joint CEO of Philo Capital Advisers and a Director of Third Link Investment Managers.


  •   2 May 2013
  • 1
  •      
  •   
1 Comments
scottb
May 03, 2013

"Investors cannot consider gold without also thinking about currencies and inflation."

Indeed. But in considering inflation, Mr Owen has forgotten that governments purposely and systematically understate the amount of actual inflation so as to make it possible for debtors everywhere – and governments are the greatest of all debtors – to repay obligations in a devalued currency, thereby enabling the ongoing operations of a debt and liquidity-based economy. The U.S government reports inflation at about 2.5% (the basis of Mr Owens analysis), but in fact it's most likely significantly higher...close to 10%. Check out Shadowstats.com.

Adjusted for true inflation, gold peaked in 1980 at about $5,000 which would suggest there's some room to the upside today.

And one can't ignore the size of the monetary base today. A look at the the ratio of the St. Louis Adjusted Monetary Base to the price of gold shows it above 2.0 ...almost record levels. All previous gold 'booms' have only stopped when the ratio falls below 0.22. And we are a very long way from that.

And consider this. In January 1980 when gold peaked at $875, the average price for gold for the month was $669. The monetary base in January 1980 was $132 billion, which means it took only 198 million ounces of gold to cover the monetary base. In January 2012 when gold averaged roughly $1,600, the monetary base was $2,750 billion. Thus it would take 1.7 billion ounces to cover the monetary base. To get the same coverage as in 1980, gold would have to be trading at almost $14,000.

Or maybe you can look at it like this. If the US actually has the 8,133 metric tonnes of gold they claim they have in their reserves (World Gold Council - World Official Gold Holdings) and the US used that gold to back the US monetary base, gold would have to rise $9,745 per ounce. Even backing 40% of the monetary base would see gold at $3,900 an ounce.


Leave a Comment:

RELATED ARTICLES

What do fund managers mean by Quality Investing?

1979 US Government defaults: what happened next?

Nassim Taleb on managing investments for rare events.

banner

Most viewed in recent weeks

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Superannuation’s structural failings

Politicians are fighting over access to super, but they may be arguing about the wrong thing. The system’s three fundamental flaws have been hiding in plain sight for decades, costing Australians far more than they realise.

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Does an American retirement rule work for Australians?

The 4% rule has survived decades of scrutiny, but Australia's retirement system changes the equation in ways most overlook. Before accepting or rejecting this rule of thumb, it pays to understand what really drives retirement outcomes.

Latest Updates

Superannuation

Bill Kelty: Super can't solve everyone's problems

One of the key figures behind Australia’s superannuation system reflects on how it began, what has changed, and why some of today’s biggest debates may be asking too much of a retirement savings system.

Investment strategies

Rising yields have put bonds back in business

For the past decade, investors were forced to chase income wherever they could find it. With yields now offering competition to dividends, the new challenge is deciding whether they're still being adequately rewarded for risk.

Strategy

Do you want a bucket with that?

Retirees, advisers and super funds all talk about the bucket strategy as if it's one thing. It's not. The differences can be significant, and some may matter far more than investors realise when markets become volatile.

Investment strategies

What The Odyssey can teach us about valuation discipline

Investment temptations are hard to resist in the moment, but successful investing is not about ignoring compelling opportunities or ideas. For value investors, the smart move is to prepare before momentum clouds judgement.

Shares

Does market concentration really mean more risk for investors?

One of the most closely watched trends in global markets has become a growing source of investor concern in recent years. Whether that concern is justified, however, turns out to be a far more complicated question.

Retirement

Retirement in reality - 8 months in

Health goals, new friendships and lingering questions about identity have dominated this month. The experience has challenged widely held beliefs about purpose, belonging and what it really means to leave work behind.

Shares

Stagnation might be OK at this point

Australia's economic problems are hardly a secret. The more interesting question for investors is whether the stock market is as exposed to those problems as commonly assumed, or whether the picture is more nuanced.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.