Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 579

An intriguing theory explaining persistent LIC discounts

[Editor: the following is an extract from Bell Potter's latest quarterly report on the latest trends in LICs and LITs.]

Paying for the beta

The emergence of trading discounts amongst closed-ended funds has become a challenge for investors and managers alike, with the combination of market rallies and interest rate volatility fueling the growth of trading discounts to historic wide levels for many Listed Investment Companies (LICs). Whilst trading activity for LICs have been volatile, investors look to the relationship between returns from the LIC and the benchmark in determining the dislocation from NTA.

The relationship between LIC and Listed Investment Trust (LIT) returns and the market can be captured through ‘beta’, being a useful measure in understanding the riskiness of an investment. A beta of 1 reflects returns which are just as volatile as the market, with a value greater than 1 indicating greater volatility relative to the market portfolio. The relationship between LIC/LIT beta and its corresponding trading premium or discount over the last three years, is depicted in Figure 1, noting many domestic listed strategies exhibit risk-return characteristics close to their respective benchmarks.
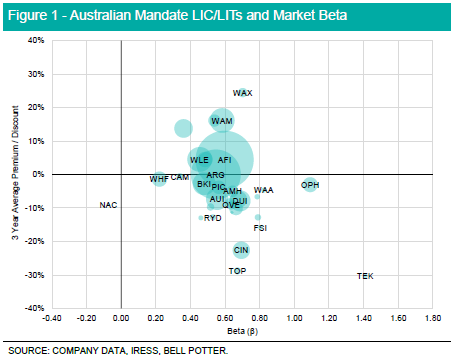
Amongst LICs with a domestic equity mandate, investors continue to preference funds with a benchmark like risk return relationship, highlighted by the majority of LICs capturing a market beta of between 0.5 to 0.8, with larger market capitalisation listed products trading near NTA. Smaller and more concentrated portfolios demonstrate dislocations from the market beta and NTA. This is headlined by the Australian Foundation Investment Company (AFI) and Argo Investments (ARG) which report a 3-year average beta of ~0.6, signifying a reduction in market risk compared to their respective benchmarks.

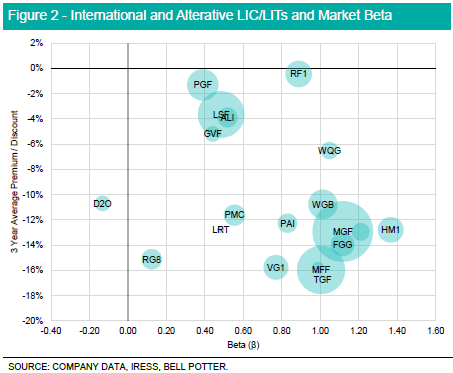
A similar relationship can be inferred amongst international and alternative mandated listed closed ended funds, with the average trading discount for LIC/ LITs closing as beta rises towards 1. Most listed products with this mandate trade on a beta of less than 1, reflecting a return profile which is less volatile than the underlying index. Divergence from NTA is more prevalent in listed products with international and alternative mandates, with markets unable to close trading discounts irrespective of historical return performance. The Regal Investment Fund (RF1) best captures market volatility whilst trading near NTA, reflected by an average beta of 0.89 and underpinned by strong performance in the LITs small company and global alpha strategies over the last 12 months.

The relationship between historical market discounts and beta indicates markets are better able to price index replicating strategies, with trading discounts becoming the result of divergence from the market portfolio. This relationship is best demonstrated with Australian equity mandated LIC/LITs, whilst International and Alternative mandates have less of a defined relationship. Outside of this the flow of additional capital towards exchange traded funds (or ‘ETFs’) has coincided with the recent emergence of trading discounts, with the sector reporting a FUM CAGR of circa 35%. Whist ETFs remain a popular alternative in capturing market returns, similar exposure exists in the LIC/LIT sector given multiple products hold broad market mandates, whilst exhibiting risk-return characteristics similar to the market portfolio, notwithstanding the impact of trading discounts, dividends and manager risk in overall returns.
It's all the same to me

Diversification is key in looking at LICs as investors want to minimize the degree of correlation in returns between assets in order to reduce overall portfolio volatility. Correlation is the degree in which two assets move together, captured by a value between -1 and 1. The higher the correlation between two assets, the closer they move in line with each other, with a value of 1 capturing perfect positive correlation, and a value of -1 capturing perfect negative correlation. In assessing the LIC/LIT market, assets which report a high correlation offer lower diversification benefits when held together in a portfolio, compared to assets which exhibit lower correlation.
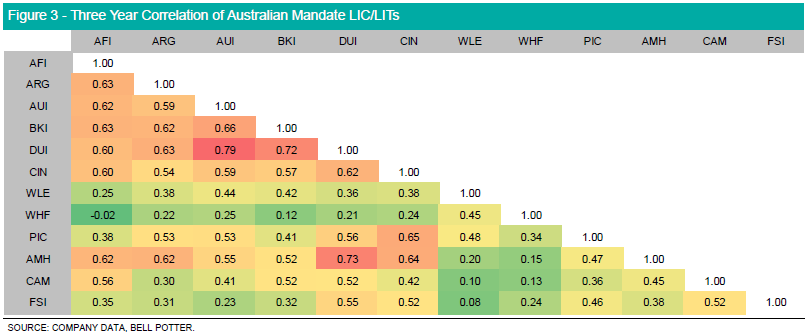
Amongst LIC/LITs with Australian equity mandates, Whitefield Industrials (WHF), Clime Capital (CAM) and Flagship Investments (FSI) exhibit a weak positive correlation against other listed products. The strongest positive correlation is held between Australian United Investment (AUI) and Diversified United Investment (DUI) given both companies share similar investment philosophies. Furthermore, LICs which hold a large cap only mandate report a strong positive correlation given there is often high overlap between underlying portfolio investments.
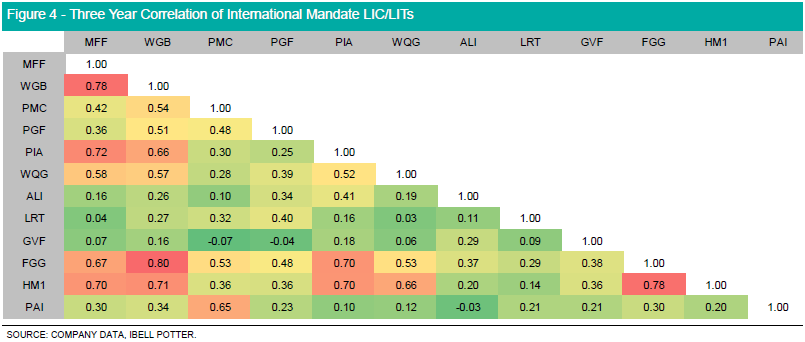
Looking at LIC/LITs with International equity mandates, the Global Value Fund (GVF) exhibits low historical correlation, given returns are driven by the managers discount capture strategy. Together with GVF, both Argo Infrastructure Limited (ALI) and Lowell Resources Trust (LRT) report a low correlation with their peers given their sector specific exposures. Contrastingly, both MFF Capital (MFF) and WAM Global (WGB) demonstrate a return high correlation given both LICs hold similar thematic and geographic allocations in their respective portfolios.

Capital raisings

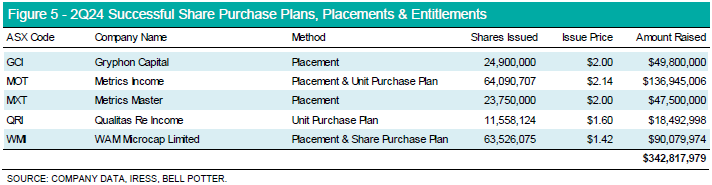
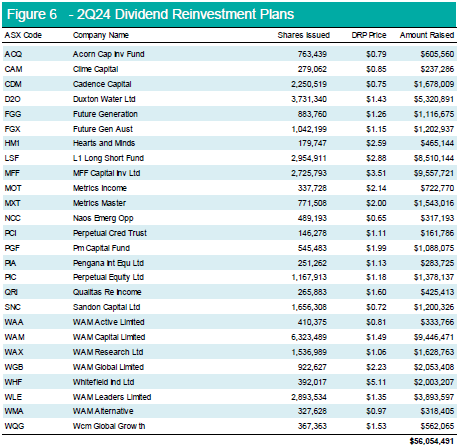
Strong market conditions provided a backdrop for LICs and LITs to raise incremental capital. A total of $398.87m was raised via the secondary market through Dividend Reinvestment Plans (DRPs), Stock Options and Placements.

The majority of additional capital stemmed from fixed income LIT managers on the back of stronger demand from the market, given LITs under this mandate trade at a weighted average premium of 1.48% versus the sector at a 7.33% discount. Managers have taken the opportunity to offer the ability to subscribe to additional units in the trust at NTA, allowing investors to capture value during a period of trading at a premium to NAV. The increased appetite for alternative income strategies comes during an elevated interest rate environment, coupled with shifting appetite from traditional lenders in participating in commercial lending.
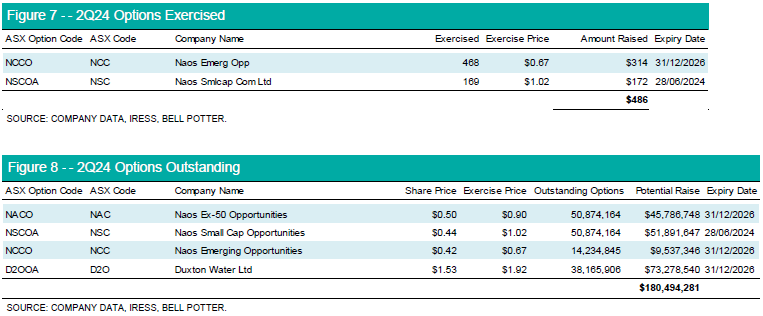
Option exercises were a negligible source of additional capital with most trading deeply out of the money at circa 20-50%.
 

Kion Sapountzis is an Investment Analyst at Bell Potter Securities. This information contains general information only and has been prepared without taking into account your objectives, financial situation or needs.


  •   25 September 2024
  • 5
  •      
  •   
5 Comments
CC
September 26, 2024

but AFI and ARG discounts have blown out to 11% despite their low volatility

PN
September 27, 2024

Thanks for the article, although I'm not sure what to make of it......
I'm an AFI and ARG shareholder, two of our biggest blue chip, conservative, lease volatile LIC's, and they've been trading at a discount for over 18 months, currently at their biggest discounts of +11%...doh.
Love to see the discount start closing

NR
September 27, 2024

re afic and argo - have a look at the buy/ sell spread. i guess newcomers who bought in during covid are now trying to cash out and move to cash/ term deposit. once this cohort is out price should get back to normal. they're silly enough to sell $1 worth of asset for 80 cents.

one of afic's board members recently bought $1million worth - this should give you confidence.

both are now publishing weekly nta which should help also.

AM
September 29, 2024

The article suggests that there is a relationship between premium/discount vs Beta.
However, I can’t see any evidence of that relationship in the top two charts.
Am I missing something here?

GFB
October 04, 2024

As a dividend buyer, I don't really care about the premium or discount on any given day for my LIC holdings. If the fund has coverage for the dividend, then that's what's important to me. Sure, having growth on your capital is nice, but it's the steady and rising DPS that I'm there for.


Leave a Comment:

RELATED ARTICLES

ETFs are the Marvel of listed galaxies, even with star WAR

Finding opportunities in listed global funds

ETF investors adding to portfolios during recent volatility

banner

Most viewed in recent weeks

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Superannuation’s structural failings

Politicians are fighting over access to super, but they may be arguing about the wrong thing. The system’s three fundamental flaws have been hiding in plain sight for decades, costing Australians far more than they realise.

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Does an American retirement rule work for Australians?

The 4% rule has survived decades of scrutiny, but Australia's retirement system changes the equation in ways most overlook. Before accepting or rejecting this rule of thumb, it pays to understand what really drives retirement outcomes.

Latest Updates

Superannuation

Bill Kelty: Super can't solve everyone's problems

One of the key figures behind Australia’s superannuation system reflects on how it began, what has changed, and why some of today’s biggest debates may be asking too much of a retirement savings system.

Investment strategies

Rising yields have put bonds back in business

For the past decade, investors were forced to chase income wherever they could find it. With yields now offering competition to dividends, the new challenge is deciding whether they're still being adequately rewarded for risk.

Strategy

Do you want a bucket with that?

Retirees, advisers and super funds all talk about the bucket strategy as if it's one thing. It's not. The differences can be significant, and some may matter far more than investors realise when markets become volatile.

Investment strategies

What The Odyssey can teach us about valuation discipline

Investment temptations are hard to resist in the moment, but successful investing is not about ignoring compelling opportunities or ideas. For value investors, the smart move is to prepare before momentum clouds judgement.

Shares

Does market concentration really mean more risk for investors?

One of the most closely watched trends in global markets has become a growing source of investor concern in recent years. Whether that concern is justified, however, turns out to be a far more complicated question.

Retirement

Retirement in reality - 8 months in

Health goals, new friendships and lingering questions about identity have dominated this month. The experience has challenged widely held beliefs about purpose, belonging and what it really means to leave work behind.

Shares

Stagnation might be OK at this point

Australia's economic problems are hardly a secret. The more interesting question for investors is whether the stock market is as exposed to those problems as commonly assumed, or whether the picture is more nuanced.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.