Given the near impossibility of timing the market’s highs and lows to perfection, investors have to expect that, even if they get the general direction of travel right, their trades will be either too early or too late. Which is better?
Usually late to the party
I believe it’s better to be early even though human nature ensures that most of us have a tendency to come late to the party. The fear of losing money in the short term, which is the destiny of the early investor, is a powerful disincentive to pre-empt the market. Far easier to wait for confirmatory signals from the market and/or the economy before we take the plunge. Easier but costly.
If you wait until it is clear the low point has been passed, the temptation to keep waiting for a pull-back to a more favourable price is irresistible. Many investors sit on the sidelines while others enjoy the recovery. If you had taken the pain of an initial loss, you would have been in at the bottom and sitting comfortably as the rally gathered pace.
I think we are precisely at this 'shall-I-shan’t-I' moment in the market cycle for the two main asset classes, shares and bonds. I accept that my optimism may be a early on both counts but I’m prepared to live with that. I think by the end of next year, we may well look back on a period of positive returns for both investments.
It's not easy to commit on the back of losses
That may look eccentric nine months into what will probably turn out to be the worst year for shares since the financial crisis and the worst for balanced funds, holding both assets, perhaps since the 1960s. The idea that the two act as diversifiers for each other has been tested to destruction this year. Persistent inflation and rising interest rates have damaged for bonds, while shares have tumbled in anticipation of recession and falling earnings.
The case for investing in bonds looks counter-intuitive in the week that the Bank of England has confirmed that its sticking plaster measures to prop up the UK’s fixed income markets will draw to a close. Forced sales by pension funds to plug holes in too-clever-by-half risk management strategies have driven bond yields higher than inflation.
That’s bad news for anyone holding those bonds but for anyone looking for an entry point, it’s a gift. Bonds are looking more interesting than they have done for many years. Even where the rise in yields has not received this liability-driven boost, the adjustment to a world of higher inflation and interest rates has largely happened now. And the additional yield premium on corporate bonds has widened too. I believe, for the first time in a while, investors are being rewarded for the greater risk of lending to a company rather than a government.
Bonds finally offering investible yields
So, investors can now lock in a decent yield. Even better, as we head towards recession on both sides of the Atlantic, they can also look forward to a potential capital gain in due course if the Fed and other central banks take their foot off the monetary gas and pivot to lower interest rates to support a slowing economy. We are not there yet. The peak in the interest rate cycle probably won’t come for another six months or so but before that point actually arrives bond yields will fall in anticipation and their prices will rise.
If identifying the low point for bonds looks a bit hasty, it looks even more so for stock markets as we approach what by all accounts is going to be a tricky earnings season. We should expect plenty of gloomy commentary about falling demand and unhelpful currencies (there’ll be a lot of talk about the negative impact on US companies of the strong dollar, for example).
But just as we expect the bond market to pre-empt the peak in the interest rate cycle, so too will the stock market move ahead of the trough in corporate earnings. The market and the earnings cycle are not the same. They march to a different beat and the gap between the two can be as much as six months or so. Prices move first and waiting for the data to confirm the market move can be expensive.
Not quite there yet
So far in 2022, the fall in stock markets has been caused by lower valuation multiples. At the beginning of the year, investors were paying 23 times expected earnings but that multiple is now about 15. But a few weeks of disappointing results announcements could easily see that fall to 13 or so. That would imply an S&P500 of closer to 3,000 than today’s 3,600. Here's the YTD movement of the S&P500, showing it has given up 23.3% since 1 January 2022.
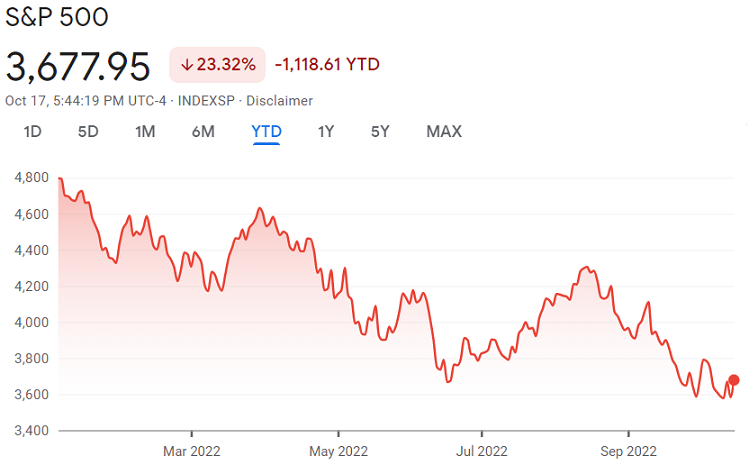
Source: Google Finance
If you think you are smart enough to time your re-entry back into the market, then by all means sit on your hands for a bit longer. However, the early weeks of the pandemic showed how quickly markets can regain lost ground when they get a sniff of recovery and interest rates start to fall again. You won’t care too much if you got in at 3,300 or 3,500 if the US benchmark is back above 4,000 again.
You will care if you are still waiting in vain for a better entry point.
Some of the wisest advice for investors is not to get more bearish as the market falls. The time to get interested is when everyone else is focused on the grim economic and corporate outlook. And if you are lucky enough to get double helpings in both the bond and stock market so much the better. Time to grit your teeth and start to prepare for the upturn. Even if it hurts in the short term.
Tom Stevenson is an Investment Director at Fidelity International, a sponsor of Firstlinks. The views are his own. This document is issued by FIL Responsible Entity (Australia) Limited ABN 33 148 059 009, AFSL 409340 (‘Fidelity Australia’), a member of the FIL Limited group of companies commonly known as Fidelity International. This document is intended as general information only. You should consider the relevant Product Disclosure Statement available on our website www.fidelity.com.au.
For more articles and papers from Fidelity, please click here.
© 2021 FIL Responsible Entity (Australia) Limited. Fidelity, Fidelity International and the Fidelity International logo and F symbol are trademarks of FIL Limited.