Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 416

How the Intergenerational Report misleads on super

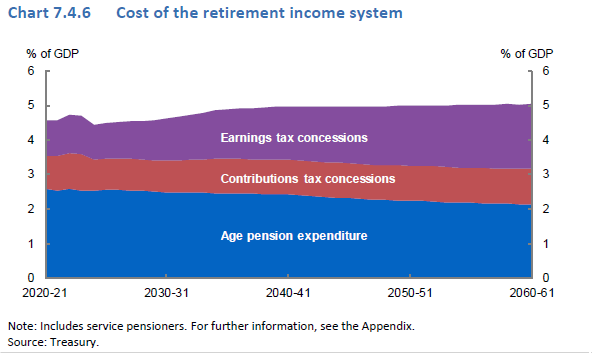
The latest Intergenerational Report (IGR) has reignited the debate about the value of the current superannuation tax concessions by projecting that the cost will rise from 2% of GDP in 2020-21 to 2.9% in 2060-61.

In contrast, the costs of the age and service pensions are projected to fall from 2.7% of GDP in 2020-21 to 2.1% in 2060-61.

In other words, the tax concessions will be worth more than the cost of the pensions, as shown in the following chart from the IGR. This finding is not new as the recent Retirement Income Review found that by 2047, the cost of superannuation tax concessions is projected to be greater than the cost of the age pension as a percentage of GDP.

The IGR raises the valid question as to whether the current superannuation concessions are worth it.
Direct cost versus estimate

Before answering that question, let’s recognise that in comparing the pension costs and the tax concessions we are really comparing apples and oranges. Let me explain.

The age and service pensions paid to some Australians each year are a direct cost to the federal budget, in the same way as health and education costs represent a direct expenditure.

In contrast, the super tax concessions are estimates as they do not represent a direct cost to the budget. Rather, less taxation is collected due to the concessions. The two major concessions are in respect of:

  1. Concessional contributions, including the Superannuation Guarantee (SG), where the tax paid by most Australian workers is about 15% less than their marginal tax rate.
  2. Investment earnings received by the super fund where the tax rate is 15% in the accumulation phase and zero in the pension phase.

The value of the super tax concessions estimate the tax forgone as a result of these concessions. It compares the tax actually paid with the tax that would have been paid if both the concessional contributions and the investment earnings were taxed at each individual’s marginal tax rate.

This approach is reasonable when estimating the value of the concessions for this year. However it is unreasonable to use this approach for future years as:

  • It does not allow for the reduced investment earnings if the concessional contributions and investment earnings were to be fully taxed.
  • It ignores any behaviour change that would occur if the tax concessions did not exist. As the Retirement Income Review noted, individuals may choose alternative savings vehicles. The Review calculated that at the end of four years, the earnings estimate is 14% lower because the earnings on these alternative tax-preferred vehicles are subject to lower marginal tax rates than those used in the original estimate. One can only estimate what the difference would be over decades.

Hence, pension costs are known but super tax concessions are based on a series of assumptions and benchmarks, which may be debated. The value of the concessions does not equate to future revenue gain if the current concessions were abolished.

An investment in the future

Another important difference, is that the super tax concessions are about the future. In effect, it represents the government making a contribution or investment today for the future. As we invest in education for the benefit of our future society, so it is with superannuation. Employers, individuals and governments invest money today for the benefit of both future retirees and future taxpayers.

While the benefit for future retirees may be obvious, the benefit to future taxpayers is equally important. As noted above, the cost of the age and service Pensions is reducing, when expressed as a percentage of GDP, even though we have an ageing population. As the IGR noted,

"As younger generations retire with greater superannuation savings, the total proportion of older Australians receiving the age pension will continue to decline.”

Indeed, a Senate Committee has previously recommended that this future saving should be calculated but this has never been completed.

The age pension costs and super tax concessions represent two very different forms of government support for our retirement income system. As Treasury notes, the value of super tax concessions “are not estimates of the revenue increase if a variation to the tax benchmark were to be removed.” Adding these estimates of an uncertain cost with a known cost of the current pensions is both unhelpful and misleading.

Finally, it should be noted that regardless of how the cost is calculated, the government’s financial support of the overall retirement income system does not exceed 5% of GDP for the next 40 years. That is financially sustainable as this figure is approximately half the average projected level of public expenditure on pensions for OECD countries in 2050. We are indeed well placed.

Let’s recognise that both the age pension and superannuation tax concessions represent important elements within our retirement income system. Let’s have some stability by not subjecting either to significant change in the forthcoming years which will also improve community confidence in the overall system.


Dr David Knox is a Senior Partner at Mercer. See www.mercer.com.au. This article is general information and not investment advice, and does not consider the circumstances of any person.


  •   14 July 2021
  • 9
  •      
  •   
9 Comments
Mart
July 14, 2021

David - thank you ! Your last paragraph says it all: stability in what is, overall, a pretty good public and private mix of solutions to retirement is what is needed. Additionally I think one of your key observations in the article is that if (or when !) politicians tinker with Super (or other savings structures) the result is people immediately assess the impact and look to see whether they'd be better off investing / saving elsewhere. This is often accompanied by media commentary / hysteria that whips up a storm and gets people worried (witness the Labour franking credits proposals at the last election, the backlash they provoked, and the numerous articles in Firstlinks that demonstrated the real impacts rather than the bluster / spin). As Charlie Munger would say "show me the incentive and I'll show you the outcome". I do fear, however, that Super is now such a big pot financially that governments of any colour won't be able to keep their mitts off it ......

Rob
July 14, 2021

David - there is of course another big difference. The Superannuation "pot" is real and tangible money invested vs the Aged Pension "pot" which is a "promise to pay" with next to nothing behind it in terms of Capital. The question is who do you trust in your old age - some future Govt or your own Savings? Personally - no brainer!

Lisa
July 14, 2021

I wonder if the government has also assessed the amount of tax revenue it is likely to receive from those who don't take all their superannuation out of the system being falling off the perch. A potentially huge tax windfall for the government and essentially a death tax.

DK
July 14, 2021

Does the (tax concession vs gov pension expenditure) make any adjustment for beyond any given year? ie concede more in tax in year 1 but the economy gains more in future years by people spending (and paying more taxes) more in the economy, from their super savings compared to what they would have from the pension, in future years?

James
July 14, 2021

Unfortunately, along with death and taxes, there will be further (adverse) changes to superannuation!

Dudley.
July 24, 2021

'Age Pension for all Age Eligible - including those who paid for it.'

Eliminate the Age Pension Income and Asset Tests - and thus eliminate the Asset Sour Spot. Make every Spot sweeter than the one before.

Revenue neutral with minor changes in Age Pension pay rate and continuing Superannuation Guarantee rates.

Chris
July 25, 2021

We ALL "paid for it"; the hackneyed phrase that "I paid taxes all me life" does not make boomers - or anyone - "more special" than any other generation. The problem is that when Gen X (and everyone else after them) retire, it will be so low - poverty line wages - that you won't want it, even if you qualify for it, or won't qualify for it because of your super. Answer - "should have saved more for your retirement" will be the new normal.

Hence, all these people bleating that they are 'self-funded' when really, they are having an each way bet with their super and a part State pension are not. Gen-X will be the first, REAL self-funded retirees, out of necessity.

Dudley.
July 26, 2021

Eliminating the Age Pension Income & Asset Tests, hastens the day when 'all' retirees become self funded.

At the moment, the Age Pension eligibility rules result in:
. SweetSpot = full Age Pension + returns and drawdown on assets of ~$401,500 (> full Age Pension).
. SourSpot = no Age Pension + returns and drawdown on assets of ~$884,000 (< full Age Pension).
.SolaceSpot = no Age Pension + returns and drawdown on assets of ~$1,500,000 (= full Age Pension).

In addition, home is excluded from Assets Test.

Result? Near retirement, plough every $1 of assessable assets in excess of $401,500 into home and "go on the pension". The inverse of 'all' retirees being incentivized to be self funded. Perverse.

Minor tweaks would make the system revenue and cost neutral.

Trevor
April 15, 2022

To Chris :"Who pays more money in taxes? ATO says : "The top 10 percent of earners bore responsibility for over 71 percent of all income taxes paid and the top 25 percent paid 87 percent of all income taxes." [ i.e. 75% paid only 13% of the tax collected ! ] ATO says : " The top 1 percent (taxpayers with AGI of $546,434 and above) earned 20.1 percent of total Adjusted Gross Income in 2019 and paid 38.8 percent of all federal income taxes. [ Almost 40% paid by the top 1%...That's generous ! ] In 2019, the top 1 percent of taxpayers accounted for more income taxes paid than the bottom 90 percent combined." Chris : What this means is that the vast majority of Australians receive more in benefits than they ever pay in tax. 


Leave a Comment:

RELATED ARTICLES

Demographic destiny: a snapshot of Australia in 40 years

Superannuation’s structural failings

The overlooked driver of energy inflation

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Higher yields are creating opportunities in global bonds

Bond markets are adjusting to a new reality, but not in the ways investors expect. With markets repricing and capital competing for attention, investors may need to rethink where resilience and opportunity lie. 

Will investors be better or worse off under new housing tax changes?

Housing tax reforms have sparked warnings of market turmoil and promises of greater fairness. But after modelling nearly two decades of property data, the results suggest winners and losers may not be who many investors expect.

Latest Updates

Superannuation

Superannuation’s structural failings

Politicians are fighting over access to super, but they may be arguing about the wrong thing. The system’s three fundamental flaws have been hiding in plain sight for decades, costing Australians far more than they realise.

Planning

The great wealth transfer myth

Why do some families preserve wealth for generations while others struggle to? As the great wealth transfer unfolds, the determining factor is often not the structure of the estate, but the preparation of those who will inherit it.

Investment strategies

What comes after bank hybrids?

For years, bank hybrids have been a cornerstone of portfolio income. With tens of billions of dollars now disappearing from the market, investors face a critical question: what comes next, and are the obvious replacements enough?

Investment insights from the US

What happens when knowledge becomes a commodity? The latest themes emerging from the US tech sector suggest AI could reshape company moats, disrupt incumbents and create winners and losers in unexpected places.

Investing

Can Berkshire thrive without Buffett?

Warren Buffett's departure marks the end of an era. But the more important question for investors is whether Berkshire's culture, discipline and capital allocation framework can survive without the man who built them.

Retirement

The Bengen 4% Rule: Lost in translation

For years, retirees have been told to focus on withdrawal rates. But the real question is far simpler: how many dollars can you safely spend? The answer may be very different from what conventional retirement wisdom suggests.

Interest rates

Super low interest rates came with side effects

For more than a decade, investors lived through an era of near-zero interest rates. With bond yields now surging, it's worth asking whether cheap money solved economic problems, or introduced a much larger set of risks.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.