Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 366

The asymmetric value of gold for Australian investors

Australia is known as the ‘lucky’ country. Our attractive weather and natural resources are some of the many positive attributes of the nation. Currently, global positioning away from the rest of the world’s problems, especially in the age of COVID-19, could be viewed as the most important health risk mitigant for the near future.

There's another benefit in investing. Unhedged exposure to gold, that is, an Australian investing in gold without hedging its USD price (Gold/AUD), provides attractive properties for portfolio risk management including equity market and inflation hedges. Further, for portfolios that have a focus on re-balancing as an added source of return, equities versus gold provides an attractive pair to harness volatility.

For lucky Australian investors, gold relative to the Australian dollar can be a powerful addition for equity-heavy portfolios.

Inflation and currency debasement

Over the past several months as central bankers have rushed to provide unprecedented liquidity and balance sheet expansion, a growing consensus is emerging around gold for its ability to protect portfolios from currency devaluations and to provide a stable store of value.

Gold continues to make new all-time highs against many global currencies, including the Australian dollar.

An expanding list of recognised names including Paul Singer, Ray Dalio, Stanley Drunkenmiller, Crispin Odey, and Paul Tudor Jones have pointed to their increased gold positioning as a way to protect wealth from potential consequences of global government monetary and fiscal actions.

While inflation has so far only shown up within financial asset prices, the level of unprecedented intervention from monetary and fiscal policy may spill into the real economy. Central banks have showcased their game-plan with seemingly limitless appetite for expansion as the potential solution to a massive global debt overhang and global economic weakness.

Gold and other ‘real assets’ with scarcity value tend to perform well in inflationary periods and diversified exposure to inflation hedging may prove to be prudent if investors lose confidence in the global central bank playbook and their ability to control the inflation genie once out of the bottle.

Protecting future purchasing power and real returns should be in focus.

Gold/AUD as equity market protection

While physical gold is a non-yielding asset, many still view gold as a currency, albeit one with limited ability to print like fiat currencies.

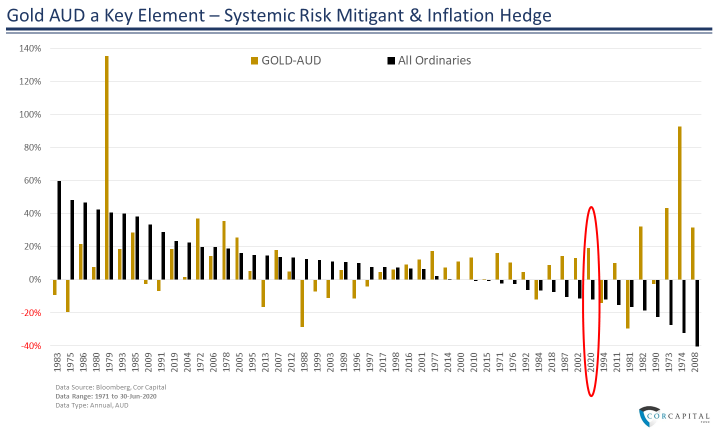
The gold price is often quoted against the US dollar. However, for Australian investors using Australian dollars for their holdings in gold, the Gold/AUD (i.e. gold in AUD terms) has held an asymmetric relationship with equities, providing attractive protection qualities for an equity portfolio in severe market stress events.

Figure 1 displays calendar year performance of All Ords Index and corresponding Gold/AUD ranked in descending order of equity market performance.

Figure 1
Source: Cor Capital P/L

For six months ending 30 June 2020, the All Ordinaries Index fell by -11.8% whilst Gold/AUD gained +19.4% over the same period.

Similarly, during most of the major equity market selloffs, Gold/AUD typically provides relief and negative correlation. Notably, in periods of both equity falls and high inflation, Gold/AUD has provided protection for an equity portfolio, such as during the 1973-1974 equity market crash driven by Bretton Woods and the oil crisis.

Gold typically provides ‘safe haven’ resilience while the Australian dollar tends to weaken with risk assets. In severe market sell-offs, Gold/AUD has often provided a boost when needed.

Importantly, in periods of rising equity markets, Gold/AUD has not held this negative correlated relationship, granting Australians an attractive put against equities with a limited drag in an upward moving equity market. In fact, over many periods both gold and equities rise together.

Harnessing volatility through portfolio re-balancing

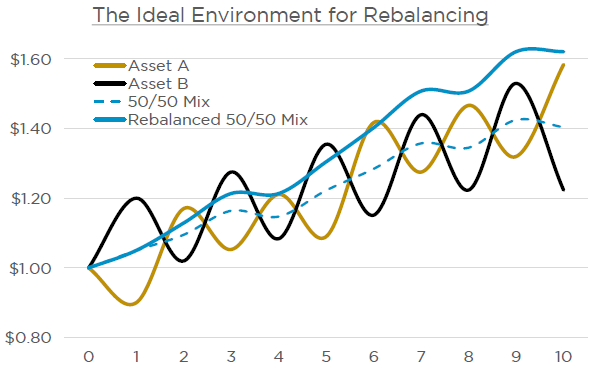
Within portfolios that regularly re-balance for added return, the ability to combine volatile but uncorrelated assets in constantly re-balanced proportions can add substantially to overall portfolio growth. This is well researched in academia and employed by Melbourne based multi-asset manager Cor Capital.

Normal volatility is harnessed through the trimming of winners and topping up of relatively poor performing assets (buy low/sell high) for added return relative to passive asset allocation. Further, as volatility increases the opportunity set increases.

Figure 2 depicts the stylised scenarios where re-balancing can add to static asset class return.

Figure 2
Source: Cor Capital P/L

Historically, equities and Gold/AUD have held a negative relationship in falling equity market periods with low correlation in all periods. Both assets have recorded roughly mid-teen (15% annually) long term volatility, creating an attractive pair of assets to harness normal volatility between the pairs.

Equity-centric portfolios have the potential to hedge for extreme events, protect future purchasing power and earn a unique source of return without taking on more equity or credit risks. Exposure to unhedged gold in Australia is readily available, for example, through unhedged gold ETFs listed on local exchanges. 


Michael Armitage is Director of FundLab Strategic Consulting ([email protected]). This material is intended to provide background information only and does not purport to make any recommendation upon which you may reasonably rely without further and more specific advice. Past performance is not a reliable indicator of future performance, and no representation or warranty, express or implied, is made regarding future performance.


  •   15 July 2020
  • 8
  •      
  •   
8 Comments
Lyn
July 17, 2020

Very interesting article, also read your historic articles re gold today. Why do so few readers comment when gold is the subject? I find it fascinating there are few reader comments re Gold articles as I would love to hear opinions which may be pertinent.
The subject of rebalancing to include gold, interests me. Had I not dipped my toe again into a gold miner (tho not direct gold) a year ago, my portfolio would be far worse at end of Yr 2020 after Covid crisis but I was a "lucky" person who rebalanced after a gain elsewhere so was in position to rebalance at right price with a gold miner I'd not touched for years despite previous gains with same miner. I re-balance often as I find it yields a better return each year, to take gains when there & pick up a bargain elsewhere. Yes it takes a lot of time, but time yields return. I have no doubt our world will return to wanting to hold Gold in any form at any price & why Australia is lucky. It does not have to be Direct/Physical Gold in my experience. In time, increasing Gold price is reflected in miner's share price so anyone who ignores gold does so at own peril whether held Direct or as shares.

Owen
July 18, 2020

Agreed Lynn, about how the gold hoarders always remain quite, that in-itself says it all.

Physical gold at the moment is almost unavailable through the Perth Mint (world renowned for quality) as a example, and if you are not a fan of someone else "playing" with your money through a ETF the other obvious choices are small gold companies who've have mining leases but the price of gold didn't make it's mining viable, until now. Because of this the micro companies are able do capital raising against the "gold in ground" needed to go to mine stage, or are being brought out by the bigger boys = due diligence on the right small gold miners = massive gains since March.

I probably didn't use enough long words combined with charts etc to make this sound sensible, probable and profitable.

Lyn
July 18, 2020

Hi Owen, I understood you, no big words needed as long as one can do numbers--much more important! L.

Dan
July 19, 2020

Nice article. Thank you. Something I've been wrestling with... I already have a weighting of around 15% to gold in my portfolio. I want to dial that up to around 20%. At the moment, it's all unhedged and majority physical + some unhedged gold + gold miners ETF exposure.

I understand there's a positive correlation between gold price + equities + AUD/USD in a rising equity market. But when equity markets tank (i.e. March 2020) AUD/USD trends down but gold price negatively correlates up

Now, that almost feels like a base case: a) equities remain volatile but trend up with increased money printing asset price inflation. Basically, markets continue to be manipulated and artificially inflated. b) gold trends up, possibly explosively to the upside, due to a number of factors (i.e. bond yields undermine 60/40 portfolios, fiscal policy/ UBI leads to inflation/ monetary policy blatantly chases inflation). If a) and b) play out together, then it's quite possible that AUD also strengthens against USD. This being so, my gold gains would be negated.

My question: is it wise to maintain a position in 100% unhedged gold/ gold miners as an Australian? If not, how should one determine the ratio of hedging? A simple solution might be to hedge gold ETF + gold miners ETF positions that are currently unhedged with hedged alternatives (i.e. tickers: MNRS and QAU).

Michael Armitage
July 25, 2020

Dan. The article highlighted the asymmetric relationship. Gold/aud historically was big defender in equity sell off. - not correlated in up equity market. You may be correct. gold/usd may be stronger than gold/aud on any given window. However, will likely be less protective in the downside, in a large equity market sell off USD tends to out perform AUD.
For portfolios that are already more equity centric , Gold/Aud may be more defensive. Further, for portfolios that are regularly rebalancing, the more pronounced negative correlation of gold/aud creates more opportunities.

Stephen
July 19, 2020

I am intrigued by the chart on the ideal environment for rebalancing. It shows a 50/50 mix and a rebalanced 50/50 mix. I am interested because I am a keen student of rebalancing and have just re-read roger gibson’s book on asset allocation. It is the best book I can find on the subject and he advocates using commodities, including gold as an essential part of the mix

Anyway i wonder if you could explain the difference between the 50/50 mix and the rebalanced 50/50 mix. My understanding is that a 50/50 mix is rebalanced anyway so the two charts should be the same

The rebalanced 50/50 mix looks very impressive and Gibson does show that a rebalanced portfolio can show a higher return than the average of the parts.

michael armitage
July 19, 2020

Hi Stephen , the stylised chart indicates an ideal scenario for rebalancing two assets that are not correlated relative to holding a static 50/50 mix. Added attribution is gained from taking profit from winner/ topping up underperformer along the way, when regularly rebalancing back to target..

Bruce
August 26, 2020

Good article thank you.
I'm in a similar position to Lyn. Sold about 2/3 of my stocks in December 19. Then 'bang' we have a pandemic.
I dived into gold even though I already had a little. So now I'm 2/3 gold, GDX, PMGOLD, and a few miners.
A little bit of luck which helps but now I'm a good 15 p/c ahead at the same time being very defensive.
Bruce


Leave a Comment:

RELATED ARTICLES

Is gold a growth or defensive asset?

Gold: should you own the metal or the miners?

The new capital gains tax trap for your portfolio

banner

Most viewed in recent weeks

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Superannuation’s structural failings

Politicians are fighting over access to super, but they may be arguing about the wrong thing. The system’s three fundamental flaws have been hiding in plain sight for decades, costing Australians far more than they realise.

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Does an American retirement rule work for Australians?

The 4% rule has survived decades of scrutiny, but Australia's retirement system changes the equation in ways most overlook. Before accepting or rejecting this rule of thumb, it pays to understand what really drives retirement outcomes.

Latest Updates

Superannuation

Bill Kelty: Super can't solve everyone's problems

One of the key figures behind Australia’s superannuation system reflects on how it began, what has changed, and why some of today’s biggest debates may be asking too much of a retirement savings system.

Investment strategies

Rising yields have put bonds back in business

For the past decade, investors were forced to chase income wherever they could find it. With yields now offering competition to dividends, the new challenge is deciding whether they're still being adequately rewarded for risk.

Strategy

Do you want a bucket with that?

Retirees, advisers and super funds all talk about the bucket strategy as if it's one thing. It's not. The differences can be significant, and some may matter far more than investors realise when markets become volatile.

Investment strategies

What The Odyssey can teach us about valuation discipline

Investment temptations are hard to resist in the moment, but successful investing is not about ignoring compelling opportunities or ideas. For value investors, the smart move is to prepare before momentum clouds judgement.

Shares

Does market concentration really mean more risk for investors?

One of the most closely watched trends in global markets has become a growing source of investor concern in recent years. Whether that concern is justified, however, turns out to be a far more complicated question.

Retirement

Retirement in reality - 8 months in

Health goals, new friendships and lingering questions about identity have dominated this month. The experience has challenged widely held beliefs about purpose, belonging and what it really means to leave work behind.

Shares

Stagnation might be OK at this point

Australia's economic problems are hardly a secret. The more interesting question for investors is whether the stock market is as exposed to those problems as commonly assumed, or whether the picture is more nuanced.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.