Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 509

Druckenmiller on the biggest mistake in the history of the Fed

At the 2023 Sohn Investment Conference in the US on 9 May 2023, Duquesne Family Office CEO Stanley Druckenmiller spoke about the US Federal Reserve’s actions in the last two years and its impact on investing conditions. The entire interview went for over an hour, but we have selected these highlights.

***

I (recently) read Edward Chancellor's The Price of Time. As you know, I've been saying for years that my observation was the worst economic outcomes tended to follow asset bubbles. I was only looking at the past 100 years or so. Chancellor's book is a real tour-de-force, and it describes how this has been going on for over 500 years. Basically, every time we've had interest rates below 2% going back 500 years, it's been followed with a difficult economic time.

I think it was actually just a little over two years ago, I went on national television and said we had monetary policy that was the most reckless and extreme relative of the economic circumstances I had ever seen. And at that time, inflation was 2.5%. You had a booming economy, we're coming out post-COVID and it was clear post-vaccines that we were on our way to maybe the most rapid recovery I have seen in my lifetime.

I was not surprised about a year later when inflation reached 9%. I was not surprised that SPACs went crazy, Bitcoin went crazy, Dogecoin went crazy, equities went crazy. What I was surprised by was that for the next year, while all that happened, Jerome Powell’s Fed (Federal Reserve, the US central bank) continued to have their foot on the gas, they continued to buy US$120 billion of bonds a month while rates were zero. This obviously led to everything I just described.

Then realising they have probably made the biggest mistake in the history of the Fed, they slammed on the brakes. They raised rates 500 basis points (5%) in the last year. We know historically, two things happen.

Number one, the worst economic outcomes tend to follow too easily-engineered asset bubbles. And number two, big maxim in my business is Don't Fight the Fed.

So I'm sitting here staring in the face at the biggest asset and probably the broadest asset bubble - forget that I've ever seen that I've ever studied - and it went on for 10 or 11 years and then as the grand finale the government spent US$5 trillion on COVID and the Fed financed 60% of it.

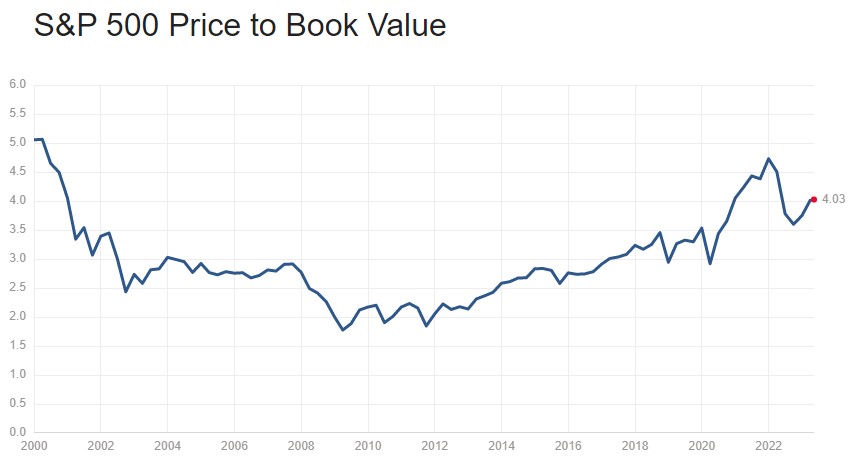
(Editor note: As an example of a broad asset bubble, consider this chart, sourced from Multpl, of the S&P500 Price to Book Value ratio. It has only been higher in this period during the dotcom era of 2000 and the Fed-induced free money and loose monetary policy until 2022. Book value is the company's value in its financial accounts determined by subtracting its liabilities from the value of its assets. This exuberance comes at a time of rising interest rates, recession threats and tightening of bank lending).
As I just described, now we have a big hike in interest rates. It's hard to look at that constellation of factors, know that we've only had a few soft landings since 1950 and all of them were preceded by what I would call proactive rather than reactive Fed policy, and believe we're going to have a soft landing. One never knows. But if you're just looking at the odds, they're very tough. In terms of the timing, I have left much less certainty on that than I do on whether we're going to have a hard landing or a soft landing.

The timing is difficult, but I will say in our shop we tend to use anecdotal information a lot. It's somewhat mixed. Housing, which has tended to lead historically, is actually fairly robust. Travel and restaurants and stuff like that are fairly robust. But trucking, which has been a guiding light for my firm in terms of economic forecasting with a six-to-eight-month lead time, is extremely weak. We're hearing bad anecdotes from retail. The banking problem we always knew.

Given what I've already described, there were going to be bodies out there. When you have free money, people do stupid things. When you have free money for 11 years, people do really stupid things. So the stuff under the hood is starting to emerge. Obviously, the regional banks recently, we had Bed Bath & Beyond. But I would assume there's a lot more bodies coming. The median regional bank has 43% of their loans in commercial real estate, about 40% of that in office. We've had this huge change in lifestyle due to COVID. Number one, the great resignation and number two people aren't going to the office. So we have actually a higher vacancy rate than we had in 2008.

I put all that together and I look also at the inverted yield curve. The timing is sort of third, probably fourth quarter of this year, first quarter of 2024. I wouldn't be surprised if the bean counters a year from now - as they tend to do backward looking - that things started (to go bad) sometime in the second quarter.


Stanley Druckenmiller is Chief Executive Officer and Chairman of his Duquesne Family Office. He made his reputation as an astute asset manager from 1988 to 2000 when he was lead portfolio manager for George Soros's Quantum Fund. The full Sohn Conference interview is linked here. This extract is general information and does not consider the circumstances of any investor.


  •   17 May 2023
  • 1
  •      
  •   

RELATED ARTICLES

The world's about to hit a brick wall

US rate rises would challenge multi-asset diversified portfolios

Central banks have lost the plot

banner

Most viewed in recent weeks

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

Testamentary trusts have secured the CGT exemption

Treasury’s latest CGT reform draft delivers a win for testamentary trusts and deceased estates, exempting estate-derived gains from the 30% floor. However, questions on death and divorce rollovers remain unresolved.

Meg on SMSFs: What do we think about reversionary pensions these days?

Reversionary pensions have long been a staple of SMSF estate planning, but are they still the best option? Meg Heffron revisits a once-clear favourite and asks whether changing super rules have shifted the balance.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

How does the 4% rule stack up?

The 4% rule has long been retirement's gold standard. But after a difficult period for investors, fresh analysis suggests a more conservative approach may significantly improve the chances of making savings last.

Latest Updates

Planning

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

Superannuation

There's a reason why your super is locked up until your 60s

For decades, it seemed settled. Then one controversial idea reignited a debate that could reshape the financial future of millions. The real question isn’t who’s right or wrong, but whether a long-held assumption deserves another look.

Property

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Retirement

Under-retiring: The greatest retirement risk in a generation

Two retirees. Similar savings. Completely different lives. New research from Challenger reveals why some Australians confidently spend in retirement while others hold back and the overlooked factor shaping retirement decisions.

Five risks to watch in markets

Things you may often hear are: a recession is around the corner, markets are overpriced, the AI sector is about to flop at any moment. It’s like the never-ending laundry pile that sits in my house, it never really disappears.

Investment strategies

Do you qualify as ‘rich’?

What does it mean to be 'rich'? For something so universally desired, it is surprisingly difficult to define. That ambiguity creates a challenge for investors and raises a bigger question about what financial success really looks like.

Investment strategies

If you’re worried about your bond portfolio, you’re missing the point

Most investors think they know what bonds are for. But when markets turn volatile, a surprising misunderstanding can lead to costly decisions. Here’s the overlooked lesson that could change how you view your portfolio.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.